

Issue #32 | June 8, 2026
🥄 FIRST BITE
The appetizer before we dive in
Welcome back. Salt & Straw hired Piper Sandler to explore a $200 million exit. Fifty scoop shops. Over $100M in annual sales. Dwayne Johnson on the cap table. The premium ice cream brand that turned seasonal flavors into a cultural event is testing the market at a time when PE is circling the entire ice cream category — Blackstone and CD&R are still eyeing the Unilever spinoff at €8B+.
Meanwhile, Nestlé is buying the rest of yfood at a €450M valuation — its first acquisition under the new CEO. Bridgepoint is paying $460M for Obagi Medical from Waldencast. Lactalis acquired Protein Works because dairy giants keep diving into functional nutrition. David’s protein ice cream sold out in 28 minutes. Smash Kitchen is on pace for $100M in its second year. And Ryl Tea raised $20M after growing 157% while the rest of the iced tea category declined.
The theme this week is strategics on the move. Nestlé, Lactalis, Bridgepoint, Church & Dwight (last week), and now potentially Salt & Straw’s buyer — every large company is in acquisition mode simultaneously. The competition for the best consumer brands is intensifying. And the brands with real velocity are getting multiple suitors, not just one. Let’s dig in.
🍊 THE MAIN COURSE
This week’s biggest CPG moves
Salt & Straw Explores $200M Exit
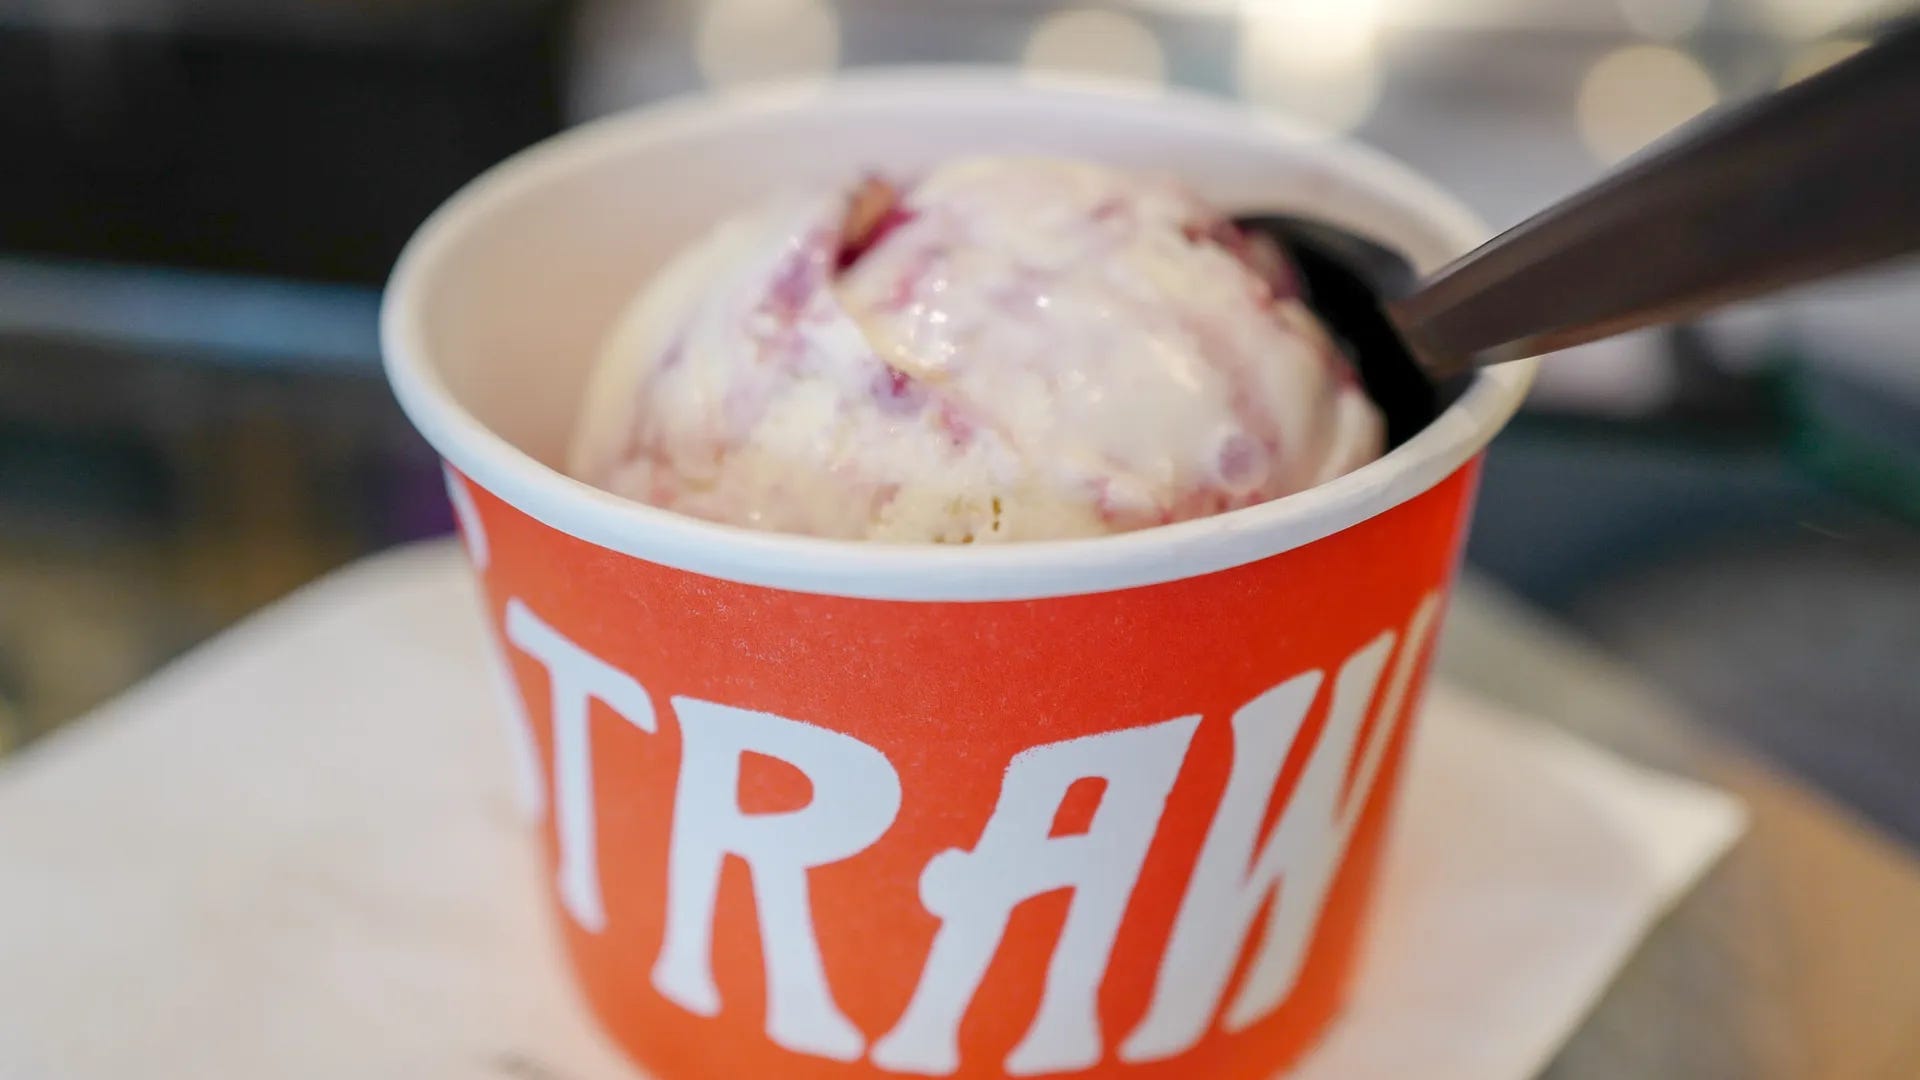
Salt & Straw tapped Piper Sandler to explore a potential $200 million exit. Founded in 2011 and based in Portland, Salt & Straw operates 50 scoop shops with annual sales north of $100M. Investors include KarpReilly, Enlightened Hospitality Investments, and Dwayne Johnson.
Salt & Straw testing the exit market at $200M makes strategic sense right now. PE firms are actively circling the ice cream category — Blackstone and CD&R are exploring the Magnum Ice Cream Company (Ben & Jerry’s, Talenti, Yasso) at €8B+. Jeni’s just hired Ben & Jerry’s former CEO. The category is getting institutional attention at every level.
At roughly 2x revenue on $100M+ in sales across 50 scoop shops, the $200M price reflects a premium ice cream brand with strong unit economics, loyal consumers, and a cultural positioning that’s difficult to replicate. The seasonal flavor drops are marketing events that drive both foot traffic and e-commerce. The question for any buyer is whether the scoop shop model scales beyond 50 locations or whether Salt & Straw’s value is in the brand, the CPG products (pints), and the cultural cachet rather than real estate expansion.
Nestlé Acquires Remainder of yfood at €450M
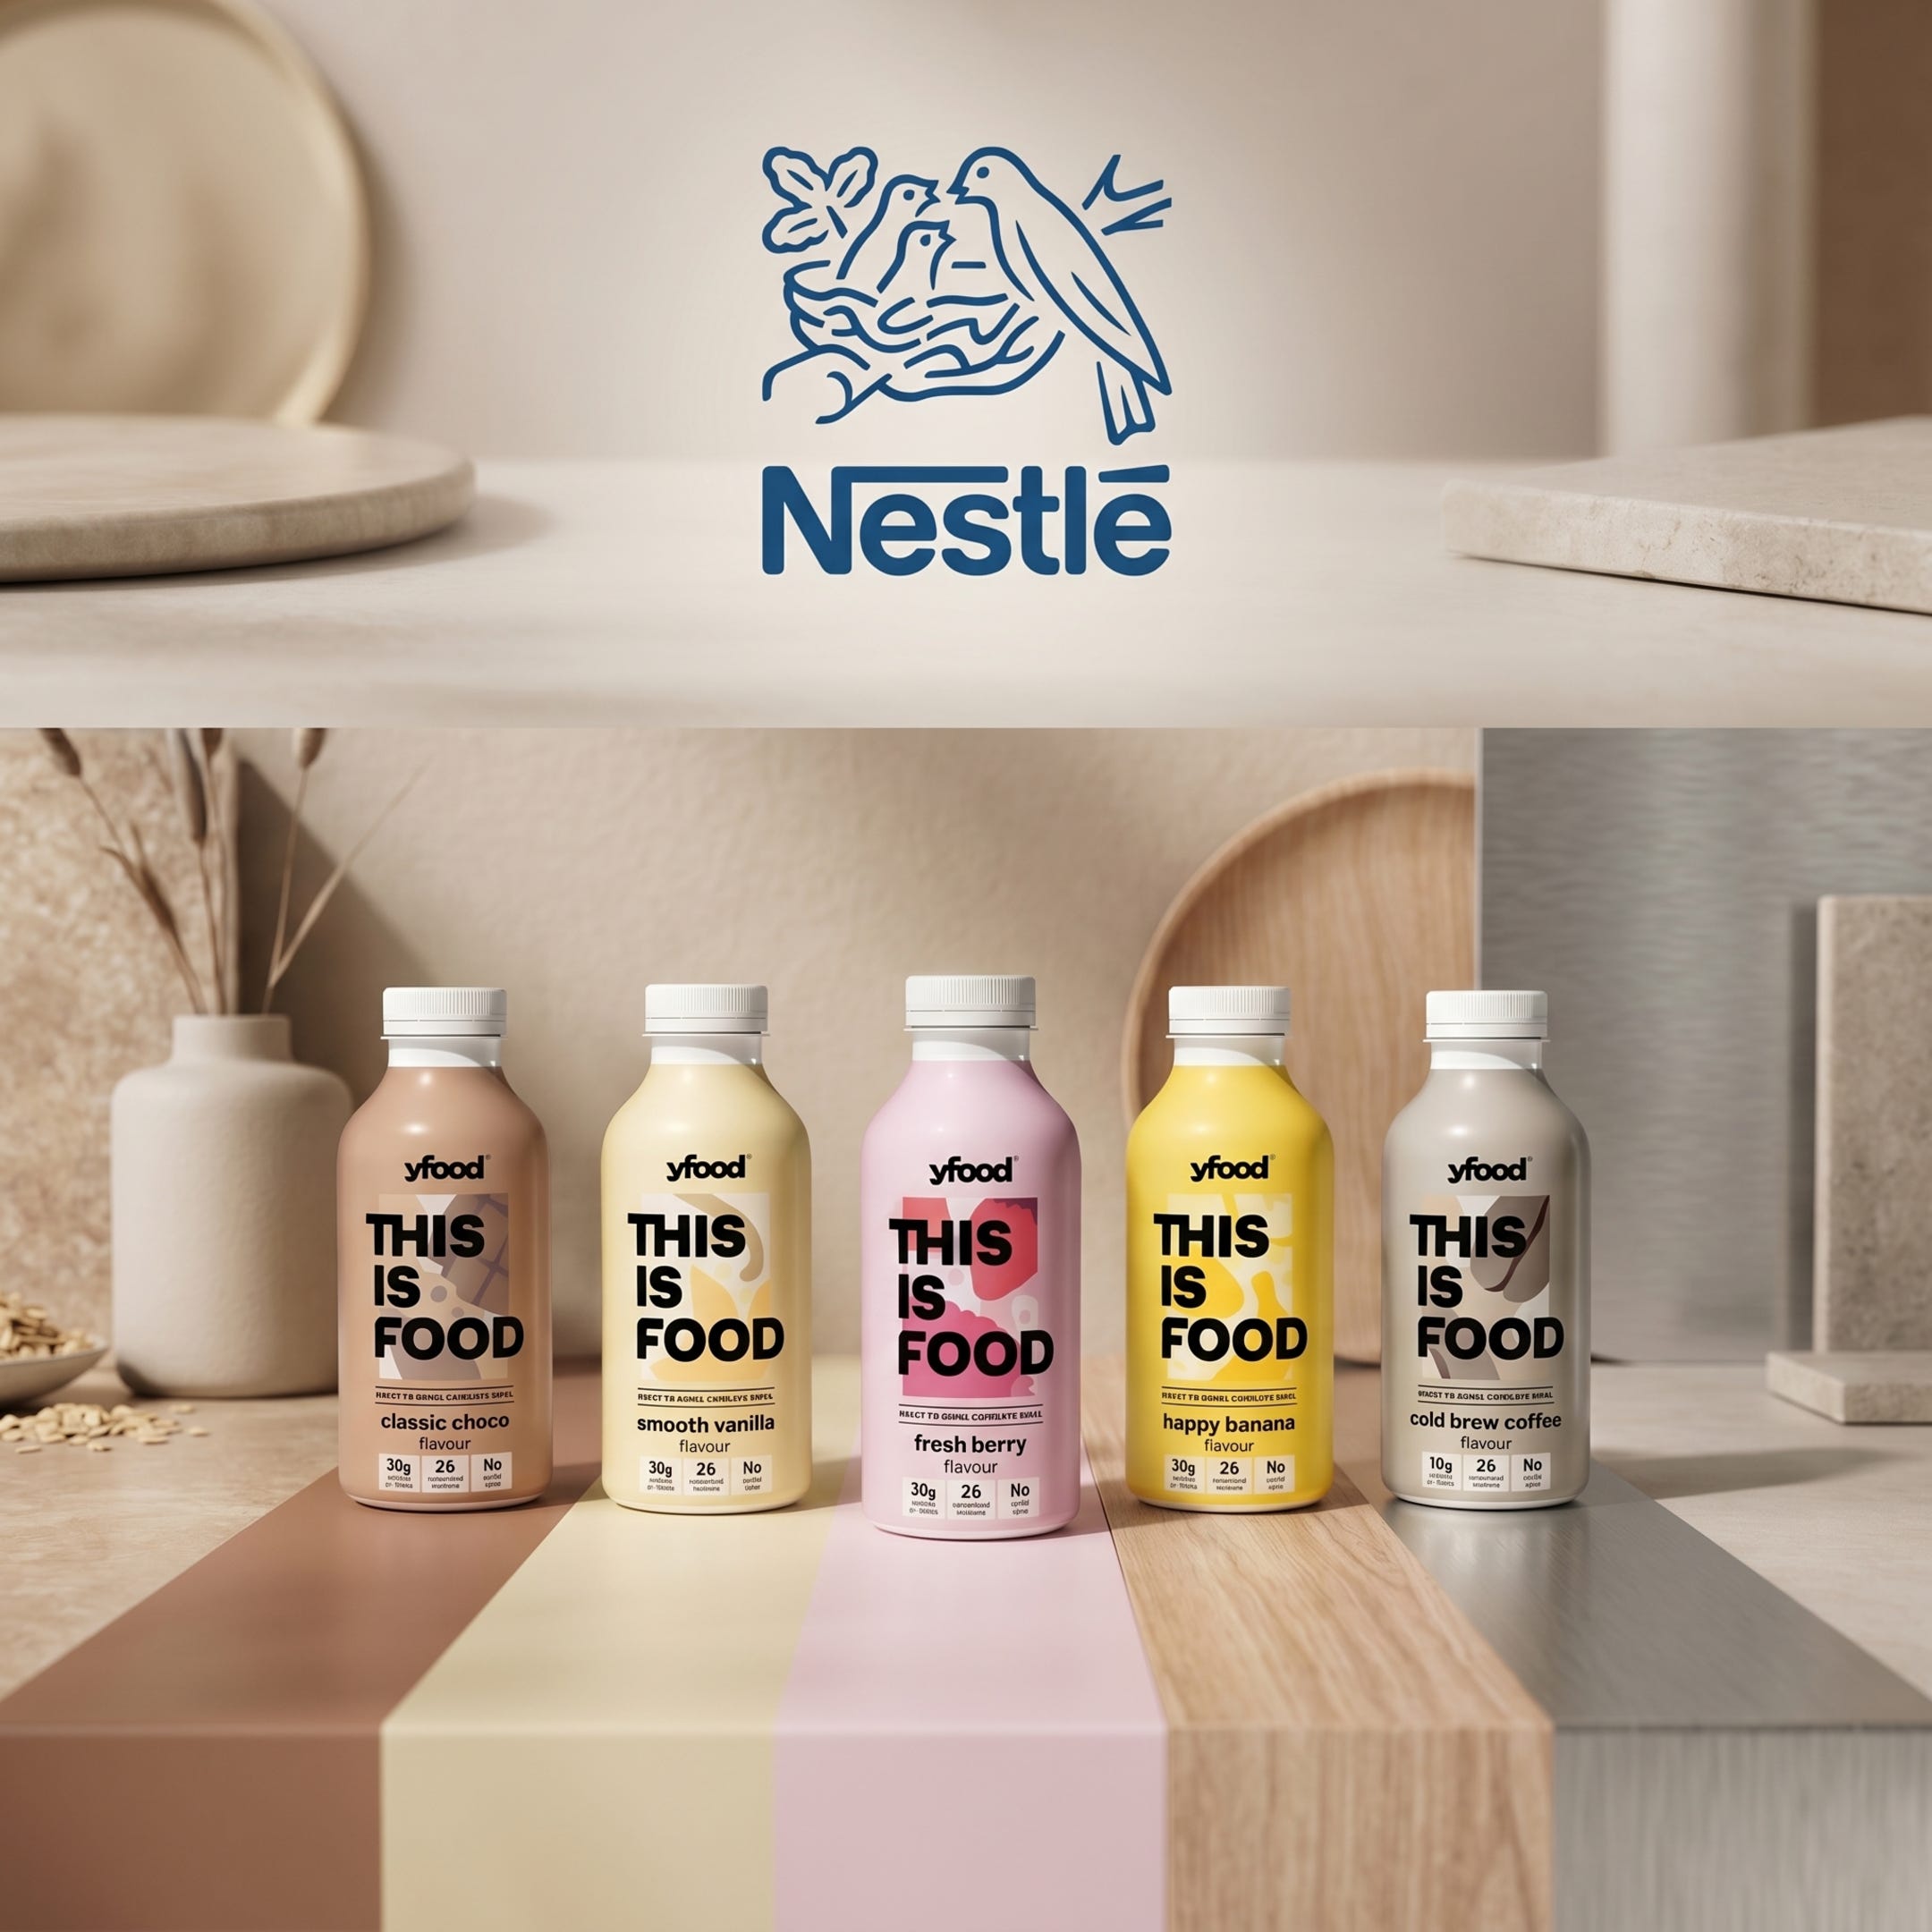
Nestlé agreed to acquire the remaining stake in yfood, a German meal replacement brand distributed in 30+ European countries. Reported valuation: €450M. First acquisition under new CEO Philipp Navratil. yfood was founded in Munich in 2017, generated nearly €150M in revenue last year with double-digit growth. Nestlé originally took a 49% stake in 2023.
Nestlé’s new CEO, making his first move with a meal replacement brand, tells you where the company sees growth. yfood, at €150M in revenue and a €450M valuation, is a 3x revenue multiple for a brand with pan-European distribution, double-digit growth, and an established product portfolio spanning shakes, powders, and bars. Nestlé going from 49% minority to full ownership follows the patient capital playbook we’ve tracked across multiple deals — Constellation did the same with HOPWTR, taking a minority first, then buying the rest.
For context: Danone acquired Huel for $1.15B earlier this year. Now Nestlé fully acquires yfood. The two largest food companies in Europe are both building functional nutrition platforms through acquisition. The complete meal replacement category is being consolidated by institutional buyers who see it as a permanent consumer behavior rather than a trend.
Bridgepoint Acquires Obagi Medical for $460M
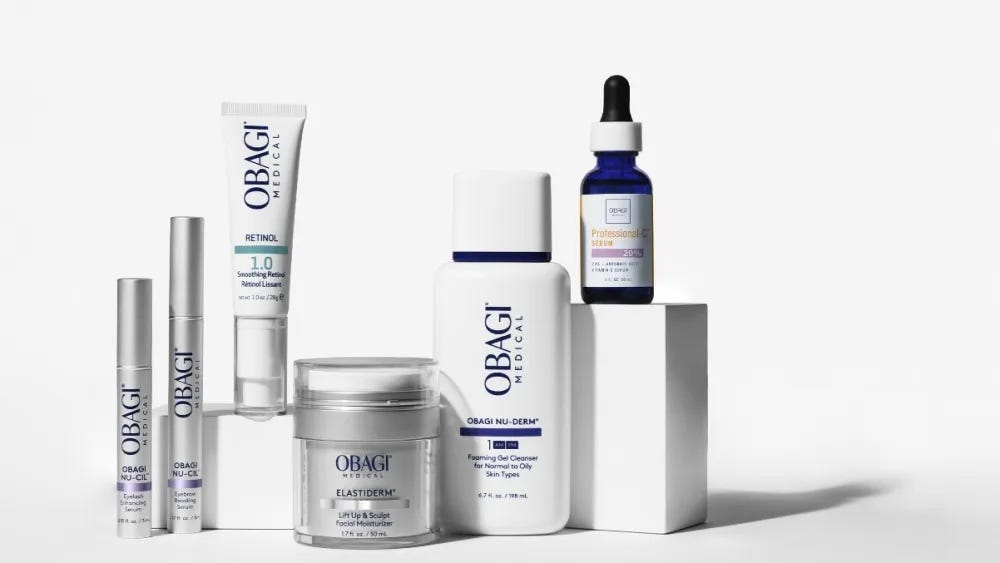
Bridgepoint acquired Obagi Medical from Waldencast for up to $460M ($366M cash, $30M vendor notes, up to $64M earnout). Waldencast will focus on accelerating Milk Makeup, which did $110M in revenue in 2025. Obagi founders Michel Brousset and Hind Sebti will transition to lead Obagi under Bridgepoint.
Waldencast choosing to sell Obagi and focus entirely on Milk Makeup is the focus-wins thesis playing out in beauty. Rather than managing two very different brands — professional dermatological skincare and trendy color cosmetics — Waldencast is concentrating on the brand with the clearest growth trajectory. Milk Makeup, at $110M in revenue, gets Waldencast’s full attention.
Bridgepoint is building a dermatological and medical aesthetics portfolio: Obagi ($460M), RoC ($500M acquisition in 2024), and Laboratoires Vivacy ($830M acquisition in 2023). Three deals totaling nearly $1.8B in the professional skincare and aesthetics space. When a PE firm spends $1.8B building a category portfolio, they’re betting that professional-grade skincare and aesthetics is a multi-decade growth story.
Lactalis Acquires Protein Works — Dairy Giants Keep Buying Functional Nutrition
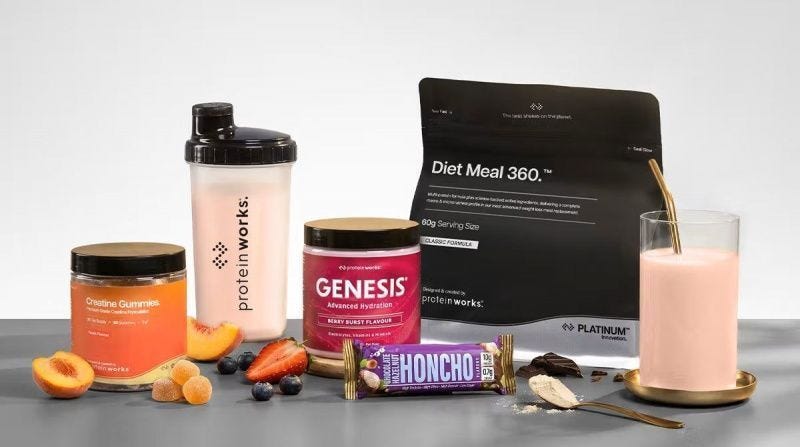
Lactalis, one of the world’s largest dairy companies, acquired UK-based Protein Works for an undisclosed sum. Founded in 2012 in Liverpool, Protein Works does around $75M in annual sales across supplements and functional nutrition.
Danone bought Huel for $1.15B. Nestlé is buying yfood for €450M. Now Lactalis buys Protein Works. The three largest dairy companies in Europe are all acquiring functional nutrition brands in the same year. The thesis is identical: traditional dairy consumption is flat or declining. Functional nutrition — protein shakes, meal replacements, supplements — is growing. Dairy companies have the manufacturing infrastructure, the supply chain expertise, and the distribution relationships. What they don’t have is the brand equity and consumer loyalty in functional formats. So they’re buying it.
Trek One Capital Acquires Good Karma Foods and No Cow
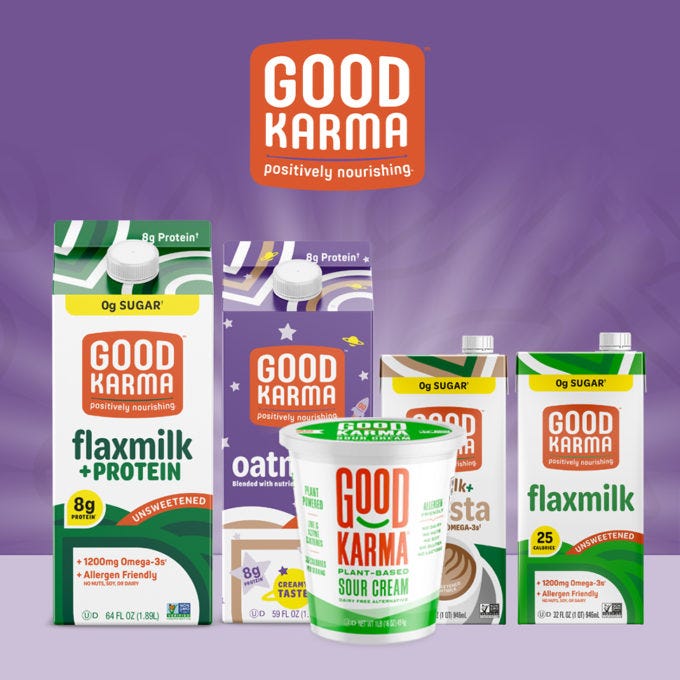
Houston-based Trek One Capital acquired Good Karma Foods (non-dairy flaxmilk leader) and No Cow (plant-based protein bars). Trek One acquired Alter Eco (an ethical chocolate company) in 2024.
A PE firm quietly building a plant-based portfolio. Flaxmilk, protein bars, and ethical chocolate under one roof. Each brand occupies a different category but shares the same consumer: health-conscious, sustainability-minded, and willing to pay a premium for plant-based. Trek One is building a platform, not collecting brands.
Helaina Partners with Nestlé for Infant Nutrition
Helaina announced a landmark partnership with Nestlé to develop early-life nutrition products using proteins identical to those found in human breast milk. The multi-year deal combines Helaina’s biotech capabilities with Nestlé’s product development and infant nutrition expertise.
This might be the most consequential food technology partnership of the year. Proteins identical to those in human breast milk are produced through precision biology, scaled up through Nestlé’s infant nutrition infrastructure. If Helaina’s technology delivers at commercial scale, it will fundamentally change infant nutrition formulation globally. Nestlé is the largest infant nutrition company in the world. Their partnership with Helaina signals that the technology is mature enough for commercial development, not just research.
💰 THE FUNDING FRENZY
Big checks being written
Ryl Tea — $20M Series C from Purchase Capital
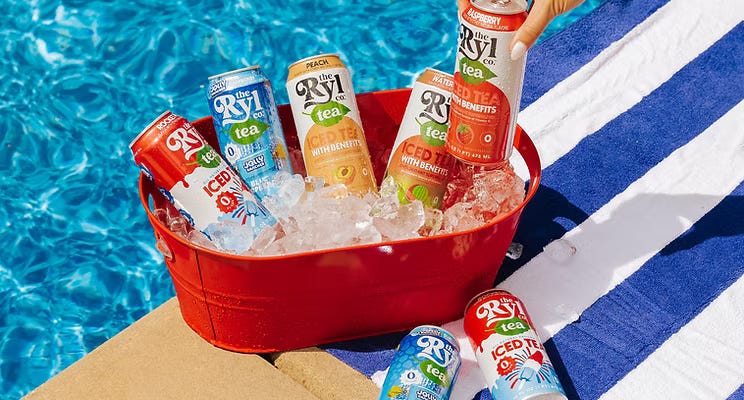
Ryl Tea closed $20M led by Purchase Capital. Founded by Blodin Ukella in 2022. Grew 157% per Circana during the 52-week period ending May 17th, while the broader iced tea category declined 1.8%. Purchase Capital previously backed OWYN, which exited in 2024 for $280M.
Growing 157% in a category that’s declining 1.8%. That’s not riding a trend — that’s creating one. Ryl Tea is stealing share from every iced tea brand on the shelf. Purchase Capital's lead is the exit signal: they backed OWYN to a $280M exit in two years. The playbook is clear — find the brand with category-defying velocity, invest, scale, exit. Ryl Tea at 157% growth is exactly the profile.
California Naturals — 8-Figure Series B from Align Ventures
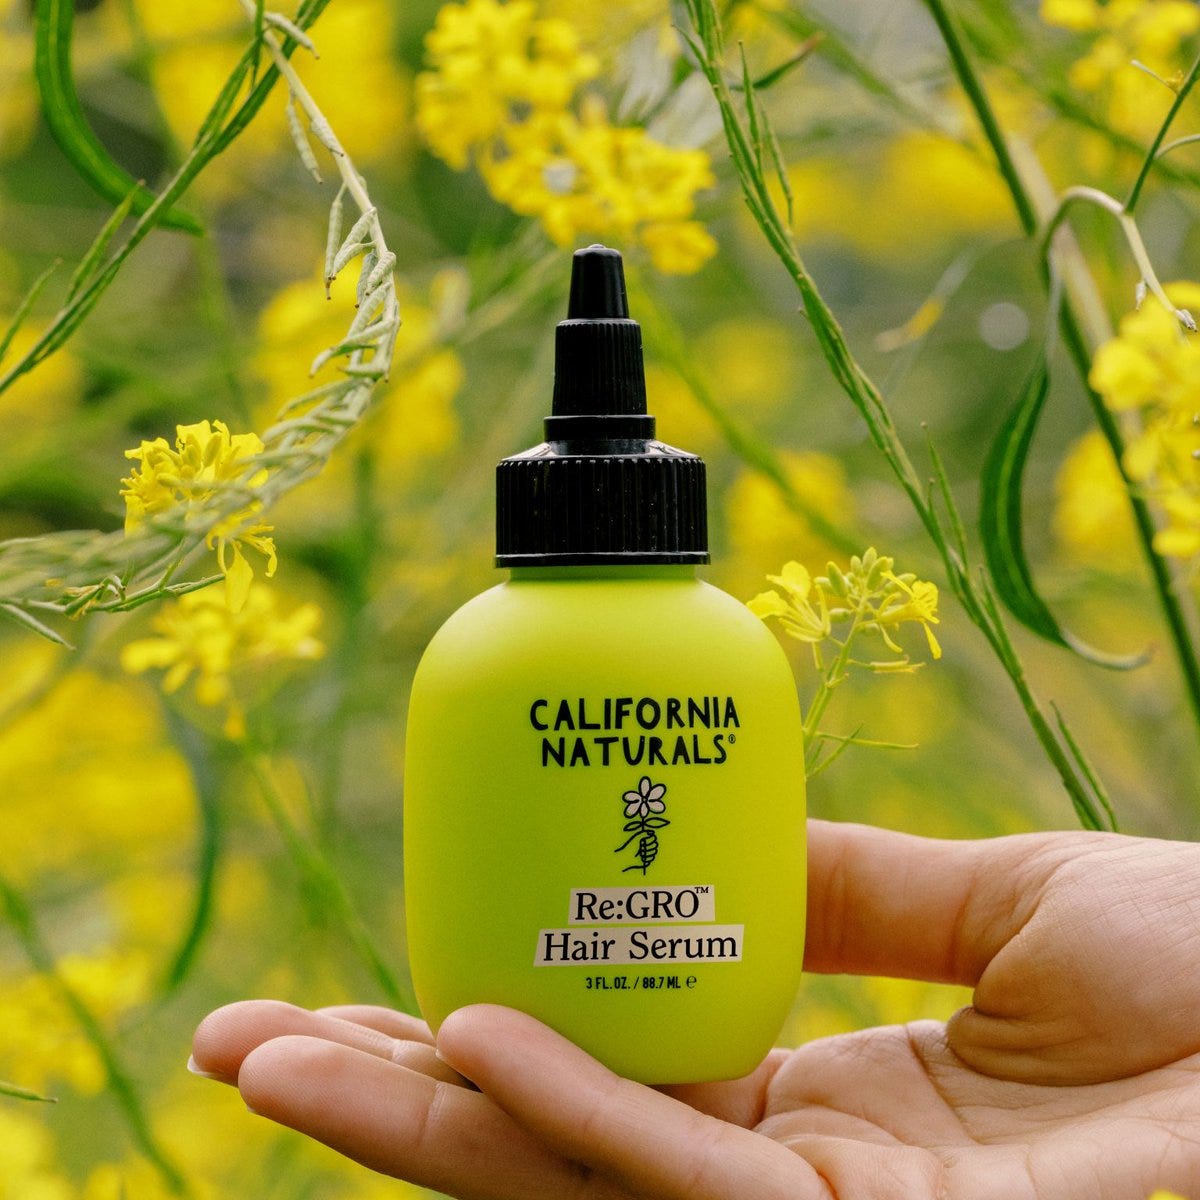
Clean personal care brand closed an 8-figure Series B from Align Ventures. COO Hayden Hiatt (former Glossier exec) stepping into the CEO role, replacing founder Shelby Wild. Distribution at Target, Ulta, CVS, H-E-B, and Sprouts. Previous backers include L Catterton, Sandbridge Capital, and Midnight Venture Partners.
The founder stepping aside for a Glossier-trained operator at the Series B stage is a mature governance decision. Hiatt bringing Glossier’s operational and brand-building playbook to a clean personal care brand already at Target, Ulta, CVS, H-E-B, and Sprouts creates a growth profile that L Catterton and Sandbridge are clearly betting on. When an L Catterton-backed brand brings in a Glossier exec as CEO, the scaling phase is beginning.
Smash Foods — $5M Equity
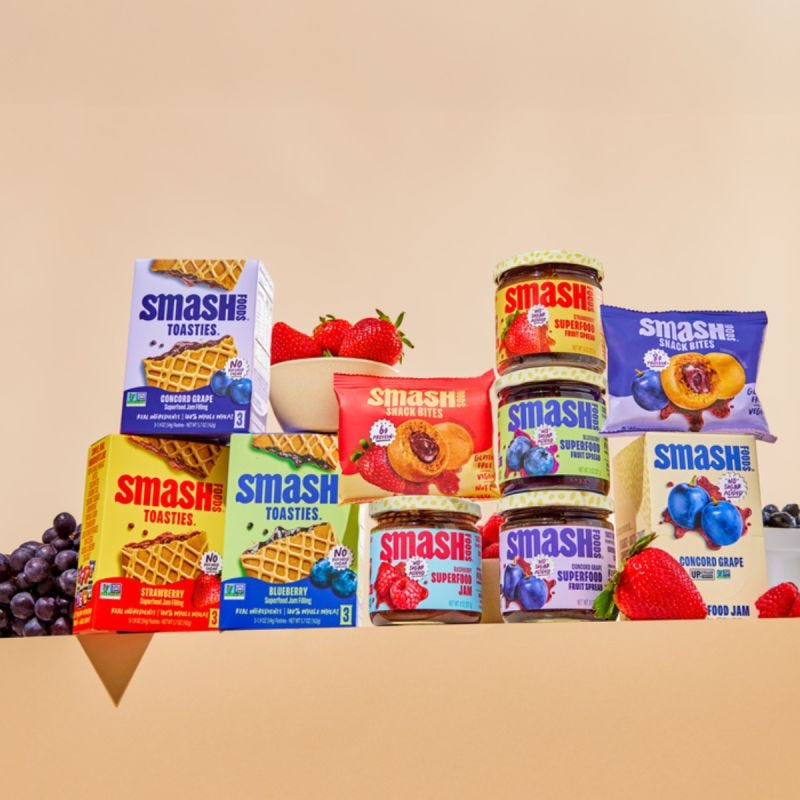
Chia-and-date superfood spread brand secured $ 5 M in funding. Founded by Anna Peck and Steve Ford in 2020. More than tripled sales last year. Previous backers: Label Capital, Family Fund, Eclair Partners.
Tripled sales. Superfood spreads and snacks in major retail. $5M to keep scaling. The functional spread category is small but growing as consumers seek alternatives to traditional peanut butter and jams that offer added functional benefits.
Filament — $2M Seed from Wittington Ventures
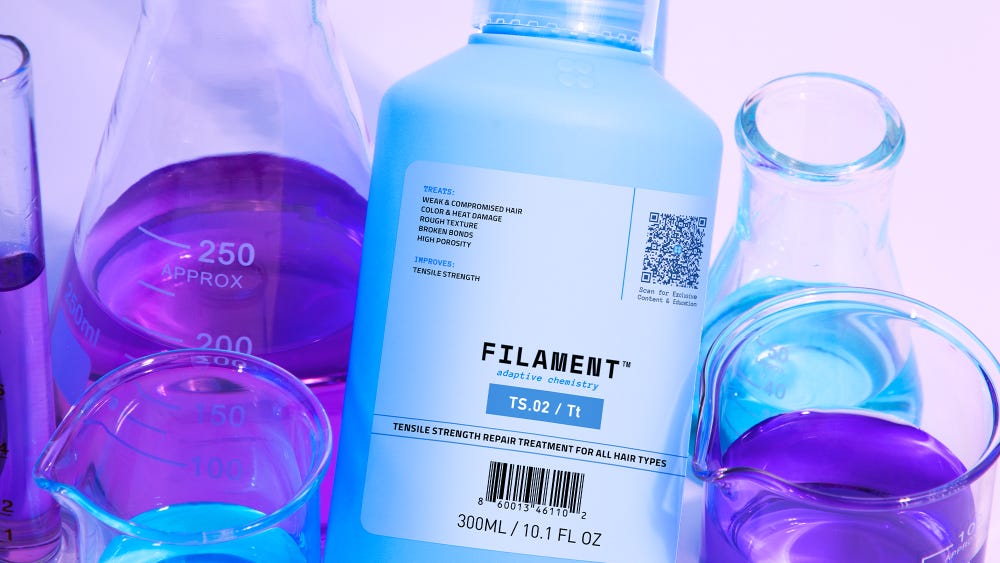
Science-backed haircare brand focused on the professional stylist channel closed $2M in funding from Wittington Ventures and Willow Growth Partners. Founded by L’Oréal veteran Nathan Puksta.
A L’Oréal veteran building a haircare brand for the professional channel — the exact channel L’Oréal dominates. Puksta knows the salon distribution model intimately. Wittington Ventures suggests they see the same opportunity in professional haircare that True Beauty Ventures saw in Crown Affair and K18. The professional channel creates credibility that flows into consumer retail.
VitaHustle — Growth Equity from Axum Capital
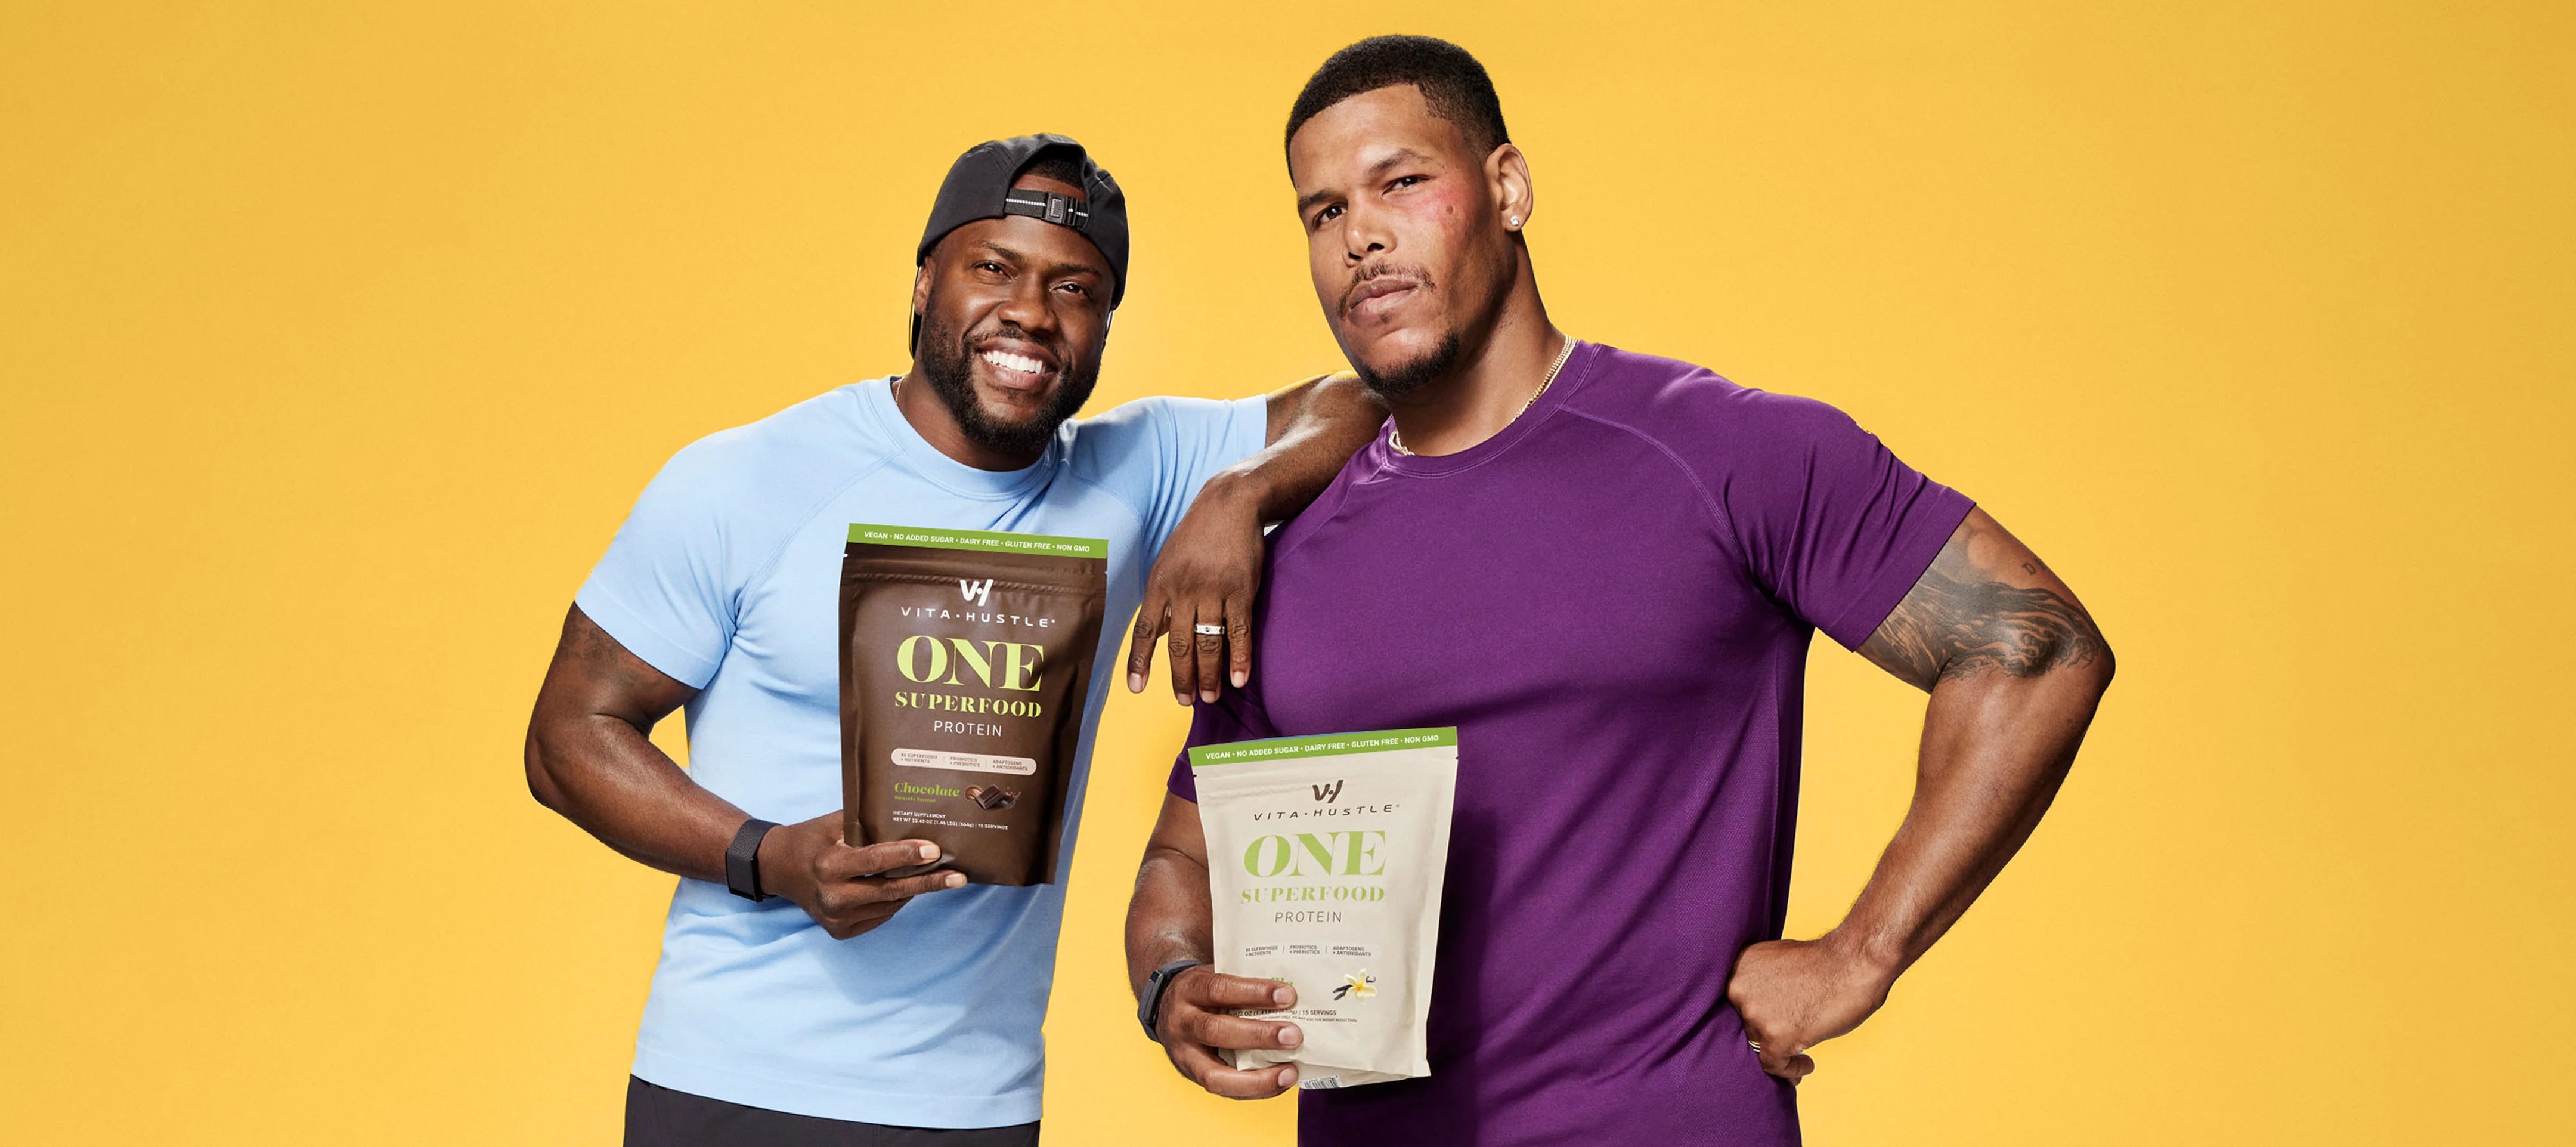
Kevin Hart and Ron Everline’s all-in-one nutrition brand secured growth equity from Axum Capital Partners. 20g plant-based protein, 86 superfoods. Available on DTC, Amazon, QVC, and iHerb.
Kevin Hart brings the audience. But VitaHustle’s growth-equity stage and QVC/iHerb distribution suggest the brand is building through direct-response and digital channels rather than traditional retail. The all-in-one nutrition shake format competes with AG1, Grüns, Ka’Chava, and a growing list of daily wellness shakes. The differentiator is Hart’s audience and the plant-based positioning.
Lune & Wild — €2.3M Series A from Guinness Ventures
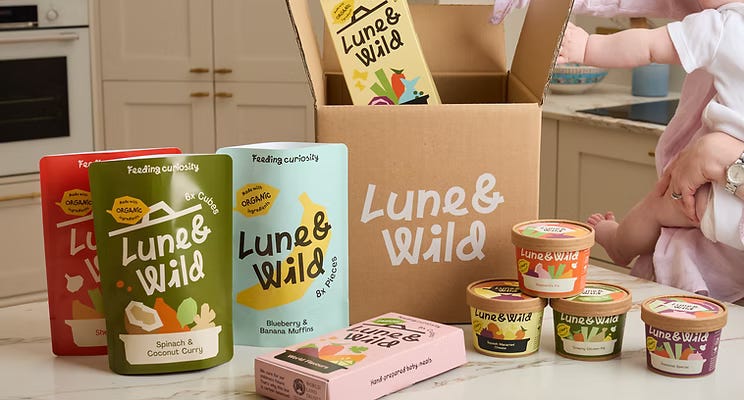
London-based baby and children’s food brand secured €2.3M from Guinness Ventures with strategic angels. Founded in 2021 by Lara Rodgers and Nadia Simonds. Chef-crafted recipes and pediatric nutrition expertise. Sold over 1 million meals in the past 12 months.
A million meals in twelve months for a children’s food brand at the Series A stage. The chef-crafted positioning in baby food follows the same premiumization thesis driving brands like Little Spoon ($1M weekly at Target), Serenity Kids, and Once Upon a Farm ($73M Q1, up 43%). Parents keep trading up for better-quality children’s nutrition. The European market for premium baby food is large and growing.
Patina — $2M from Betaworks and True Ventures
Fragrance tech company using machine learning and molecular design to produce novel scent molecules. Aims to sell molecules to fragrance houses and cosmetics companies.
B2B fragrance tech is a different thesis than consumer-facing brands. Patina isn’t building a brand — it’s building the ingredient infrastructure that brands use. If their AI-generated scent molecules perform at commercial quality, every fragrance house and cosmetics company is a potential customer. Betaworks and True Ventures’ backing signals tech investor conviction that AI can meaningfully innovate at the molecular level in fragrance.
Applied Nutrition — Acquires Nutrablend Assets for $16M
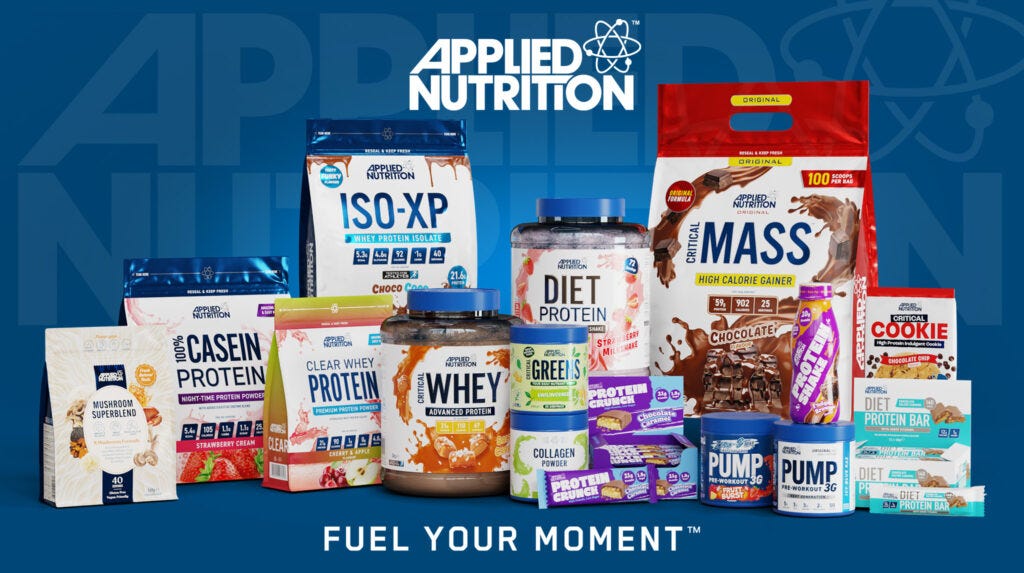
UK-based Applied Nutrition acquired a 107,000-square-foot manufacturing facility in Buffalo and two brands (Basic Supplements, GR8 Lifestyle) for $16M. Applied Nutrition revenue up 57% to £74.5M in H1 FY26.
A supplement brand is growing 57% buying manufacturing capacity in North America. Applied Nutrition is vertically integrating its U.S. operations — owning production gives margin control and speed-to-market that contract manufacturing can’t match. The same playbook WILDE just executed with its 130,000-square-foot facility. When supplement brands reach this growth rate, owning manufacturing becomes a strategic imperative.
🆕 PRODUCT LAUNCHES & INNOVATION
This week’s innovation circus
David Protein Ice Cream Sells Out in 28 Minutes
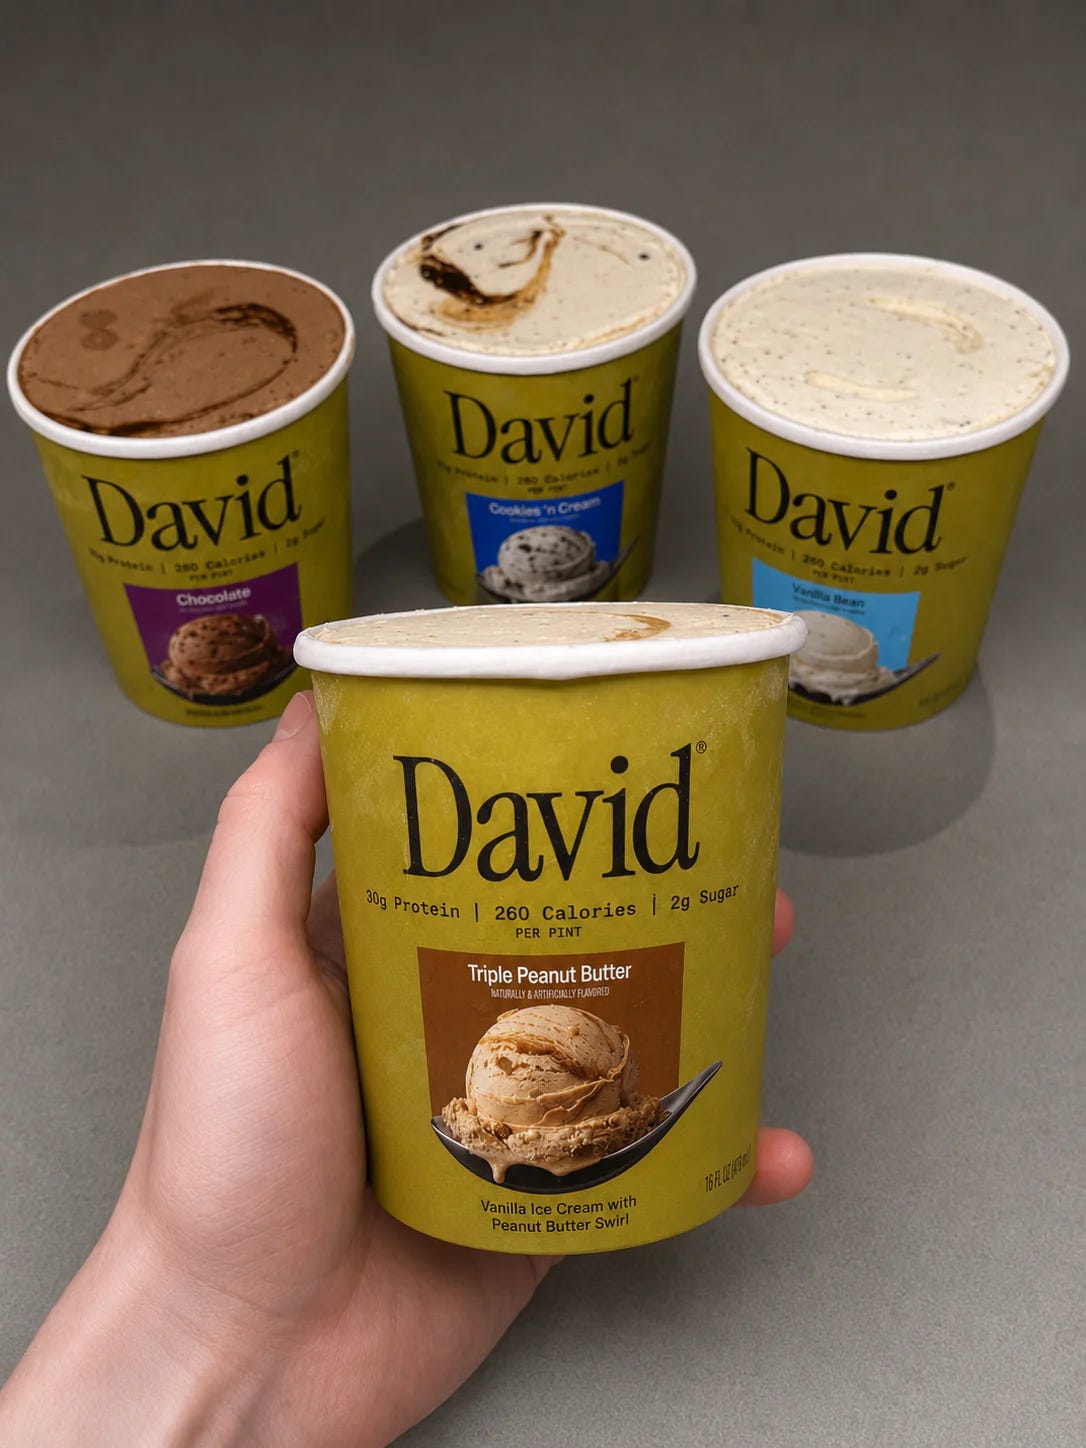
David launched protein ice cream with four flavors: Vanilla Bean, Cookie Dough, Triple Peanut Butter, and Triple Chocolate. 30g protein, 1-2g sugar, 210-260 calories per pint. 6-pack at $90. Sold out in 28 minutes.
Ninety dollars for six pints of protein ice cream. Twenty-eight minutes to sell out. Peter Rahal continues proving that the David consumer will pay a premium for anything the brand touches — protein bars, canned cod in golden tins, and now $15-per-pint ice cream. The protein ice cream category is getting crowded (Frozen One, Smearcase, Halo Top, RYSE), but nobody else is charging $90 for six pints and selling out in under half an hour. The brand premium David commands is unmatched in the functional food space.
BERO Summer Shandy at Target
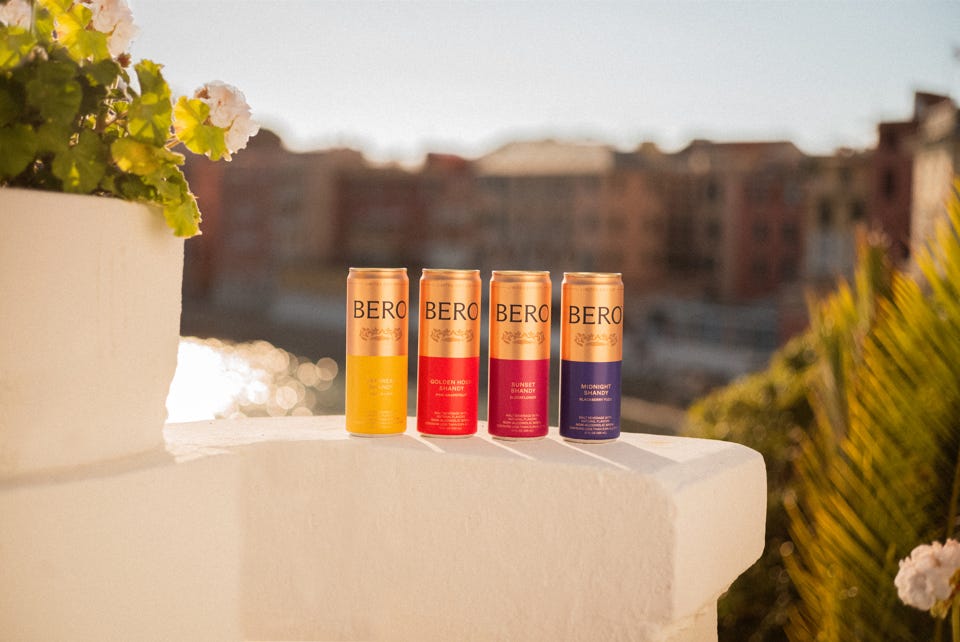
BERO launched a limited-edition Summer Shandy Collection — 30% Kingston Golden Pils, 70% lemonade. Debuting at Target on June 14th before expanding to BevMo, Total Wine, Sprouts, Gelson’s, and others.
Tom Holland’s non-alc beer brand is turning seasonal releases into retail events. The shandy format targets the summer casual drinker who might not buy a non-alcoholic beer year-round but wants a refreshing option for pool parties and barbecues. Target, as the launch retailer, continues BERO’s strategy of using Target for debut moments before broader distribution. Full national grocery in under two years and now seasonal limited editions at Target — BERO keeps building the playbook.
Frosh Kids Juice Boxes at Target — Ciara and Russell Wilson
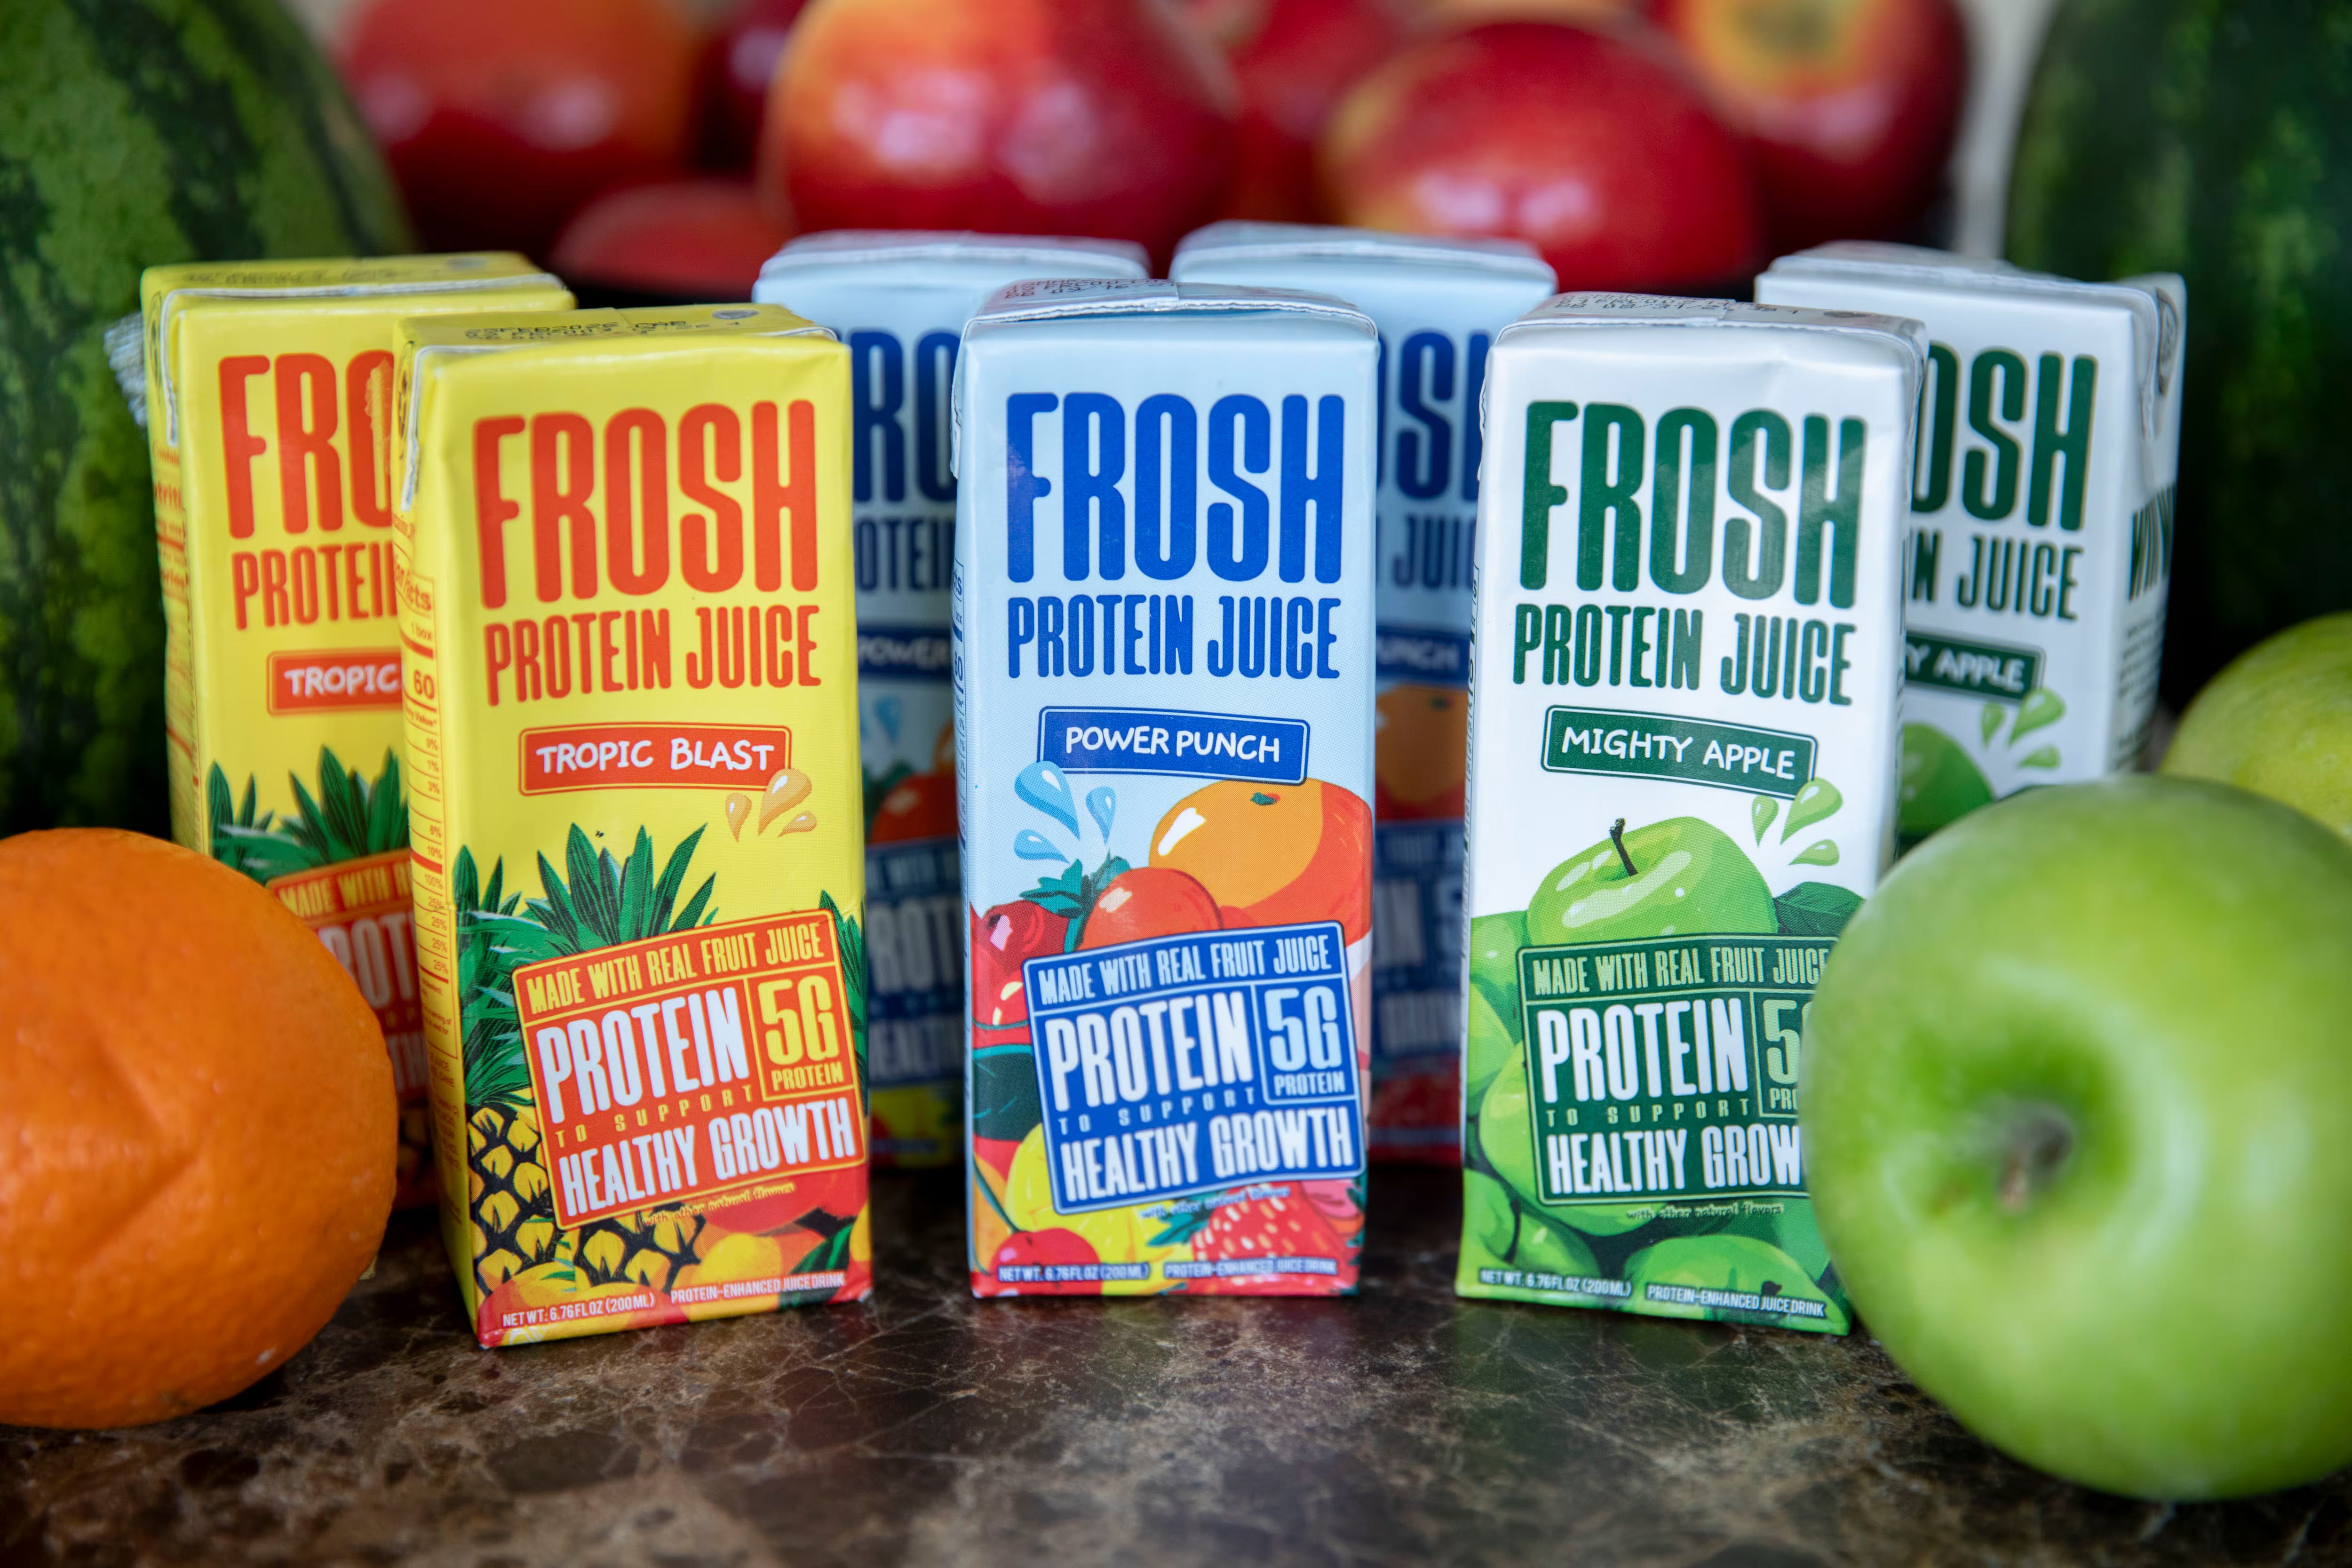
Kids’ nutrition platform Frosh, developed by talent-led venture studio VO/D, launched functional juice boxes nationwide at Target. 5g protein, real fruit juice, vitamins, and minerals. Co-founded by Ciara, Russell Wilson, and the LaBrant Family.
Celebrity-backed kids’ nutrition at Target. Frosh’s advantage is the venture studio model (VO/D), which provides the operational infrastructure behind the celebrity names. The functional juice box format — protein plus vitamins in a format kids already love — addresses the same thesis as Roxberry and NoBiggie: parents want better options in formats kids won’t reject.
Smash Kitchen Approaching $100M
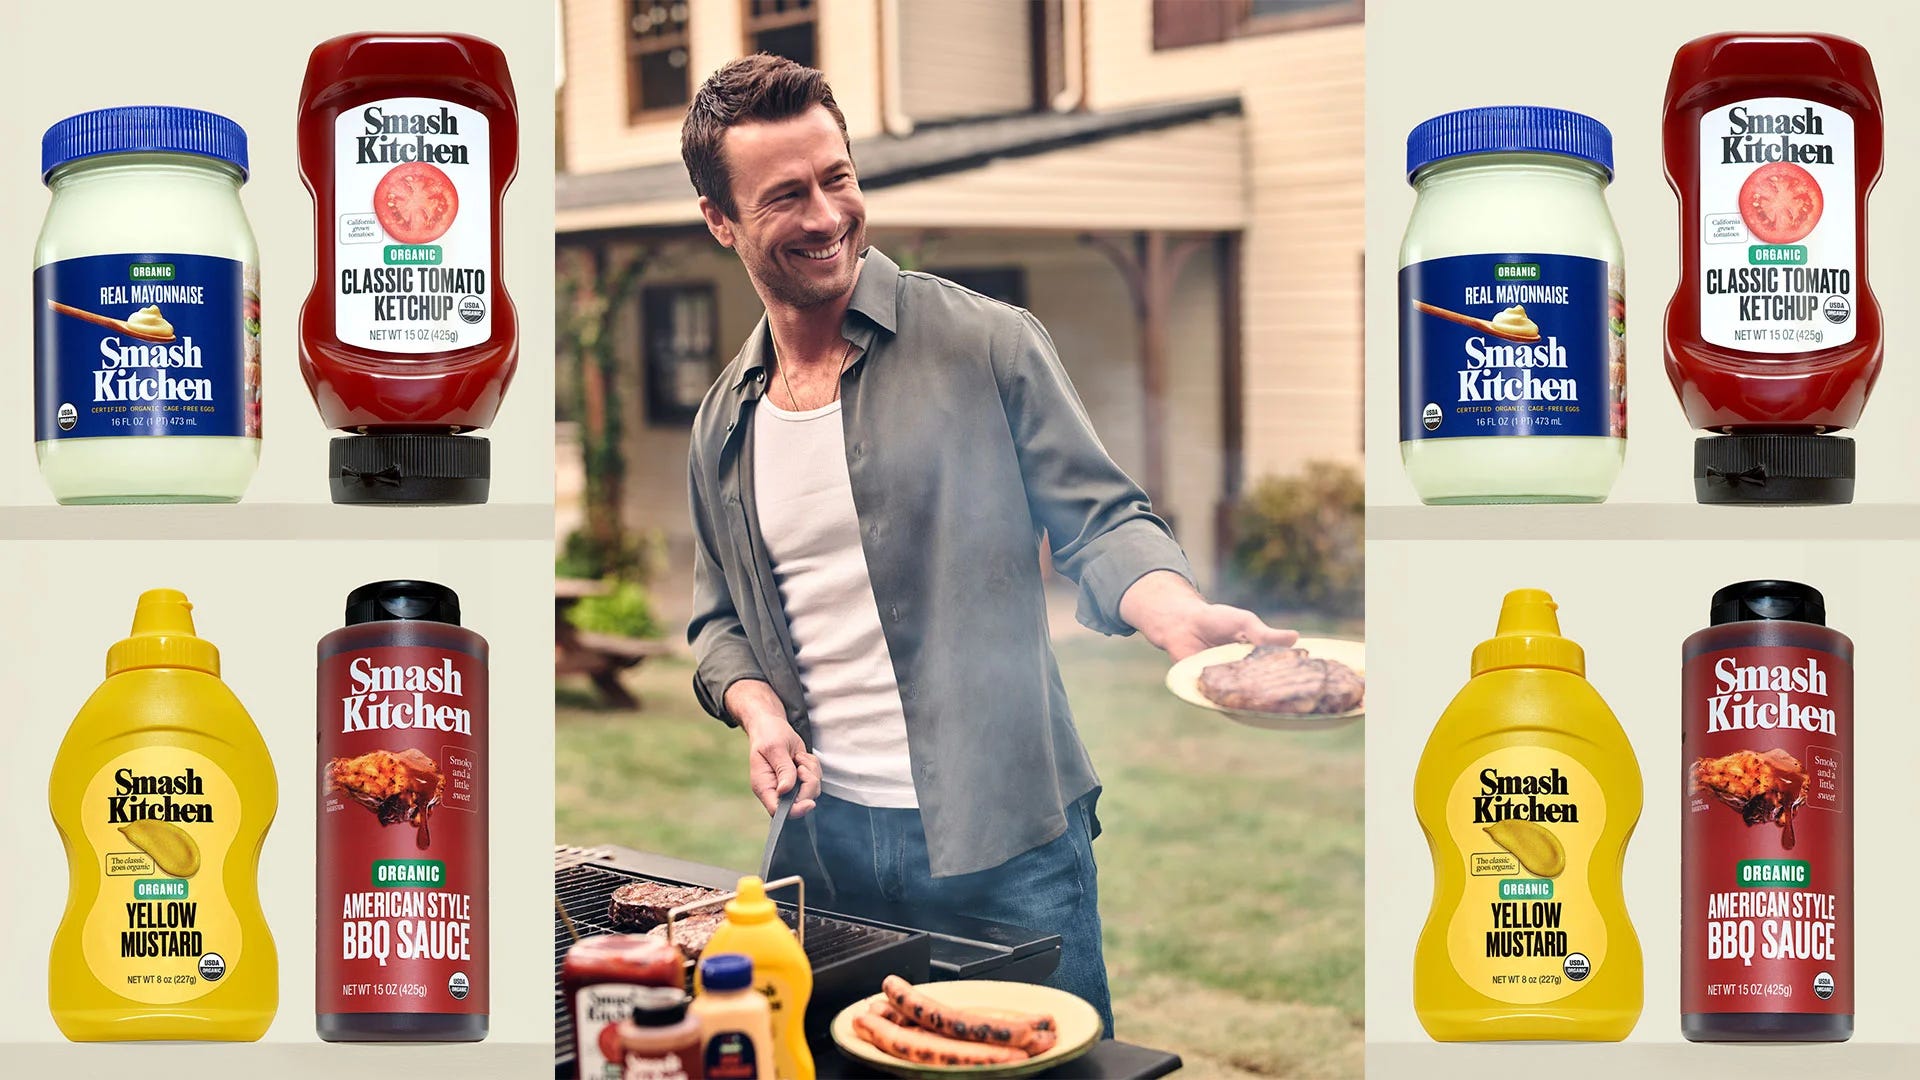
According to Inc. Magazine, Glen Powell’s Smash Kitchen is set to surpass $100M in annual retail sales by the end of 2026. The clean condiments brand debuted at Walmart last April and has expanded to nearly 15,000 doors.
From Walmart launch to $100M in under two years. Fifteen thousand doors. The Glen Powell effect is real — but the velocity sustaining beyond the celebrity launch period proves the products earn repeat purchase. Clean condiments at Walmart are a massive category opportunity. Smash Kitchen is proving velocity at this scale across hot sauce, kettle chips, popcorn, and dressings, positioning it as one of the most successful celebrity CPG brands of the decade.
More Launches Worth Watching
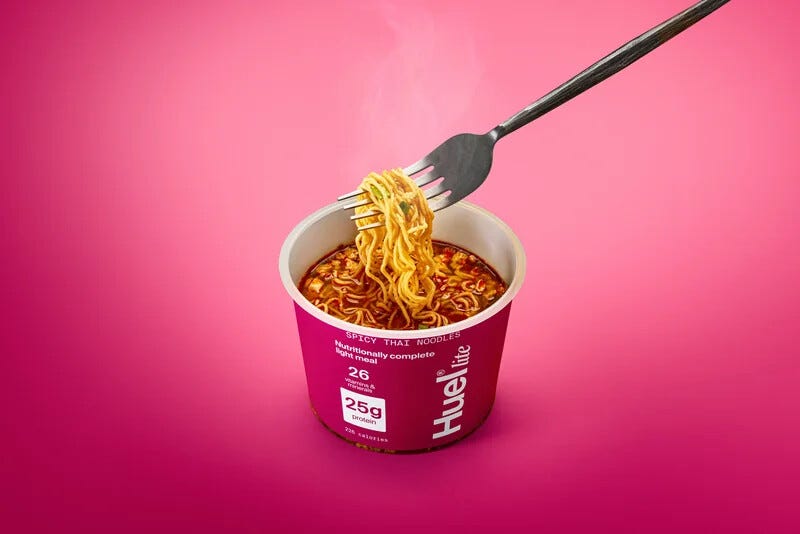
Huel Lite Ramen — 25g protein, fiber, 26 vitamins and minerals in three flavors. Danone’s $1.15B acquisition brand entering the functional ramen category.
Magic Spoon Protein Oatmeal — 15g protein, 6g fiber, 1g sugar. Apple Cinnamon and Maple Brown Sugar at Walmart and Instacart. The cereal brand enters adjacent breakfast formats.
AG1 Omega-3 and Omega-3 + CoQ10 — wild-caught fish oil. AG1 keeps expanding beyond its hero product under Kat Cole. Now at Walmart alongside DTC.
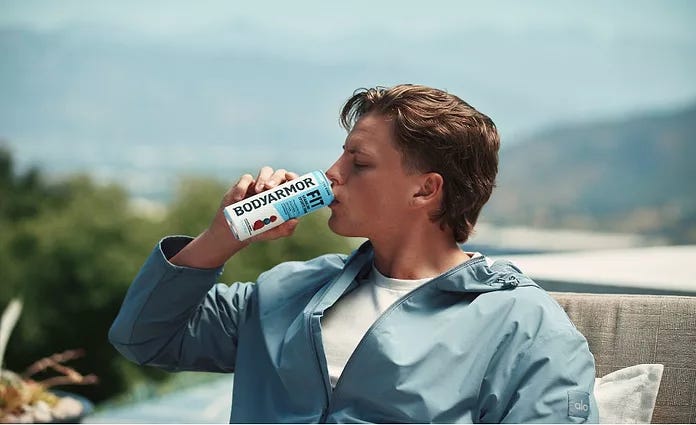
Coca-Cola BodyArmor Fit — sparkling sports drink with 290mg electrolytes, 60mg caffeine, green tea extract. Five flavors. BodyArmor enters the sparkling functional category.
MAC Energy landing Kroger, Albertsons, and other retail cut-ins before its July 12th launch. Conor McGregor’s energy drink securing retail distribution pre-launch.
Crisp Power opened a $15M production facility in Texas — high-protein pretzels moving from Israeli imports to domestic manufacturing.
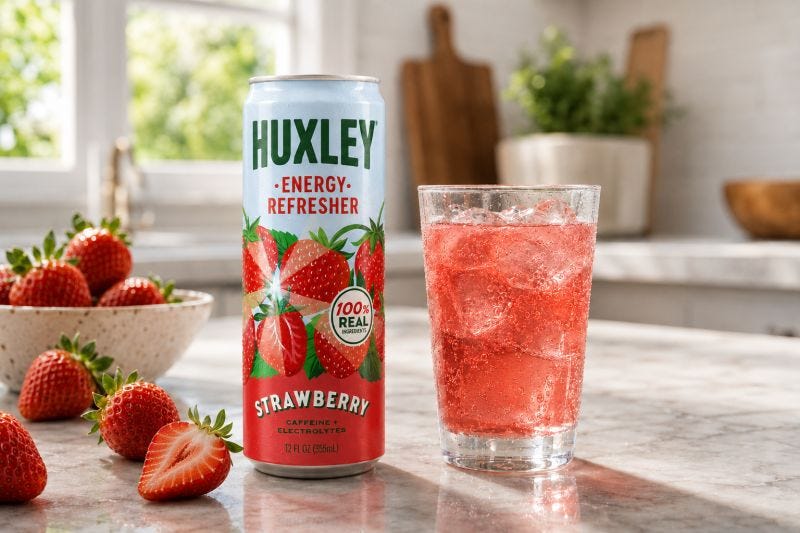
Huxley repositioning from pure energy to “Energy Refresher” — smart pivot given Starbucks Refreshers’ dominance with no RTD competitor in the format.
Roadie — zero-alcohol, zero-calorie beer from LA. Branding by LAND. Available at SoCal independents.
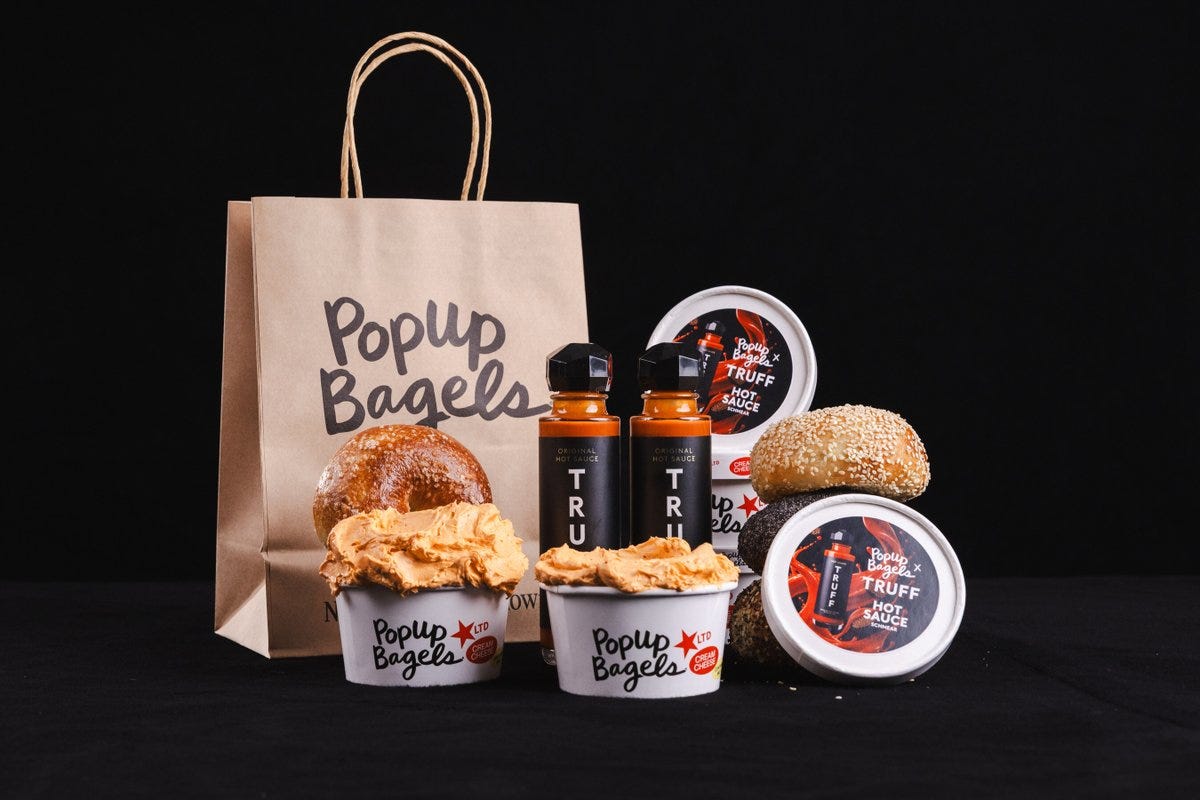
TRUFF x PopUp Bagels Hot Sauce Schmear. Also released TRUFF x KITH co-branded sauce earlier this month. The collabs keep coming.
Snif Body Whips — bestselling scents in body care format with skincare-level ingredients at Sephora.
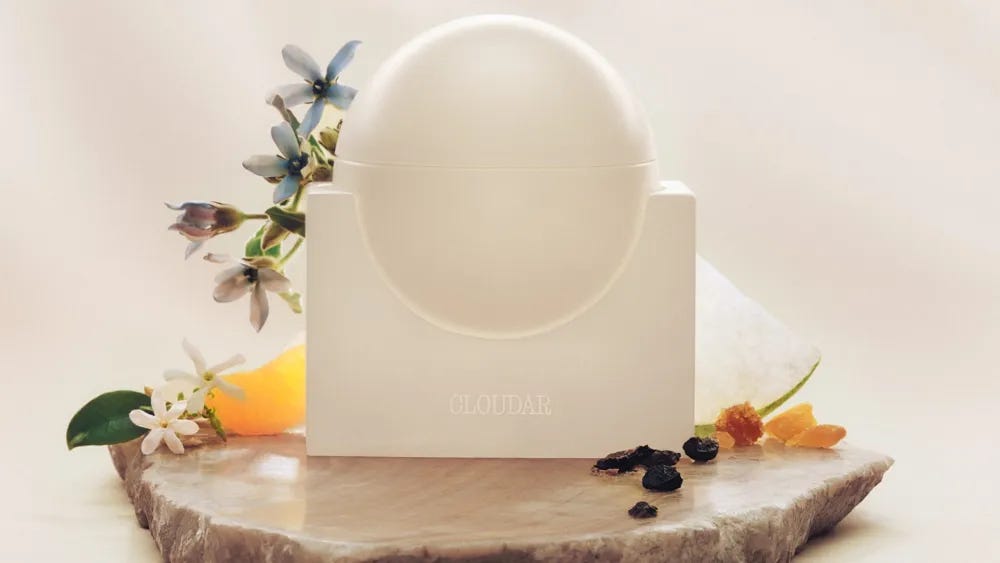
Drake’s Better World Fragrance House launching Cloudar — fragrance #2 with longtime perfumer Michael Carby.
Neuro limited-edition Watermelon Energy & Focus Gum at Walmart.
La Pulga Double Barrel Reposado — Blue Weber agave aged 7 months, finished in Still Austin bourbon barrels.
Sweet Addison’s x Ice Cream for Bears Hot Fudge Cookie collab.
Karen Behnke (Juice Beauty founder) launched BeautyCrush Skincare — regenerative biotech with plant exosomes and grapes from her organic Sonoma farm.
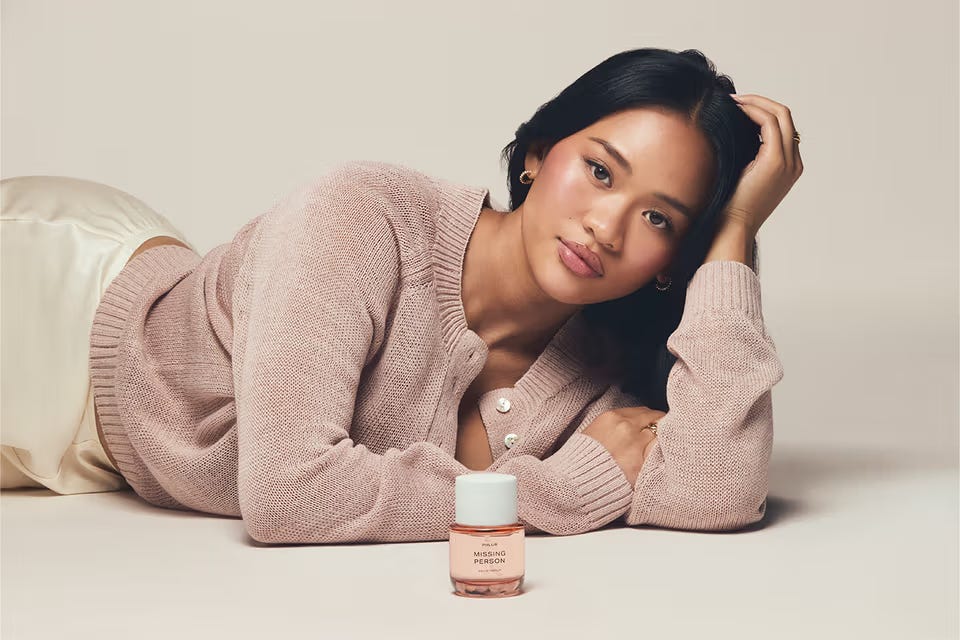
Suni Lee as first celebrity partner of PHLUR, the fragrance brand TSG acquired in 2025.
📊 THE DATA DIGEST
Numbers that matters
Smash Kitchen: On Pace for $100M
Glen Powell’s clean condiments brand is approaching $100M in its second year. Nearly 15,000 doors. From Walmart launch to nine figures in under two years.
OLIPOP Volume Up 18%
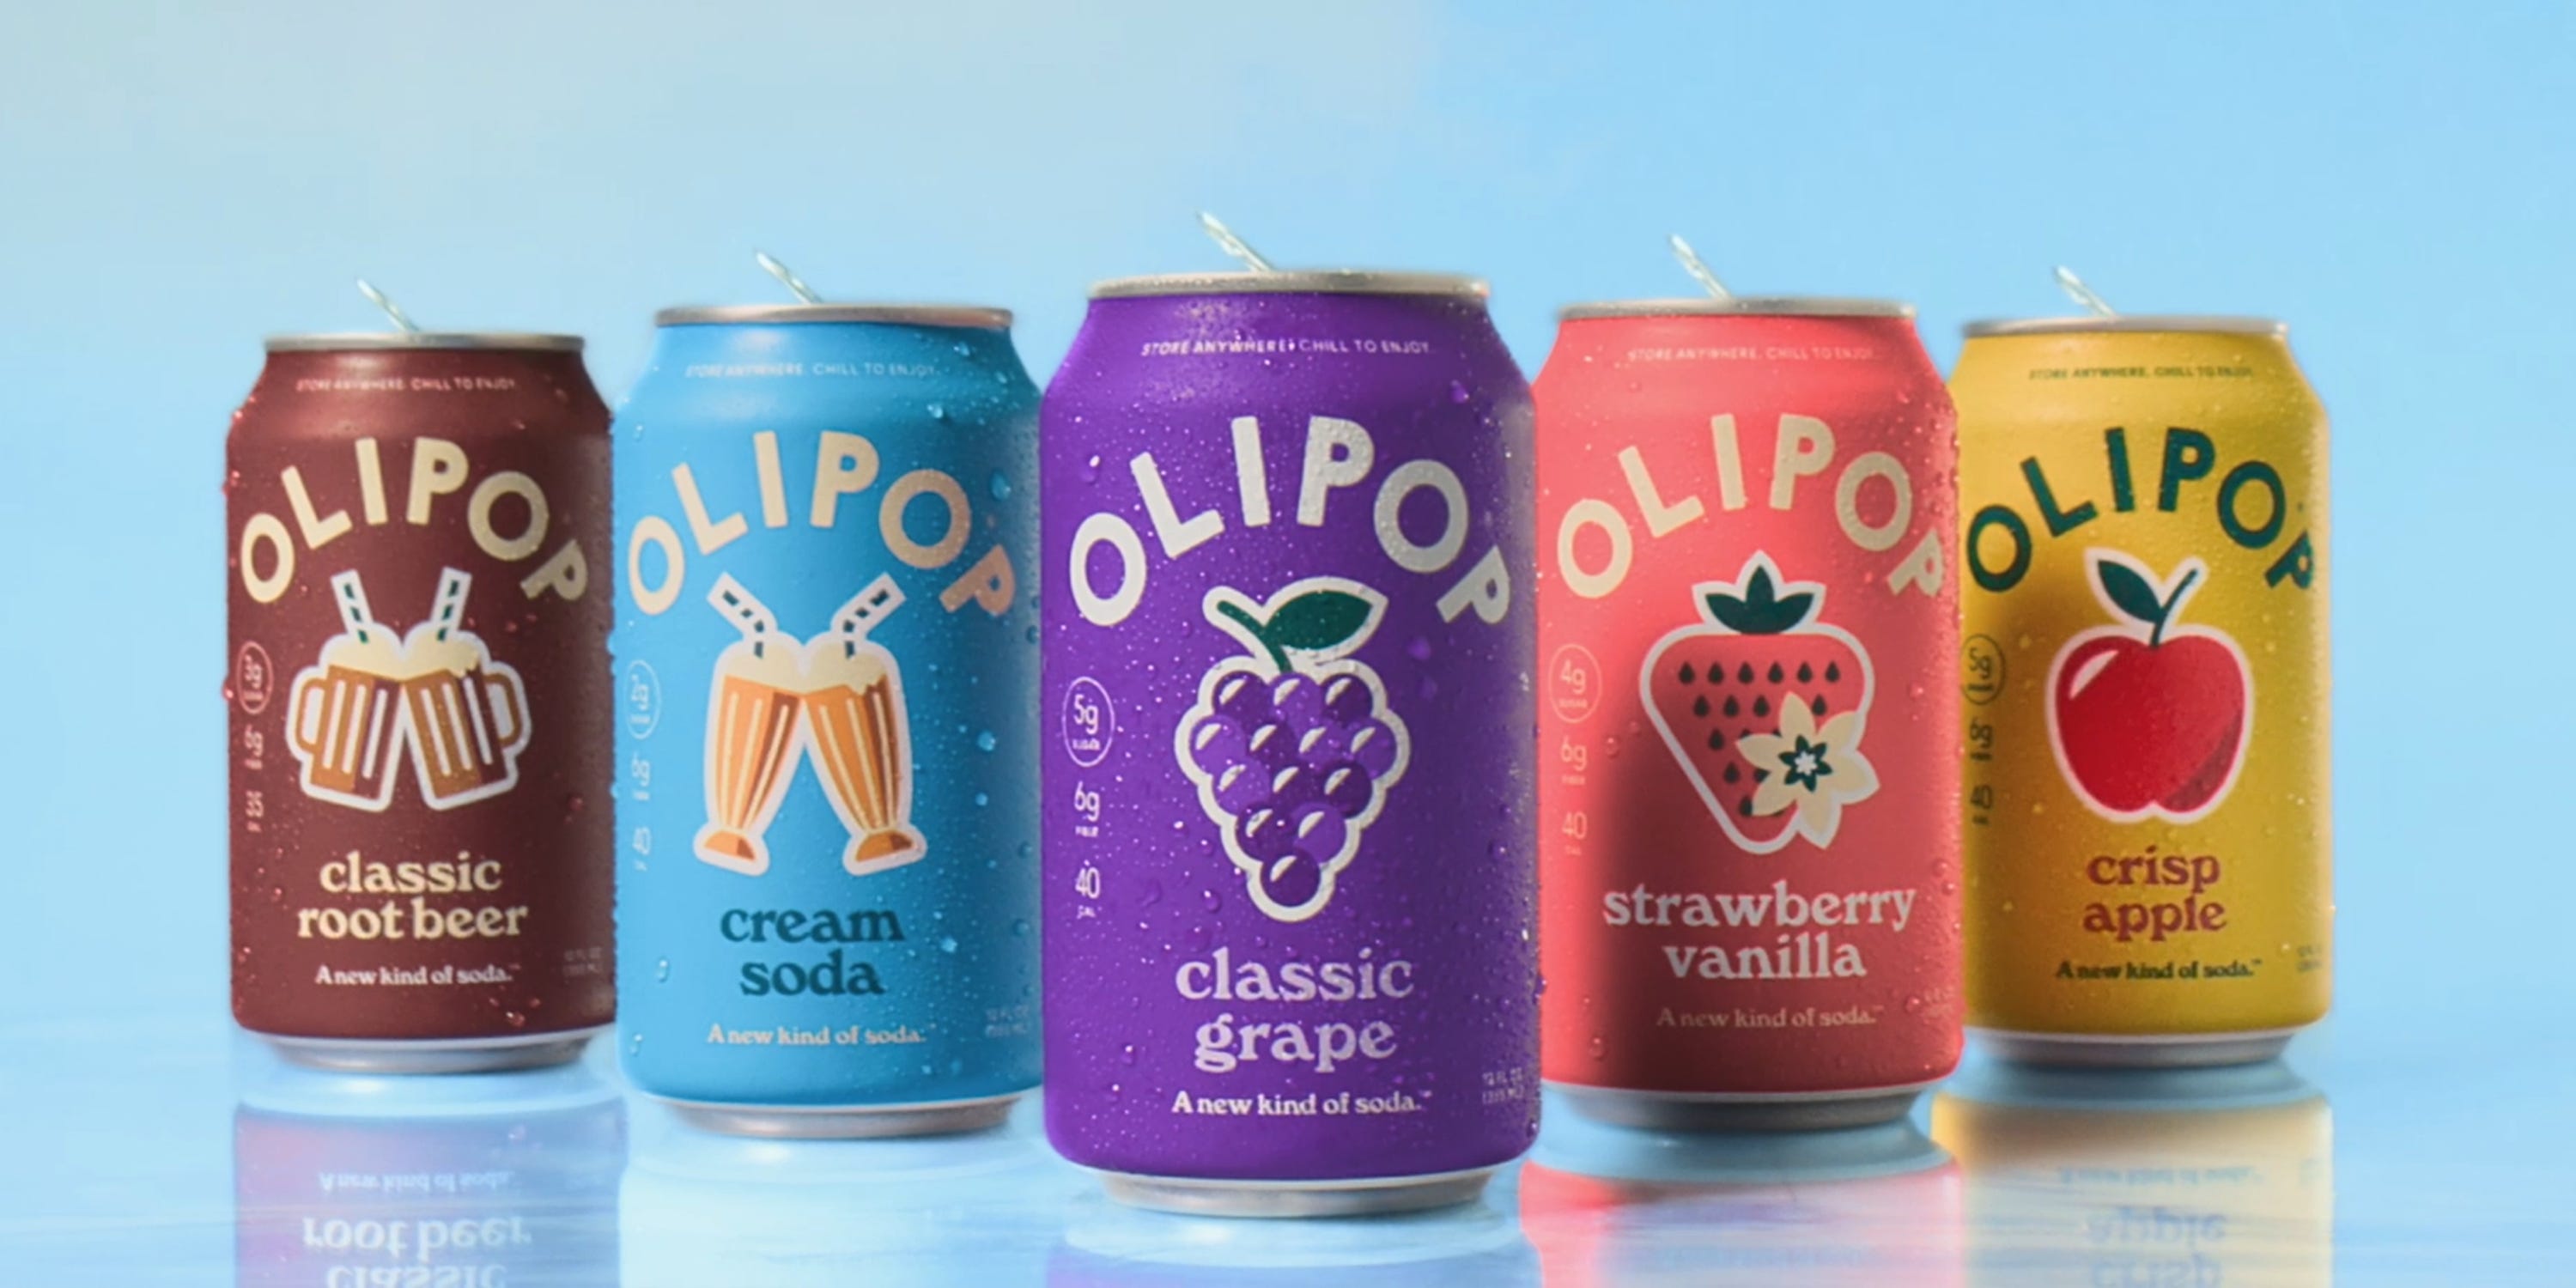
Volume jumped 18% in the four-week period ending May 16th. Following 17.5% and 22.3% in previous periods. The packaging refresh is working. Walking away from Coca-Cola, raising $200M, and still posting consistent double-digit volume growth.
Brown-Forman Q4: Stock Up 3%
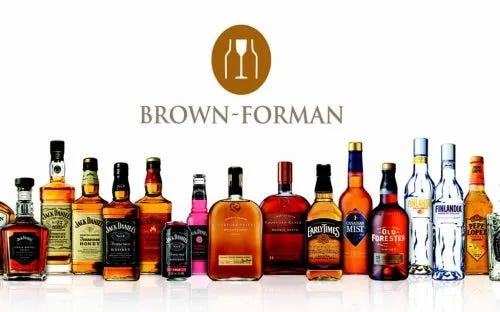
Shares climbed 3% after Q4 net sales rose 2%. SG&A spiked 34%, but the company still posted $54M in net income. Brown-Forman (maker of Jack Daniel's and Old Forester) officially rejected a $15 billion ($32 per share) buyout offer from rival spirits giant Sazerac.
ODDITY Collapses 30%
ODDITY’s share price dropped nearly 30% after Q1 net revenue declined 26%. Net loss of $21.4M compared to $37M+ in net income Q1 2025. CPA (cost per acquisition) spiked 83%. The beauty tech company that was supposed to disrupt traditional beauty hit a wall. When your customer acquisition cost nearly doubles, your growth model breaks down.
IM8 Board Addition: Comfrt Founde
r
IM8 added Hudson Leogrande, founder and CEO of billion-dollar apparel brand Comfrt, to its board. Comfrt expects to hit $1B in revenue this year — four years after launching. Adding a founder who built a billion-dollar brand in four years to the board of a brand that hit $100M in 11 months is a velocity-recognizes-velocity move.
🏪 DISTRIBUTION DOMINATION
Everyone’s everywhere
Target
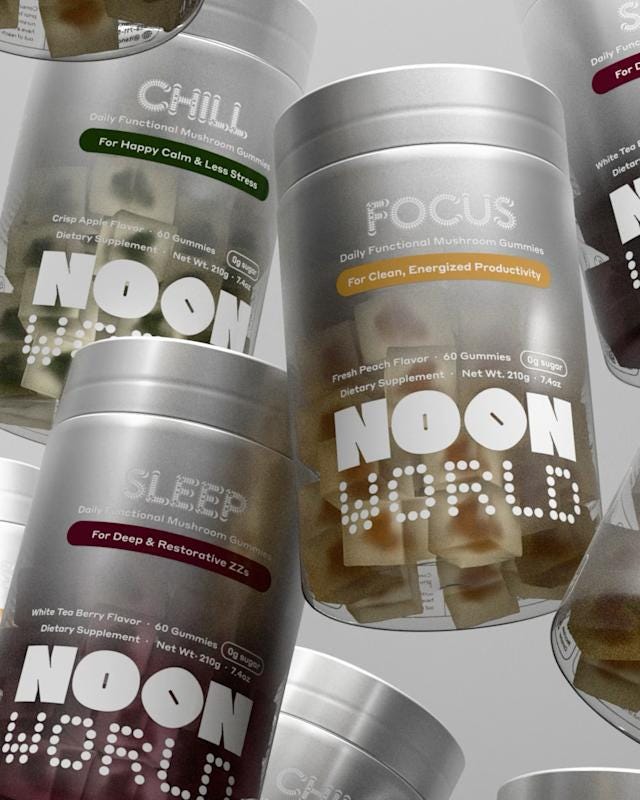
DryWater launched at 1,300 doors. Cure Hydration is rolling into 1,227 stores after 550% three-year growth. BERO Summer Shandy debuting June 14th. NOON WORLD launched online and in-store. Frosh kids juice boxes nationwide. Target keeps being the most important launchpad for emerging brands.
Costco
Neuro launched at 235 locations. O Positiv debuted at 235 locations. Elixir Shots launched in TX, LA, AR, and OK. Three brands are entering the club channel simultaneously. Costco’s willingness to take emerging functional brands signals category commitment.
H-E-B
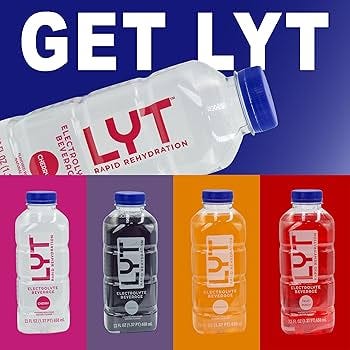
LYT launched. H-E-B continues adding functional beverage brands to its Texas footprint.
Whole Foods
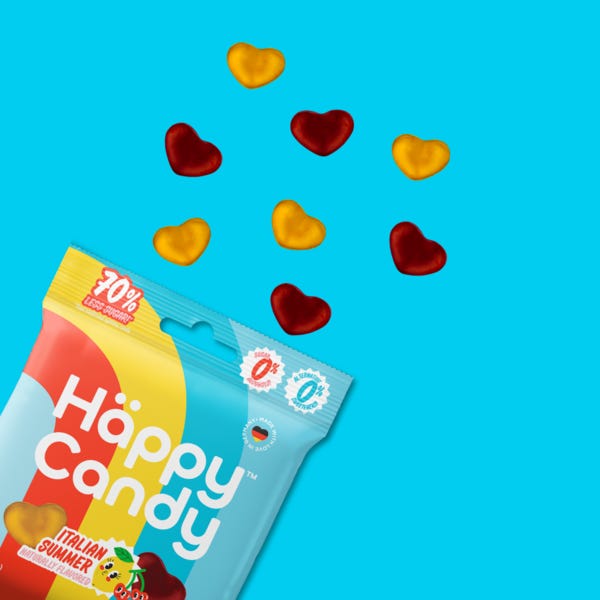
Häppy Candy launched at select stores. Clean candy entering the most curated natural grocer.
Wegmans
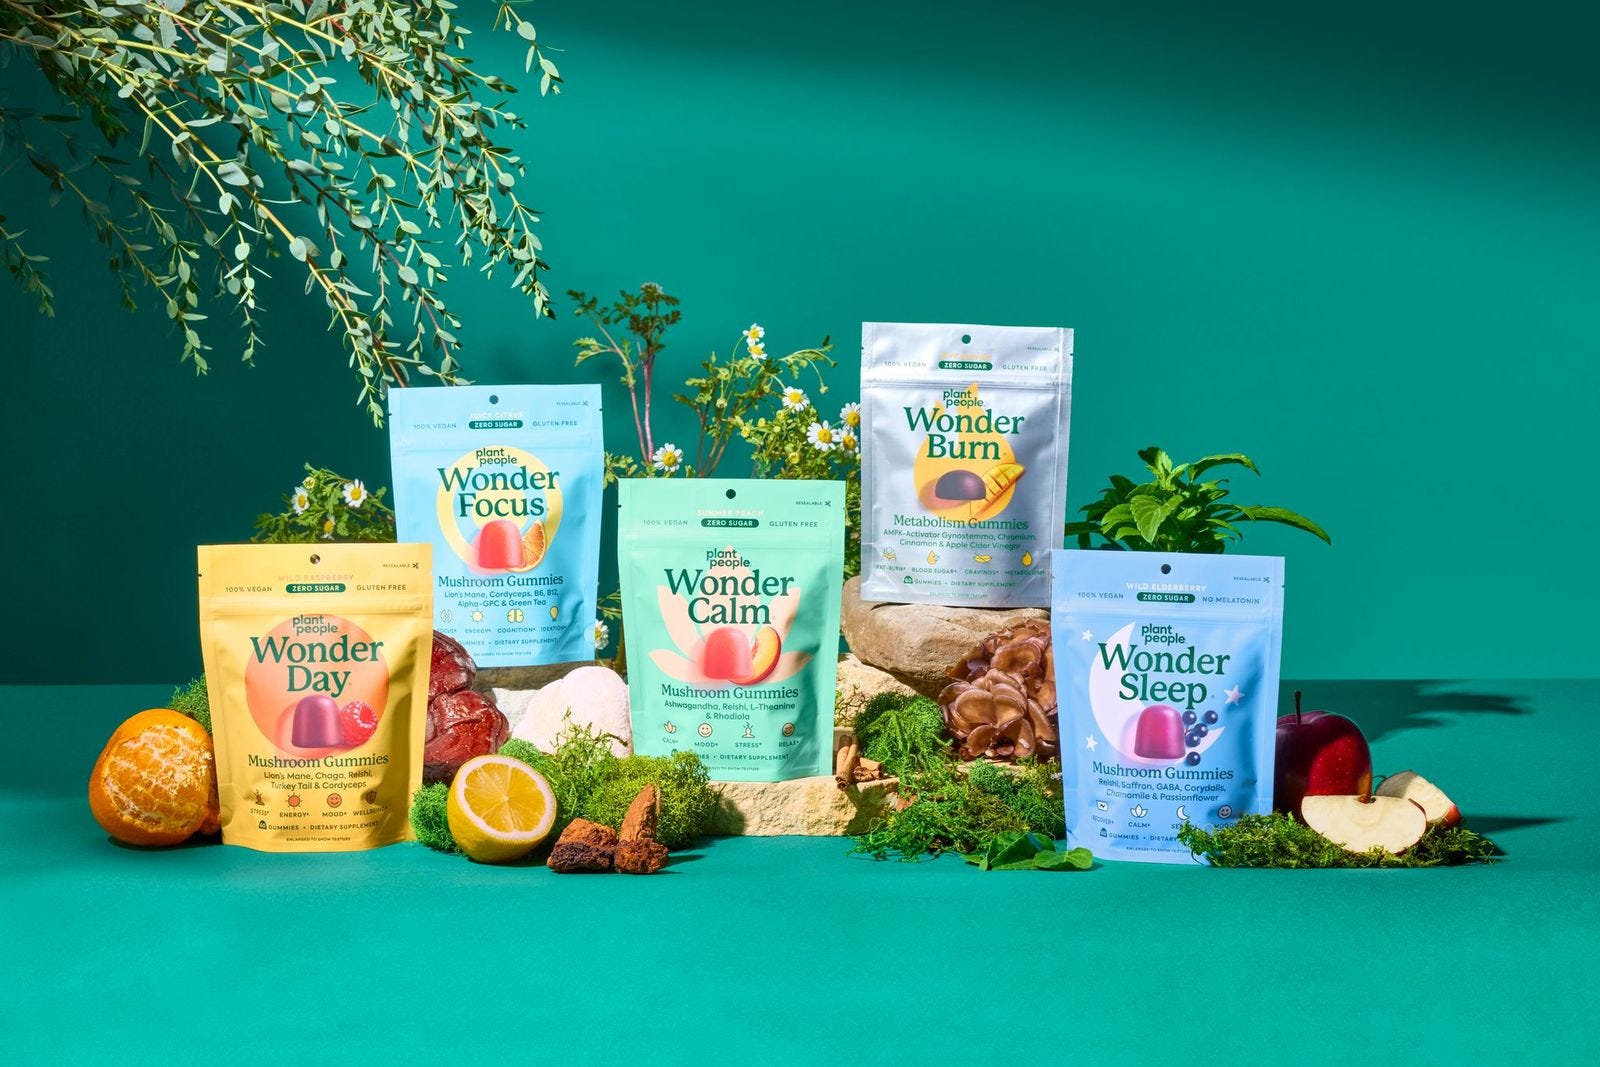
Plant People launched. The #1 mushroom supplement at Target expanding into Northeast premium grocery.
GNC
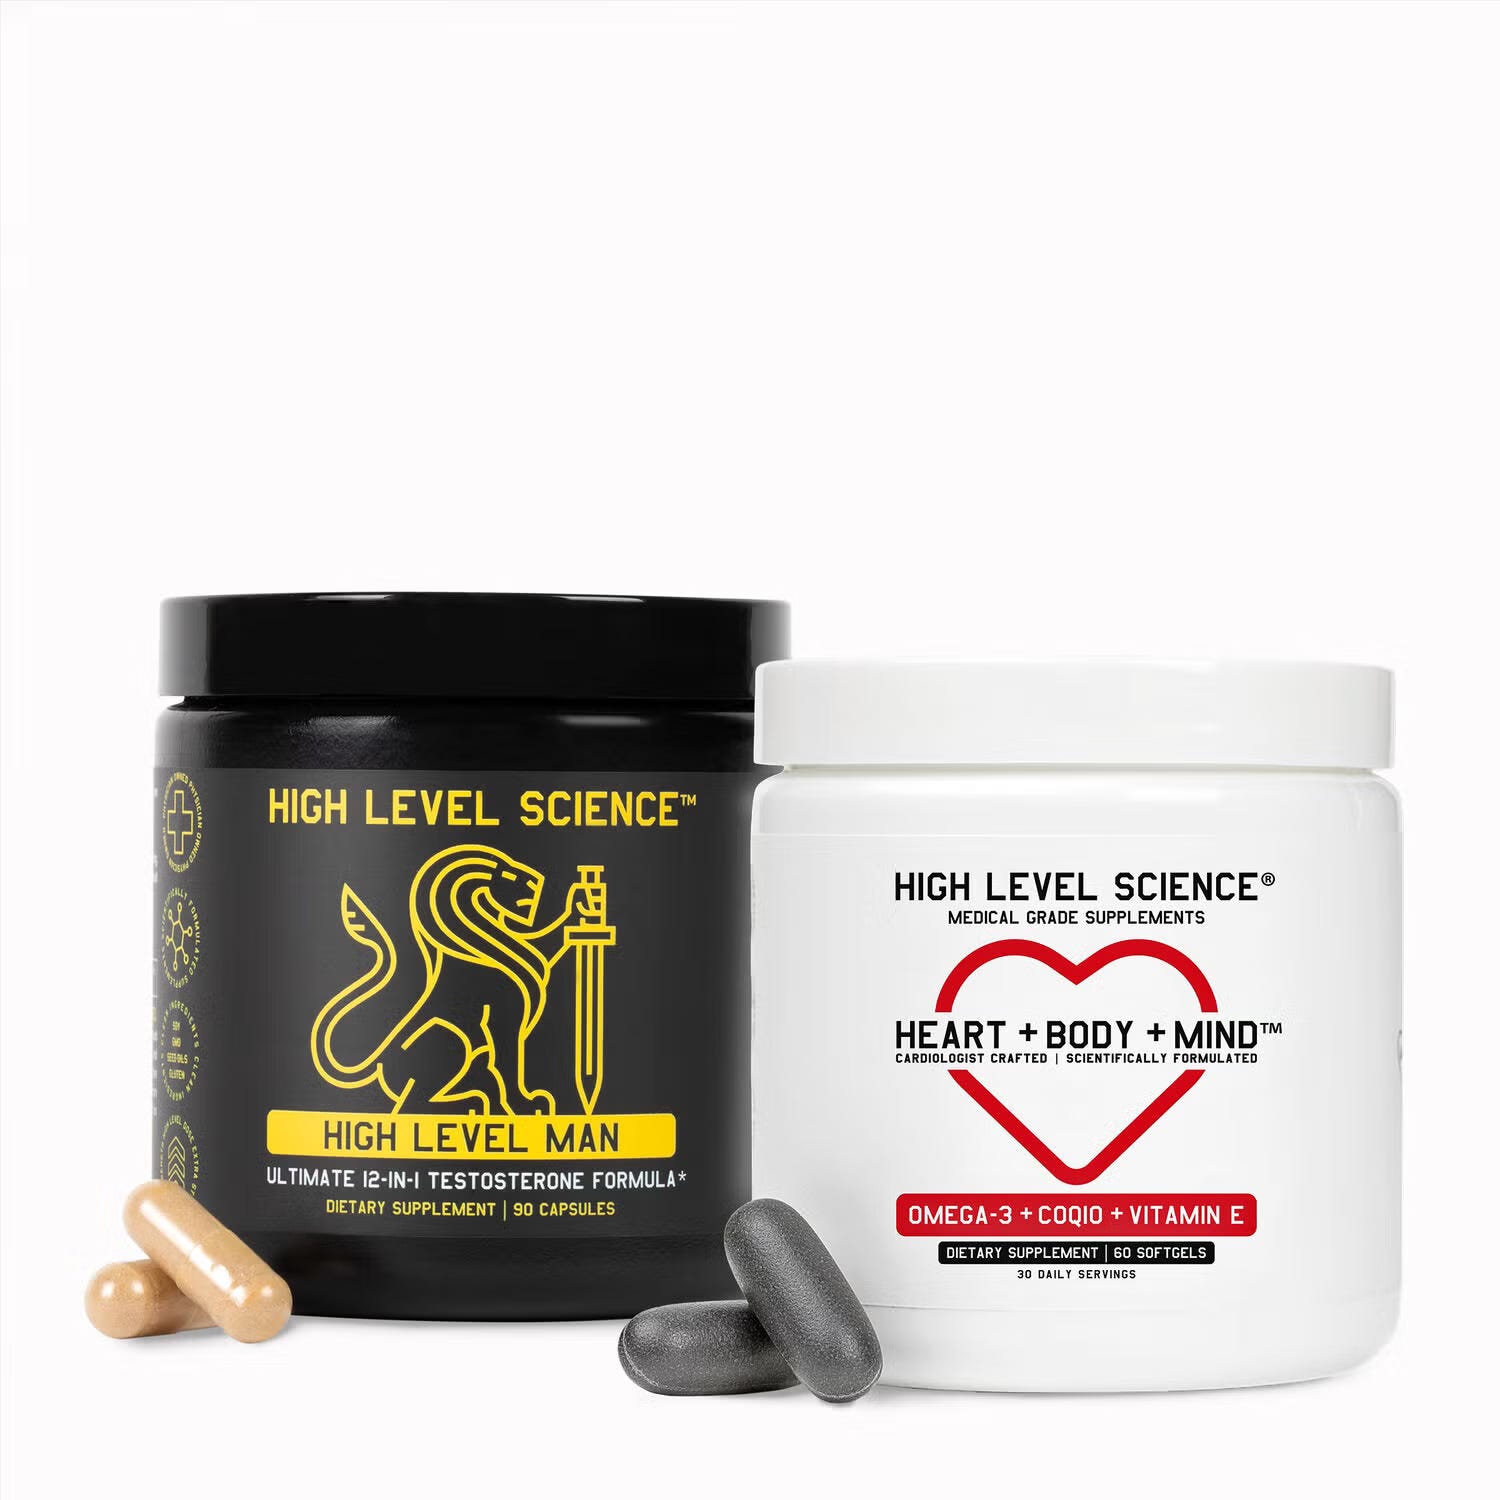
High Level Science launched at 1,000+ locations. Medical-grade supplements are entering the specialty supplement channel on a massive scale.
Casey’s
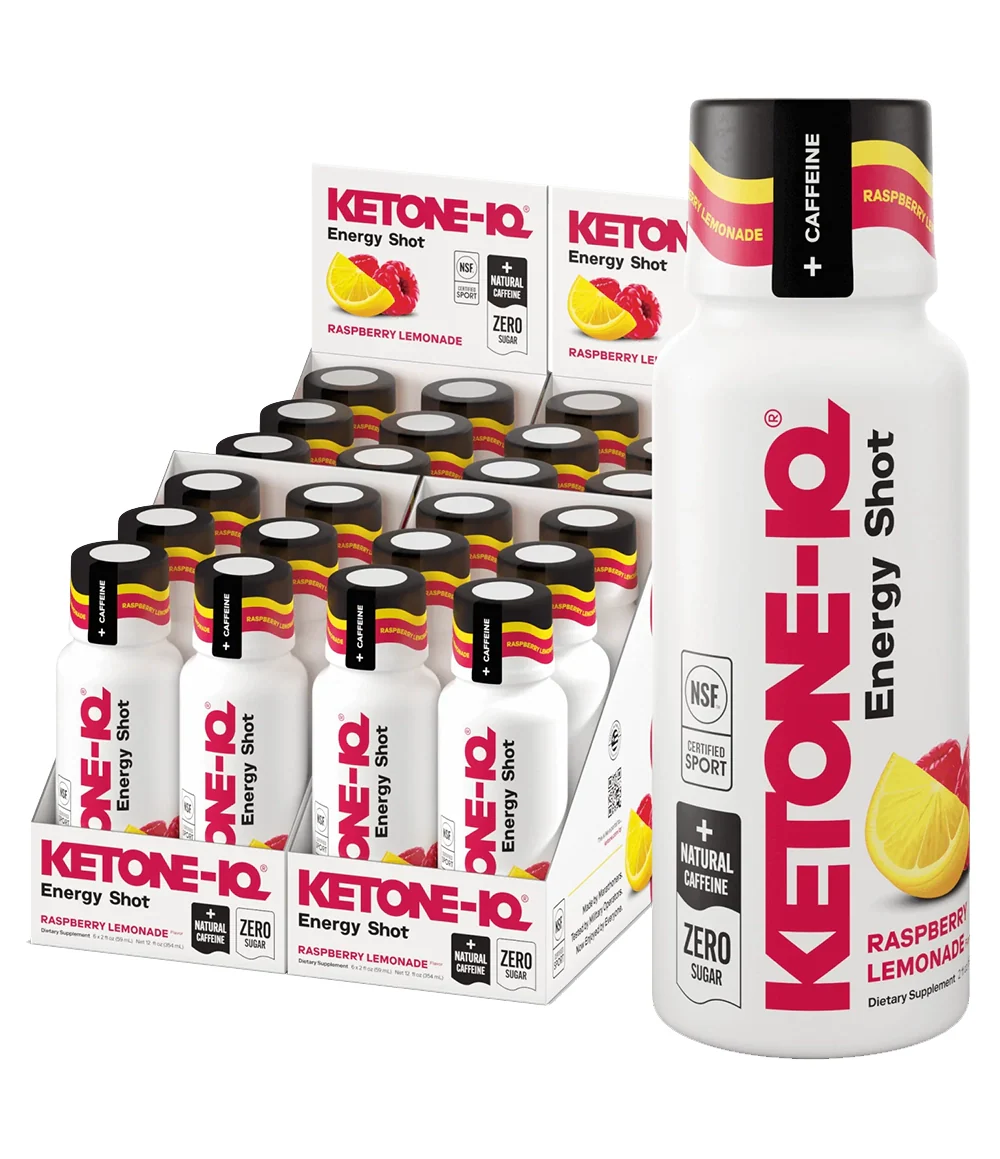
Ketone-IQ officially launched. The convenience channel continues to add functional beverages. Casey’s, with 2,500+ locations across the Midwest, gives Ketone-IQ access to a consumer base most premium functional brands miss.
Kroger and Albertsons
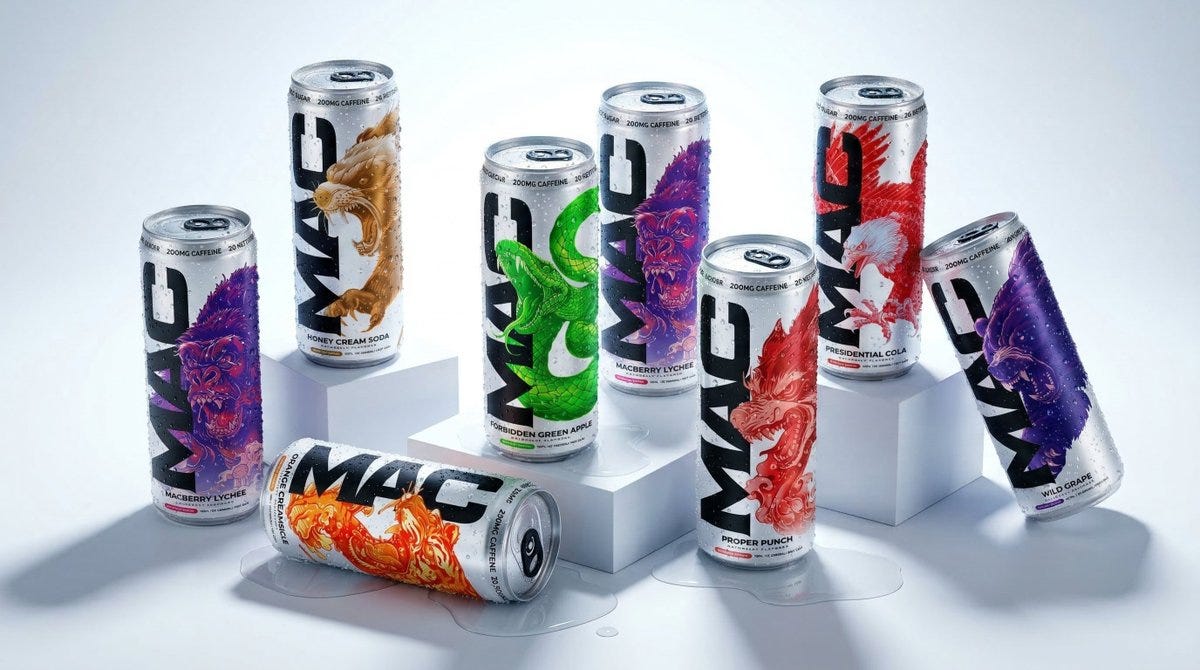
MAC Energy is securing cut-ins before the July 12th launch. Pre-launch retail commitments from two of the largest grocery chains in America for Conor McGregor’s energy drink.
Regional
Rotten at GIANT. Neutonic at Sainsbury’s (UK). Elavi confirmed nationwide at Whole Foods. Distribution continues to build for brands with proven velocity.
👋 PEOPLE MOVES
Hayden Hiatt, former Glossier exec, stepping from COO to CEO at California Naturals, replacing founder Shelby Wild. A Glossier-trained operator taking the reins of an L Catterton-backed personal care brand at the Series B stage. The brand is at Target, Ulta, CVS, H-E-B, and Sprouts. The scaling phase begins.
Hudson Leogrande, founder and CEO of Comfrt (expecting $1B revenue this year), joins IM8’s board. The brand that hit $100M in 11 months, adding a founder who built a billion-dollar brand in four years.
Sam McBride (ex-RXBAR COO) is running Kettle & Fire. Anish Agarwal (ex-Colgate CMO) is running Orebella. Jeff Rubenstein (ex-Poppi President) is running Khloud. The operator-upgrade cycle across CPG continues — proven executives with nine-figure and billion-dollar exits taking the helm at brands entering their scaling phase.
Suni Lee, a two-time Olympic gymnast, was named the first celebrity partner of PHLUR fragrance.
Karen Behnke, Juice Beauty founder, launched BeautyCrush Skincare — a serial founder back in the game with regenerative biotech.
🔥 THE HOT TAKE
My unfiltered opinion on this week’s madness
The strategics are in a feeding frenzy. And the brands with real velocity are getting fought over.
Look at this week alone: Nestlé is buying yfood for €450M. Bridgepoint is paying $460M for Obagi. Lactalis bought Protein Works. Applied Nutrition acquired Nutrablend assets. Trek One grabbed Good Karma and No Cow. Salt & Straw hired Piper Sandler for a $200M process. Church & Dwight paid $325M for Miss Mouth’s last week. Blackstone is still circling the Unilever ice cream spinoff.
That’s over $2 billion in announced or exploring deals in two weeks. Across ice cream, skincare, meal replacements, supplements, plant-based, and stain removers. Every category. Every price point. Every geography.
What’s driving it? The same thing that always drives M&A cycles: the math works. The brands that built real velocity over the past three years — during the correction, during the hype-to-reality reset — are now the most attractive acquisition targets in a decade. They’re cheaper than they would have been in 2021. They’re more proven than they were in 2023. And they’re growing faster than the acquirers’ organic businesses.
Ryl Tea grew 157% while iced tea declined 1.8%. That’s not growth. That’s category dominance. Purchase Capital backed OWYN to a $280M exit, and now they’re backing Ryl Tea at $20M because they see the same pattern. OLIPOP keeps posting 18% volume growth and just turned down Coca-Cola. Smash Kitchen is approaching $100M in year two. David sold out of protein ice cream in 28 minutes.
The velocity brands aren’t just growing. They’re proving that their growth is sustainable, repeatable, and acquired. Every quarter that passes with consistent double-digit growth raises the acquisition multiple.
Meanwhile, ODDITY collapsed 30% after CPA spiked 83%. The beauty tech company that was supposed to disrupt traditional beauty discovered that when customer acquisition becomes expensive, the model breaks down. CPA is the tax on growth for every DTC-first brand. The brands that survive it are the ones with strong enough repeat purchase to amortize the acquisition cost over years of retention. The brands that don’t survive it are the ones buying growth rather than earning it.
The strategics know the difference. That’s why they’re paying $325M for stain removers and $460M for dermatological skincare and €450M for meal replacements. Products with high repeat purchase, strong margins, and real distribution. Not virality. Not a celebrity. Not customer acquisition hacks. Repeat purchase.
The feeding frenzy is here. And it’s rewarding the brands that built something real during the years nobody was watching.
🎙️ COMING TUESDAY
Unpackaged Goods Episode
Breaking down the M&A feeding frenzy — over $2B in deals across two weeks. Salt & Straw is exploring $200M while Blackstone circles the ice cream category. Nestlé’s first acquisition under the new CEO. Bridgepoint is building a $1.8B dermatological skincare portfolio. Lactalis is buying Protein Works as the third European dairy giant enters functional nutrition. Ryl Tea is growing by 157%, while iced tea is declining. David is selling out of protein ice cream in 28 minutes. And ODDITY collapsing 30% when CPA spiked 83% — the warning for every DTC brand.
🥫 ONE MORE THING...
Before you close this tab
Nestlé is buying yfood. Lactalis bought Protein Works. Danone already bought Huel. The three largest dairy companies in Europe are all acquiring functional nutrition brands in the same year.
Traditional dairy consumption is flat. Functional nutrition is growing. The dairy giants have manufacturing, supply chain, and distribution. What they don’t have is the brand and the consumer relationship. So they’re buying both.
If you’re building a functional nutrition brand with real velocity and strong repeat purchase, every dairy company in Europe is a potential acquirer. Danone already wrote a $1.15B check. Nestlé just wrote a €450M check. Lactalis wrote an undisclosed check. There are more checks coming.
The buyer pool for functional nutrition brands has never been deeper. Build accordingly.
Until next Sunday, Jonathan Deeter Your CPG-Obsessed Friend
P.S. — David sold protein ice cream for $90 per six-pack and sold out in 28 minutes. Ninety dollars. For ice cream. In 28 minutes. Peter Rahal could probably sell protein air fresheners in David packaging and move 10,000 units before lunch. The brand premium is that strong. The real question is whether $15-per-pint ice cream works at retail scale or only as a DTC drop model. I’m genuinely curious to see if Whole Foods puts $15 David pints next to $7 Jeni’s and $5 Häagen-Dazs. That shelf will tell you everything about how far brand premium can stretch.
TikTok | Instagram | Newsletter | Pickle Advisors | YouTube
This newsletter is finished with Trophy Wife Finishing Salts - elevating every bite since 2025