

Issue #4 | November 23, 2025
Proudly seasoned by Trophy Wife - The Official Finishing Salt of The Deeter Digest. Because you are the prize, and so is this salt.
🥄 FIRST BITE
The appetizer before we dive in
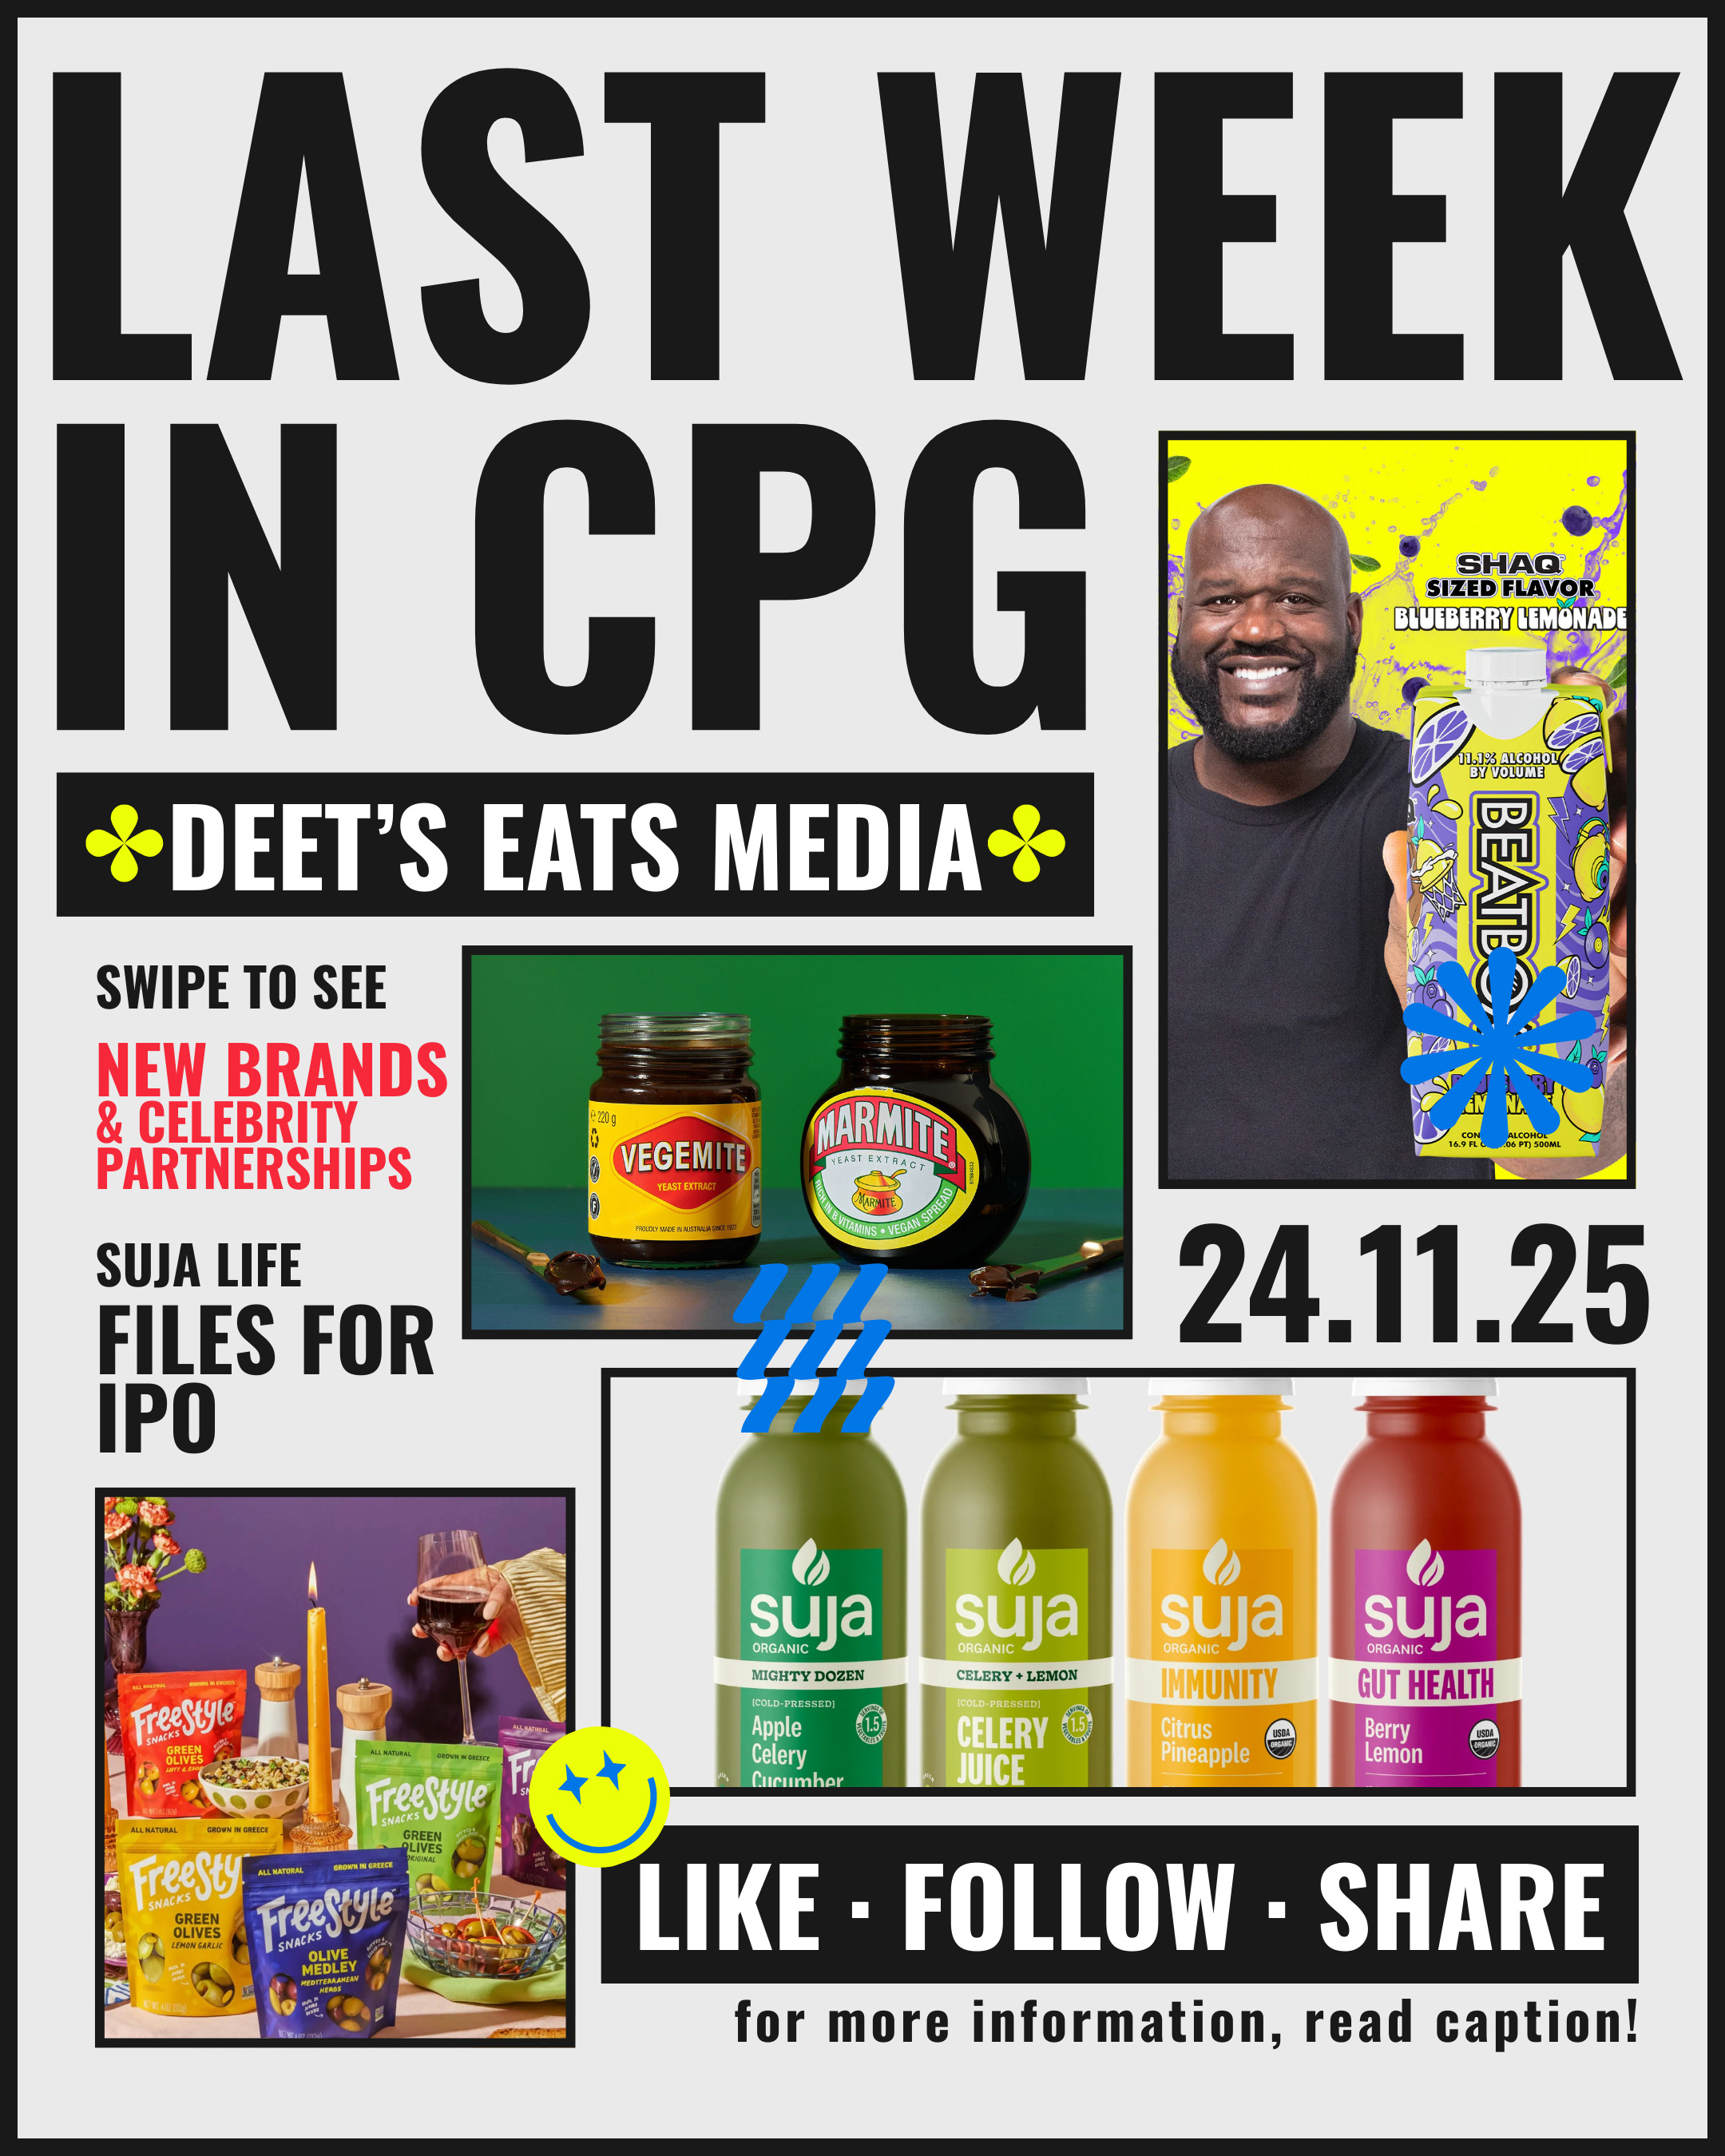
Welcome to The Deeter Digest. This week, Anheuser-Busch dropped $700 million on party punches, Suja Life filed for IPO, and seemingly every fund in CPG raised new capital.
The exits are back. The funds are loaded. Let’s feast.
🍊 THE MAIN COURSE
This week’s biggest CPG move
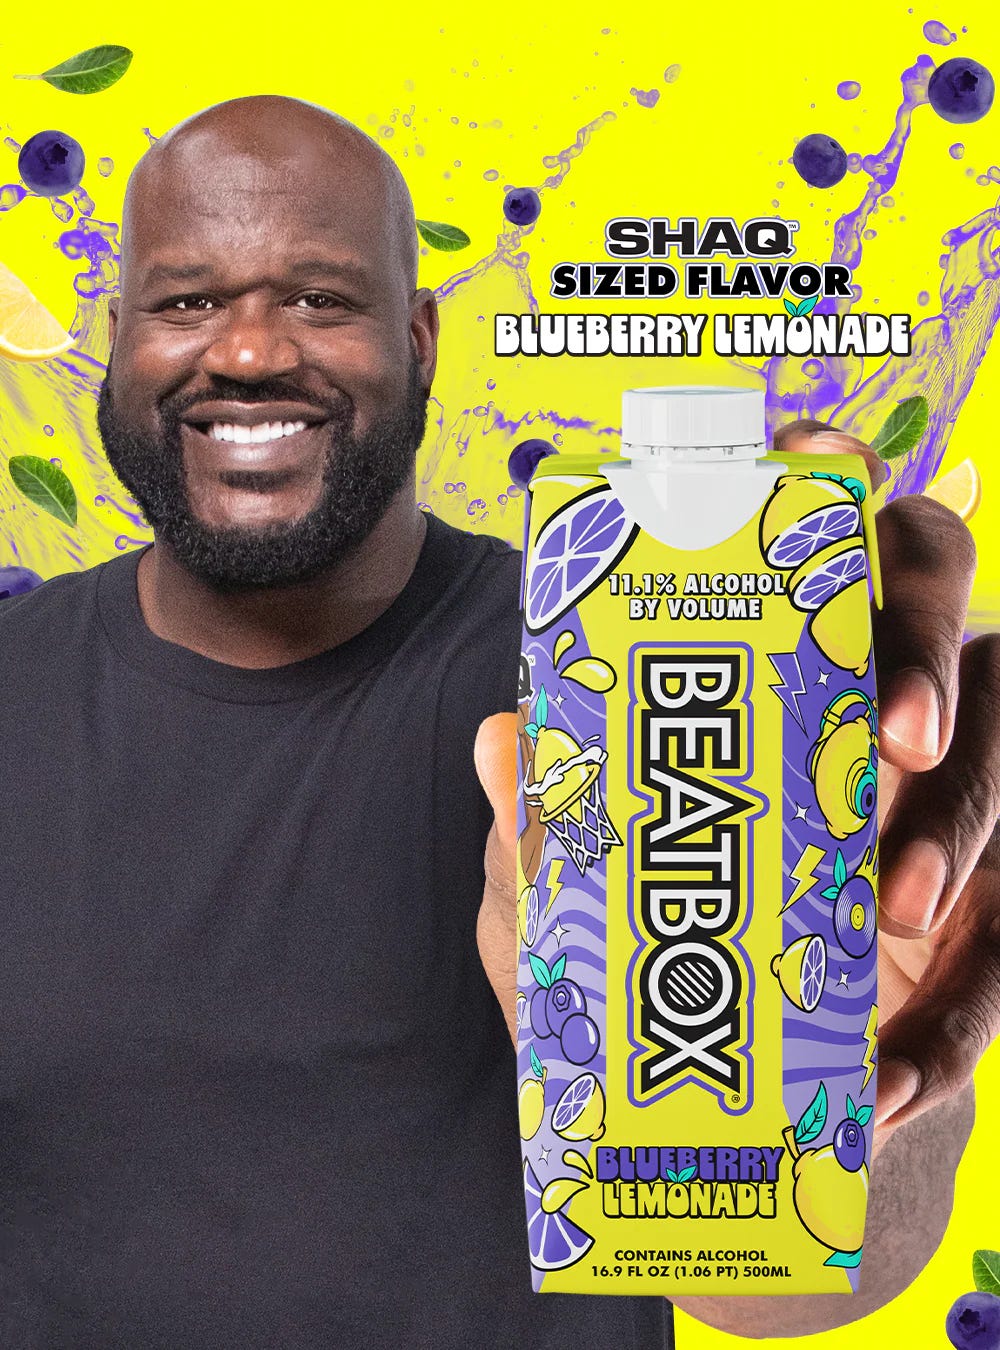
BeatBox Scores $700M Exit to Anheuser-Busch
The RTD cocktail brand known for bright Tetra-Pak packaging and high-ABV party punches is selling to AB InBev for approximately $700 million. Founded in 2011 by Justin Fenchel, Aimy Steadman, and Brad Schultz, BeatBox was on pace for $175 million in 2024 revenue and expects $250 million in 2025.
At roughly 2.8x forward revenue, the valuation is surprisingly rational by recent standards. For AB InBev, BeatBox joins Cutwater Spirits and Nütrl in their growing RTD cocktail portfolio. The acquisition signals Big Alcohol’s continued pivot from declining beer sales to higher-margin, occasion-based beverages. With scaled players like Surfside, Sprinter, and The Finnish Long Drink still independent, expect more RTD consolidation soon.
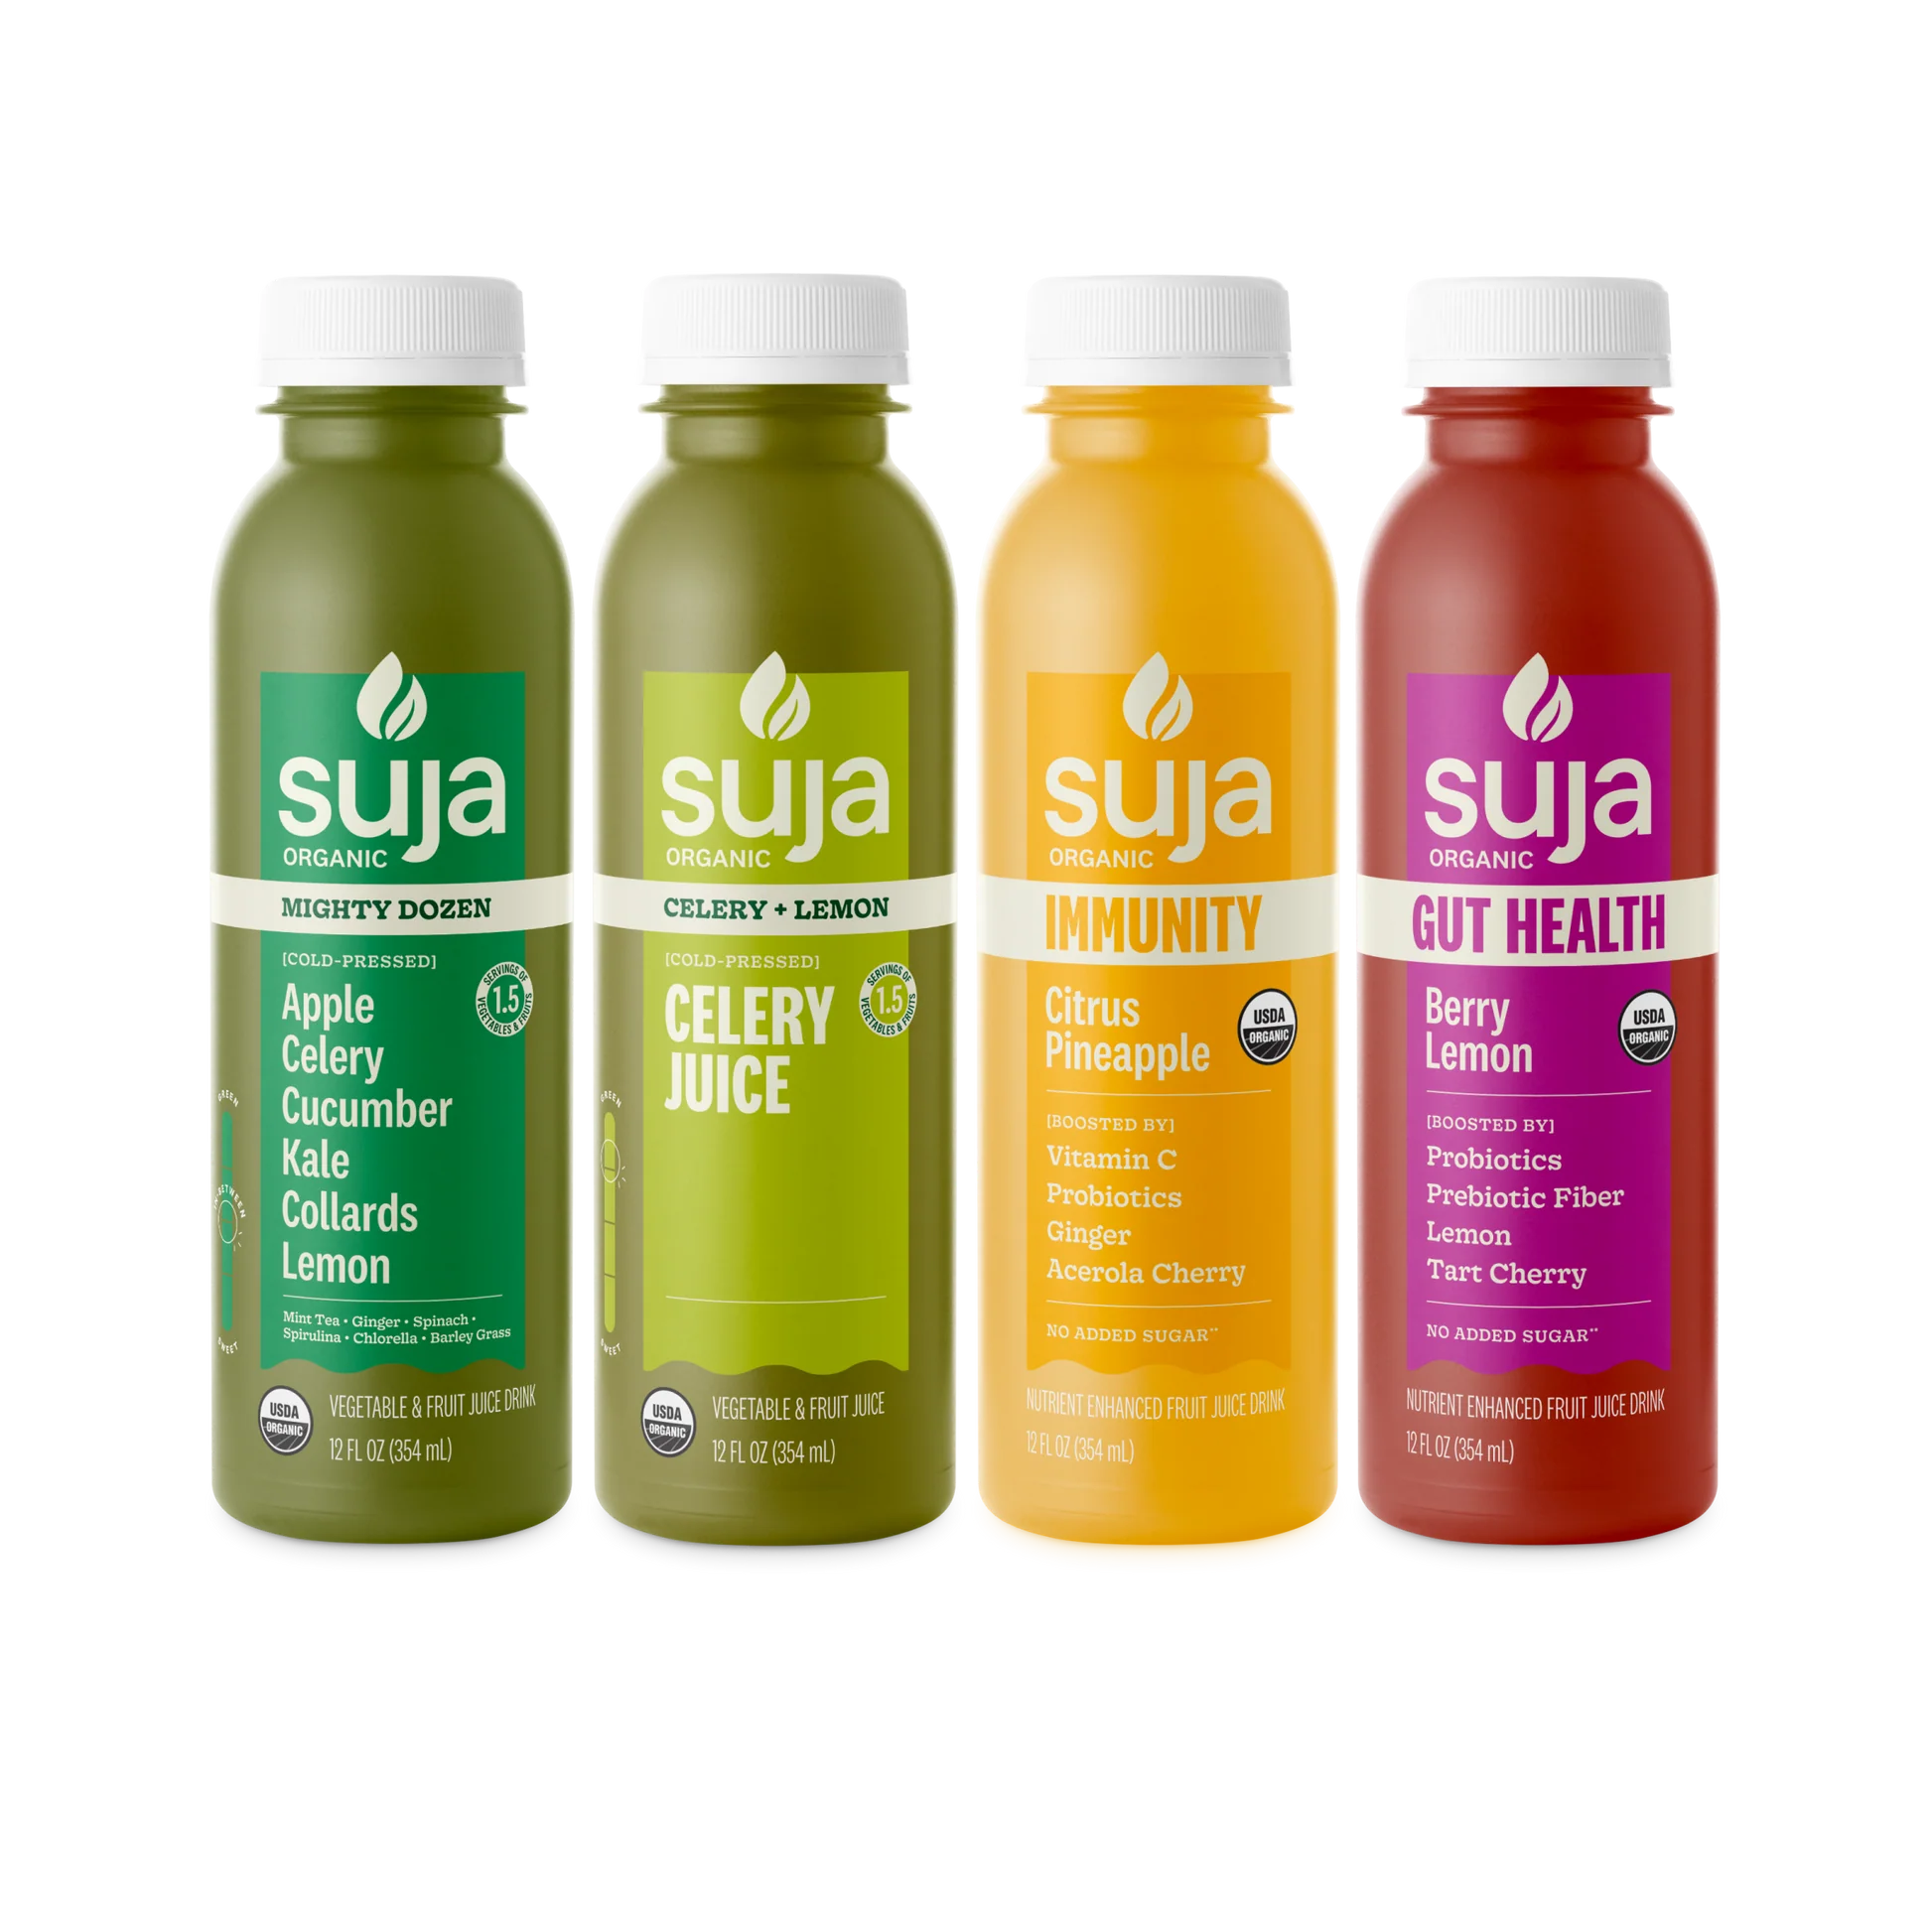
Suja Life Files for IPO
Paine Schwartz-backed Suja Life confidentially filed IPO paperwork with the SEC, testing whether public markets are ready for another juice story. The company owns Suja Organic, Vive Organic (acquired 2022), and recently rebooted Slice Soda. Paine Schwartz acquired Suja in 2021 when revenue approached $200 million.
The IPO filing represents a bold bet that Wall Street will see Suja as more than just cold-pressed juice. With functional shots via Vive and nostalgic soda through Slice, they’re positioning as a beverage platform. But public markets have been brutal to single-category beverage brands. Suja needs to prove their portfolio approach drives better margins than juice alone. The roadshow pitch better be compelling.
The Great Fund Raising Spree of 2025
Everyone with a track record just raised a fund. Monogram Capital closed $350 million for Fund III, bringing AUM to $1.75 billion. Prelude Growth raised a massive $600 million for Fund III after exits including PHLUR (to TSG) and 8Greens. Lerer Hippeau secured $200 million, while Aria Growth ($152M), ACG ($160M), and Sugar Capital ($75M) all closed new vehicles.
The fund frenzy reflects CPG’s return to rationality. LPs saw enough exits in 2024-2025 to believe again. Fund sizes are growing but not ridiculous – Prelude’s $600 million is substantial but appropriate for later-stage growth. New entrants like Taste Tomorrow Ventures ($30M) and the upcoming Paperboy Ventures show the ecosystem expanding. With Bachan’s hiring bankers (another Prelude portfolio company), the exit momentum should continue.
💰 THE FUNDING FRENZY
Big checks being written
Growth & Late Stage
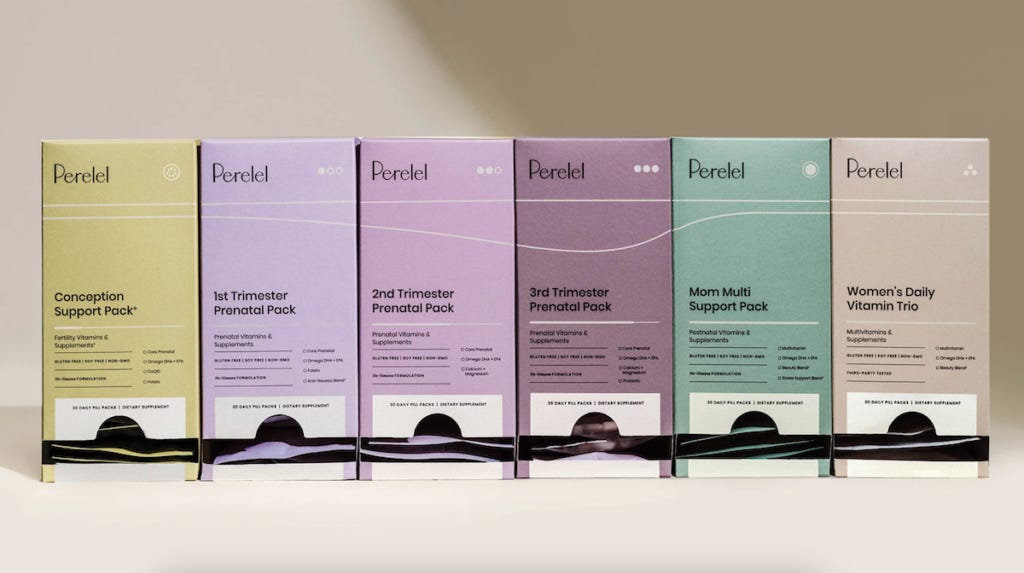
Perelel raised $27 million in growth funding led by Prelude Growth Partners, with participation from Unilever Ventures, Willow Growth Partners, and Selva Ventures. The doctor-founded women’s supplement brand is evolving from prenatal vitamins into comprehensive women’s health.
Aplós secured $5 million for their functional non-alcoholic spirits from undisclosed investors. The brand added 2,000 doors this year and landed on menus at Atelier Crenn and Soho House. Every spirits giant now needs a zero-proof play.
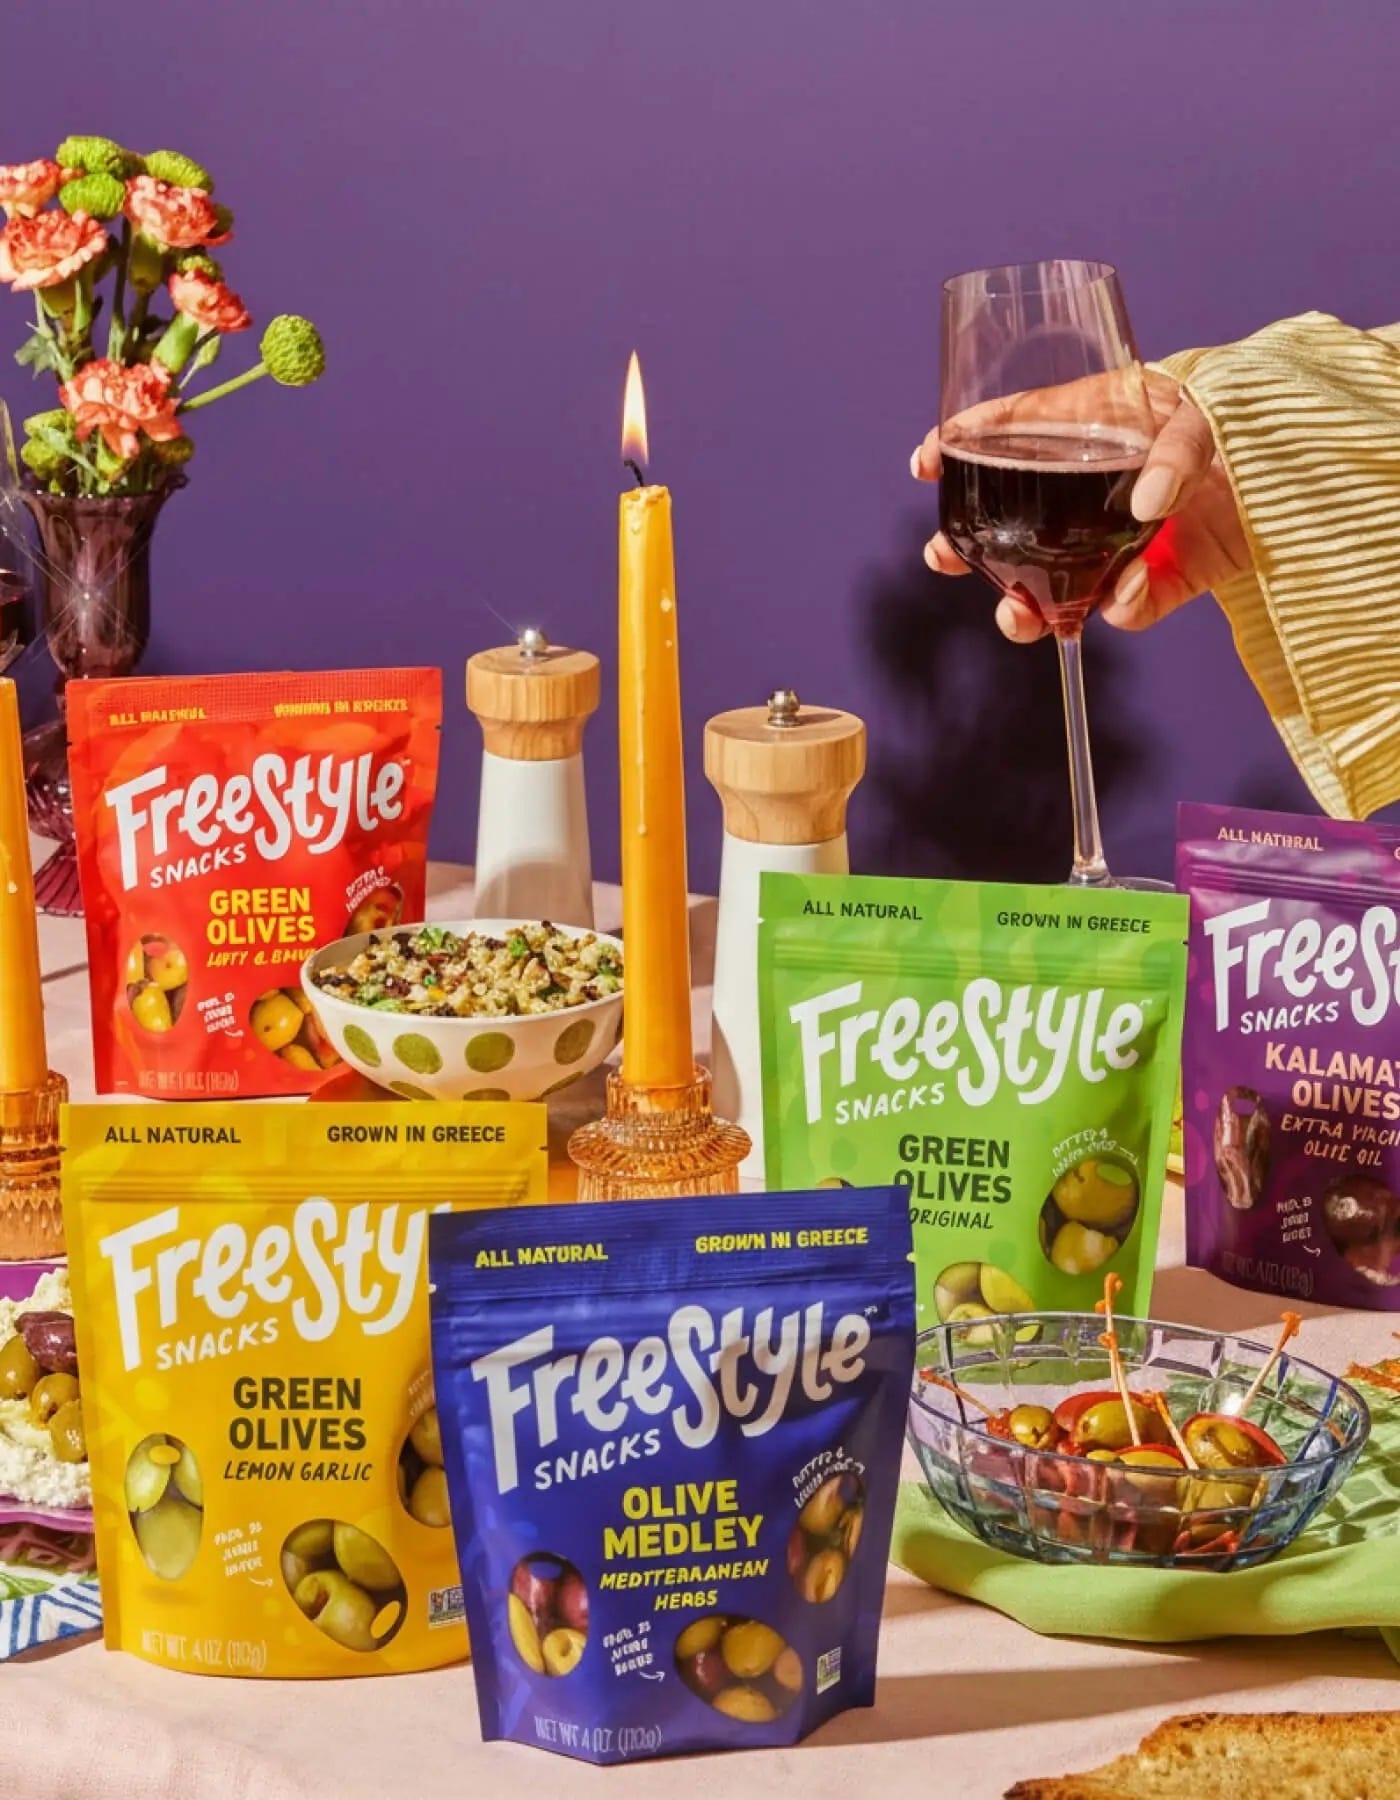
Freestyle Snacks won $300K from Poppi co-founder Allison Ellsworth on Shark Tank. The portable pickle and olive snack brand expects $4-5 million in FY sales. Sometimes the best funding comes with prime-time exposure.
The Exit Pipeline Building
Prosperity Organic Foods acquired Miyoko’s Creamery for undisclosed terms, giving the plant-based cheese brand a new home after founder drama. AG Barr bought out Strykk non-alc spirits after holding 20% since 2019. Small exits, but exits nonetheless.
🏪 DISTRIBUTION DOMINATION
Everyone’s everywhere
The Energy Drink Land Grab
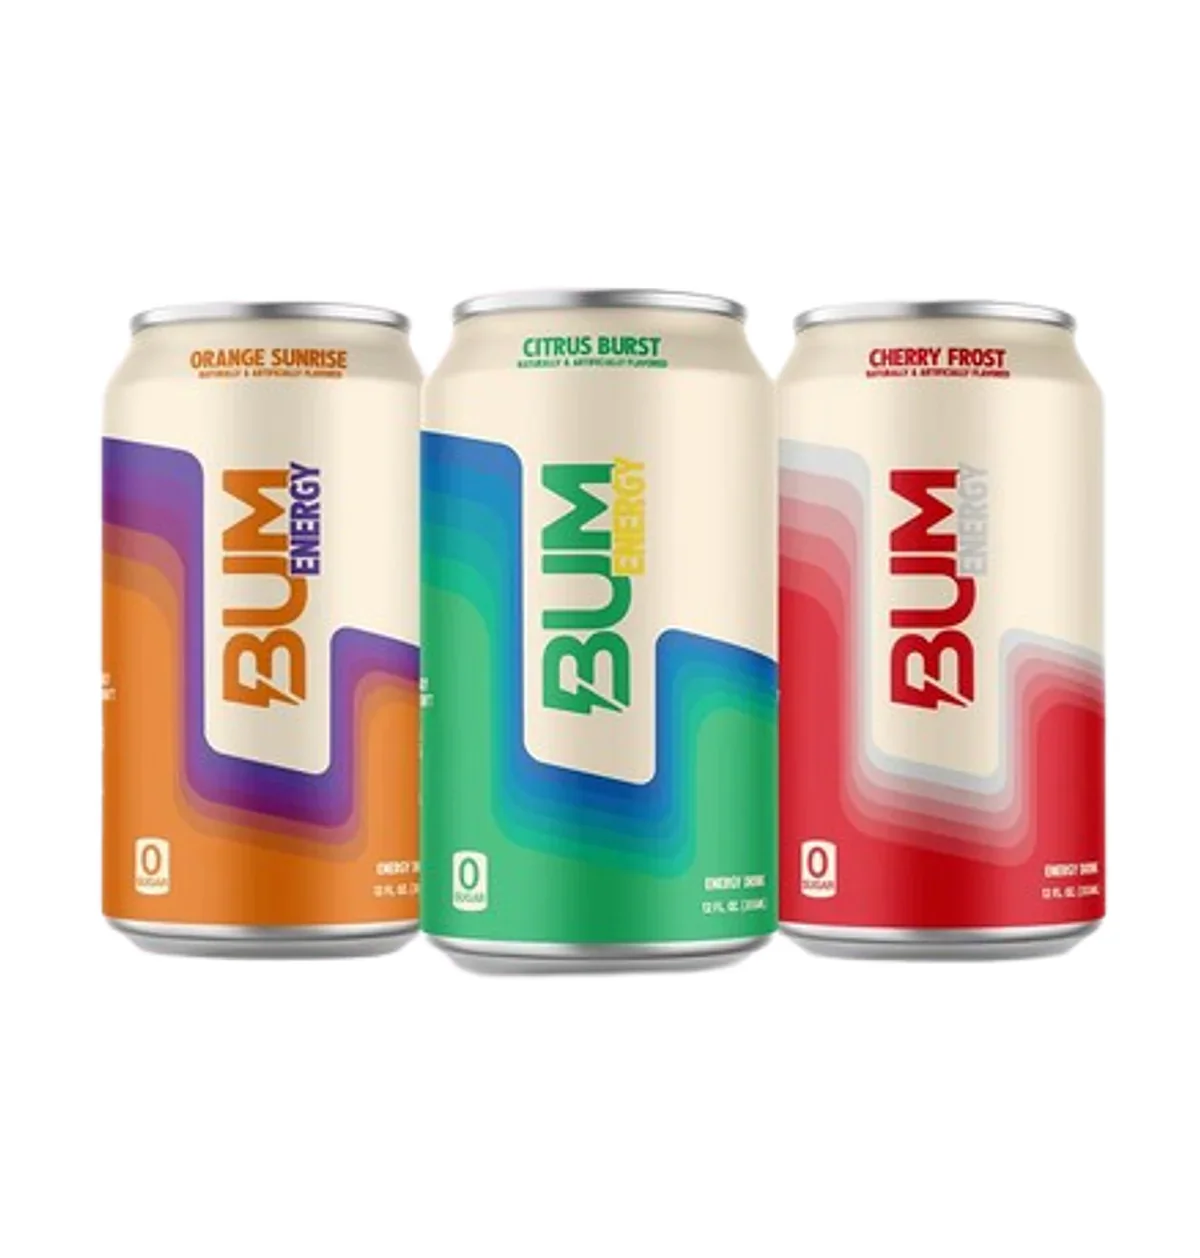
BUM Energy is having a moment. After 800% year-over-year growth, they’re loading up with talent from Congo Brands, RYSE Fuel, and Liquid Death. With Target, Walmart, Sam’s Club, and Costco launches incoming for 2026, BUM is positioned to challenge the energy establishment. RAW Nutrition’s 2023 launch is paying off.
Bloom rolled out their energy line at Buc-ee’s, because apparently gas station glory is the new Whole Foods. Joyburst is pacing toward $100 million in sales, proving there’s room for more players in caffeinated chaos.
Mainstream Retail Embraces Everything
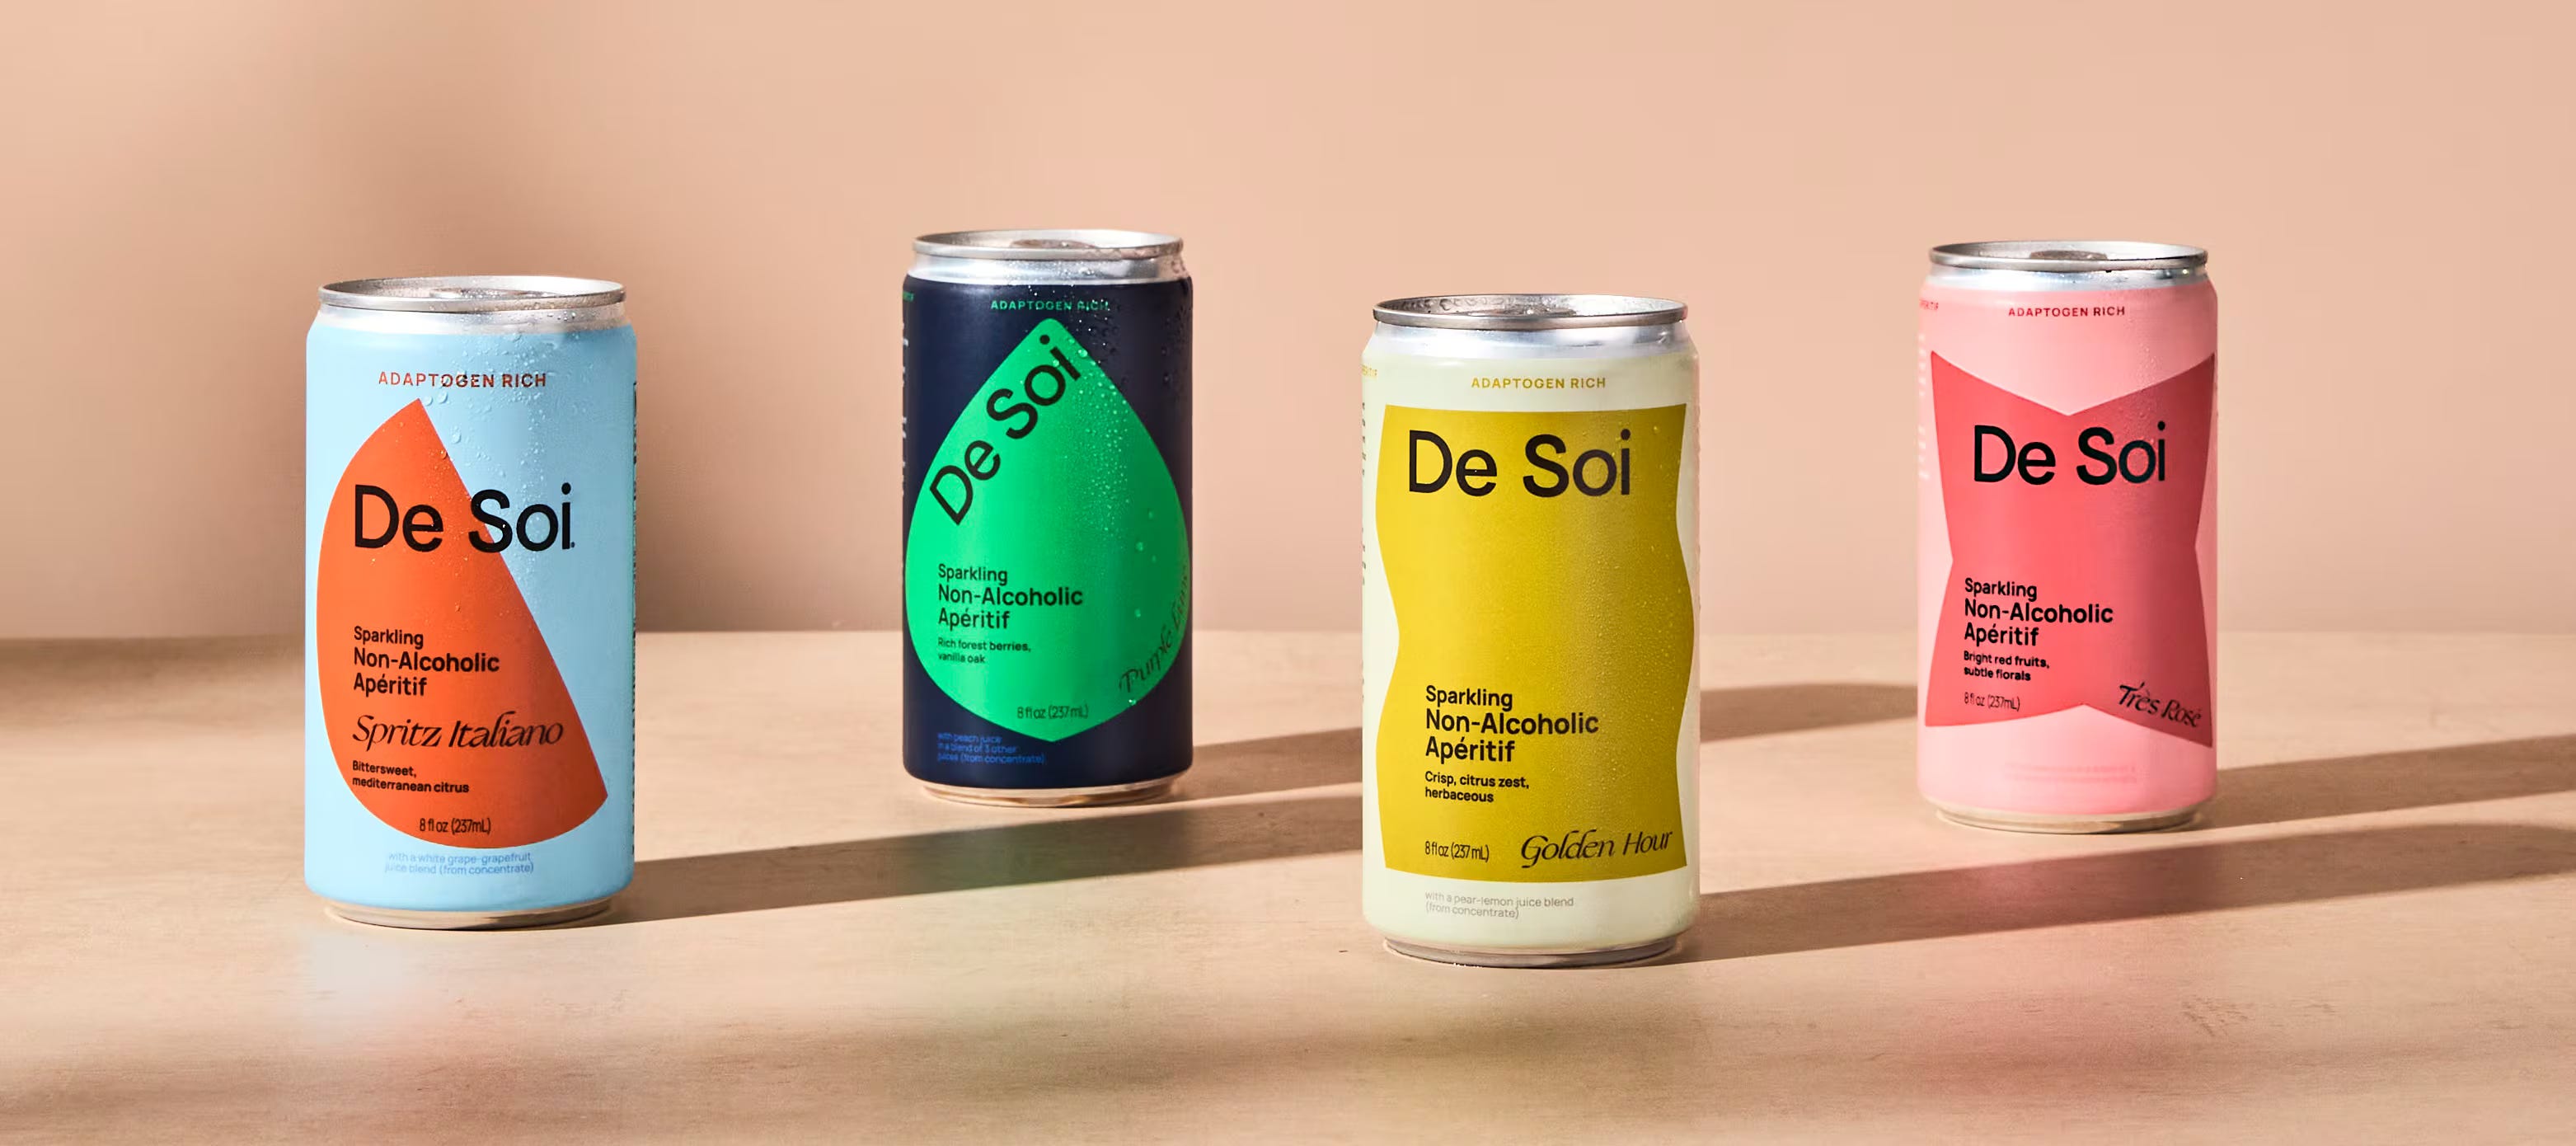
This week’s distribution wins paint a picture of radical retail acceptance. Wavers hit Safeway. De Soi went nationwide at Kroger. Cann launched at Circle K. Doughlicious added 1,100 Kroger stores. When THC beverages land at gas stations and frozen cookie dough gets thousand-store rollouts, we’ve entered a new era of retail permissiveness.
Regional Retailers Lead on Innovation
Alice Mushrooms at Raley’s. Willie’s Remedy+ expanding in Austin. Realsy at Heinen’s. Marlow at Shoppers Drug Mart in Canada. Regional retailers continue punching above their weight, giving emerging brands crucial proof points before national expansion.
🎾 CELEBRITY & COLLABS
This week’s famous faces and partnerships
Strategic Partnerships
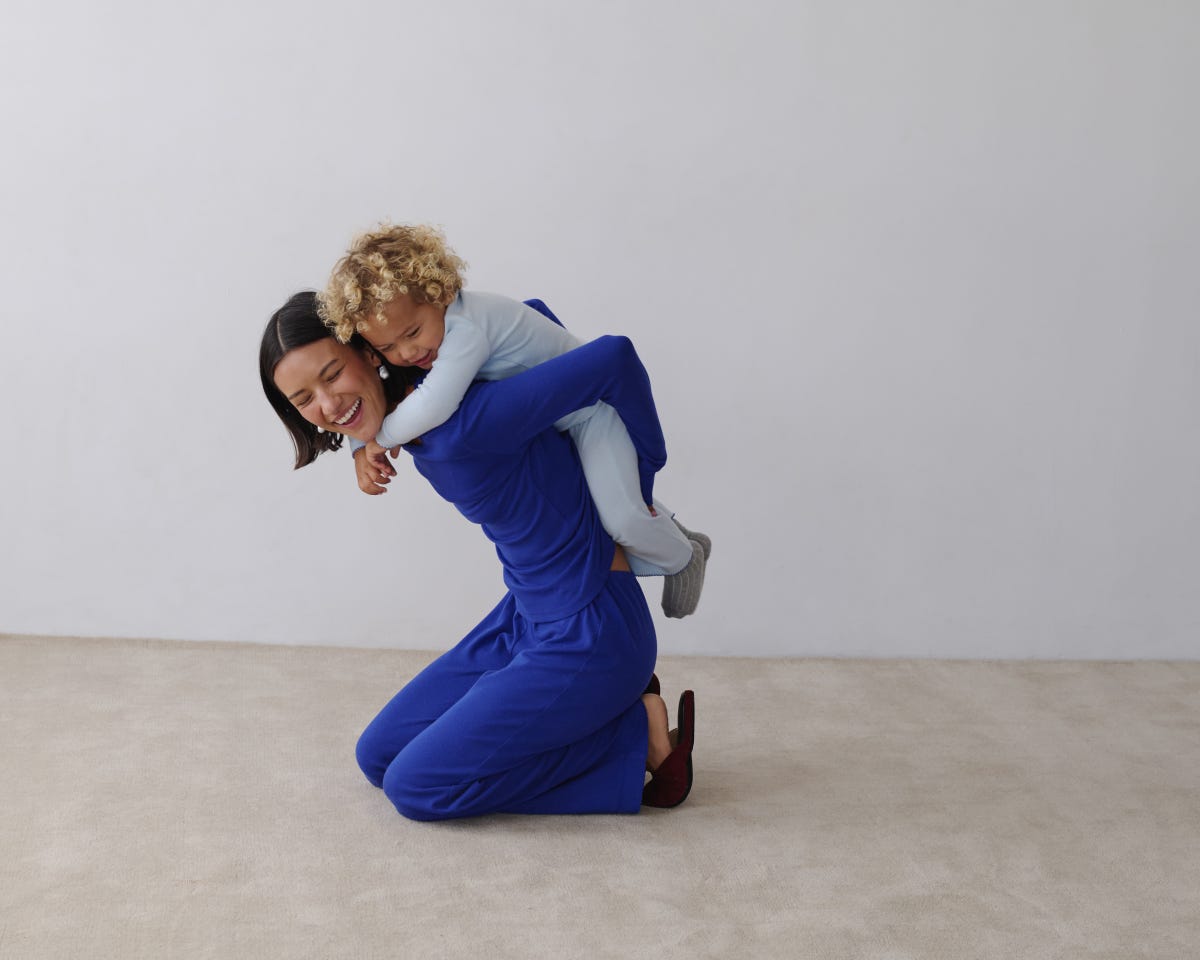
Coterie x DONNI dropped an apparel collection for moms, babies, and toddlers. Smart cross-category play between diapers and fashion. Lucky Energy x Brittany Cartwright launched “Rawt in Hail” strawberry lemonade, bringing Bravo energy to energy drinks.
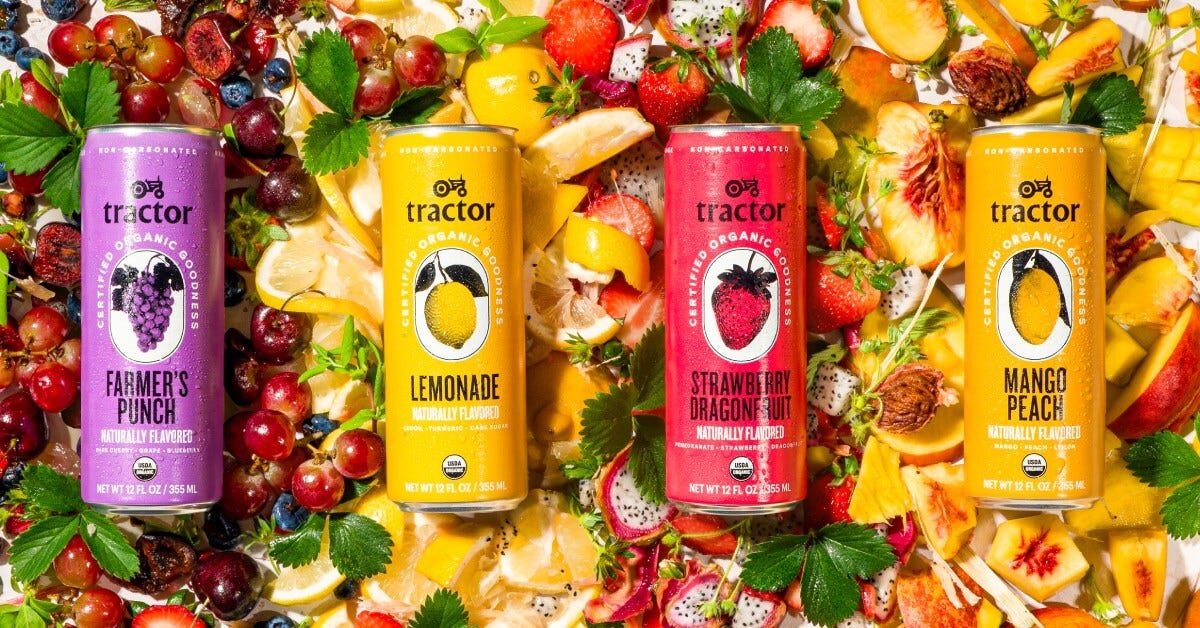
Tractor Beverage is taking their foodservice success (10,000 locations) to retail with Haymaker, an ACV-based sparkling tonic launching at Sprouts in January. The foodservice-to-retail playbook rarely works, but Tractor has the scale to try.
Product Innovation
California Naturals expanded beyond haircare with Hydrating Lip Balms. Rotten candy dropped Spicy Sour Gummy Cruncheez exclusively at Sprouts. Cleveland Kitchen unveiled new packaging. Suja launched multivitamin shots in three variants. Everyone’s extending lines, seeking growth through SKU proliferation.
🏭 INFRASTRUCTURE & INNOVATION
Building real businesses
BUILT Builds Manufacturing Muscle
The protein bar brand opened its second Utah facility – 132,000 square feet supporting 500 new jobs. Combined with their American Fork facility, BUILT now has serious manufacturing capacity in Utah, which is quietly becoming the protein bar capital of America. While others outsource, BUILT’s betting vertical integration drives margins and quality.
Tech Meets Traditional CPG
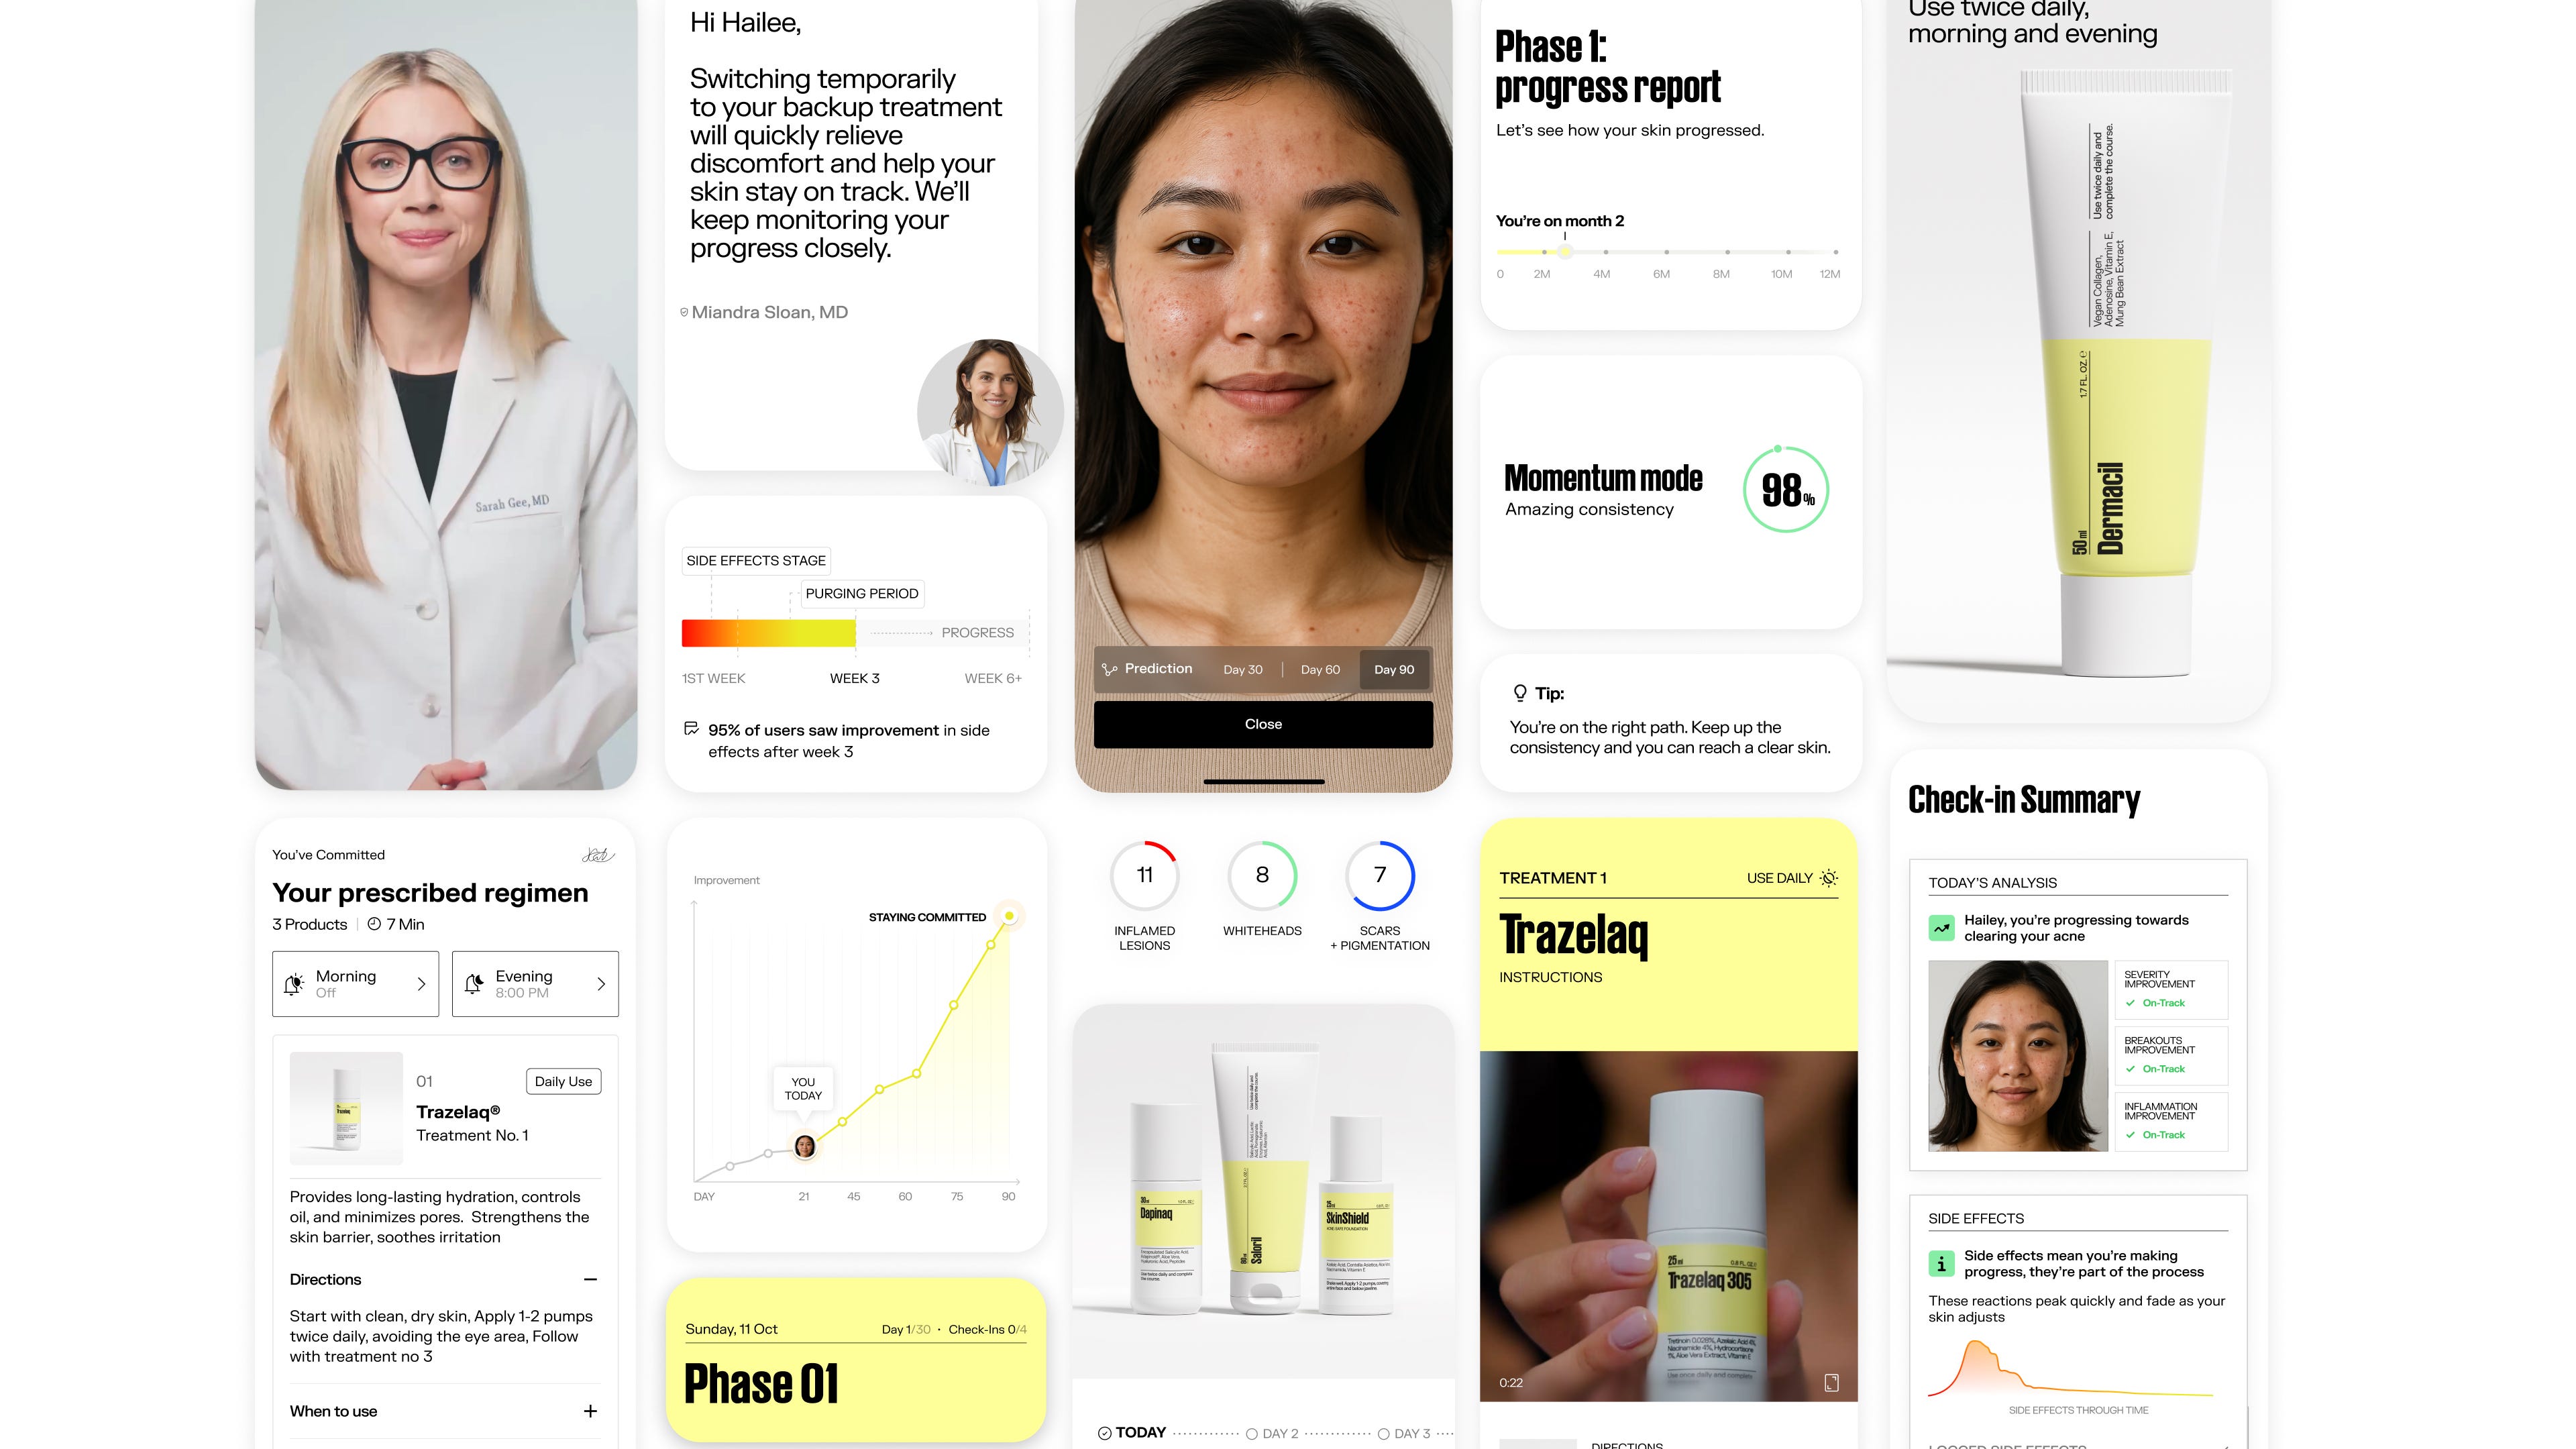
Oddity (NASDAQ: ODD) launched Methodiq, a telehealth dermatology platform targeting 50 million Americans with acne and 30 million with eczema. The $2.1 billion market cap company proves tech-first beauty brands can expand into medical-grade treatments.
YETI paid $38 million for Helimix and its hexagonal shaker bottle technology. YETI’s first acquisition shows they’re serious about drinkware beyond tumblers. At roughly 10x revenue, they’re betting premium shaker bottles follow the same $45 tumbler logic.
Big CPG Moves
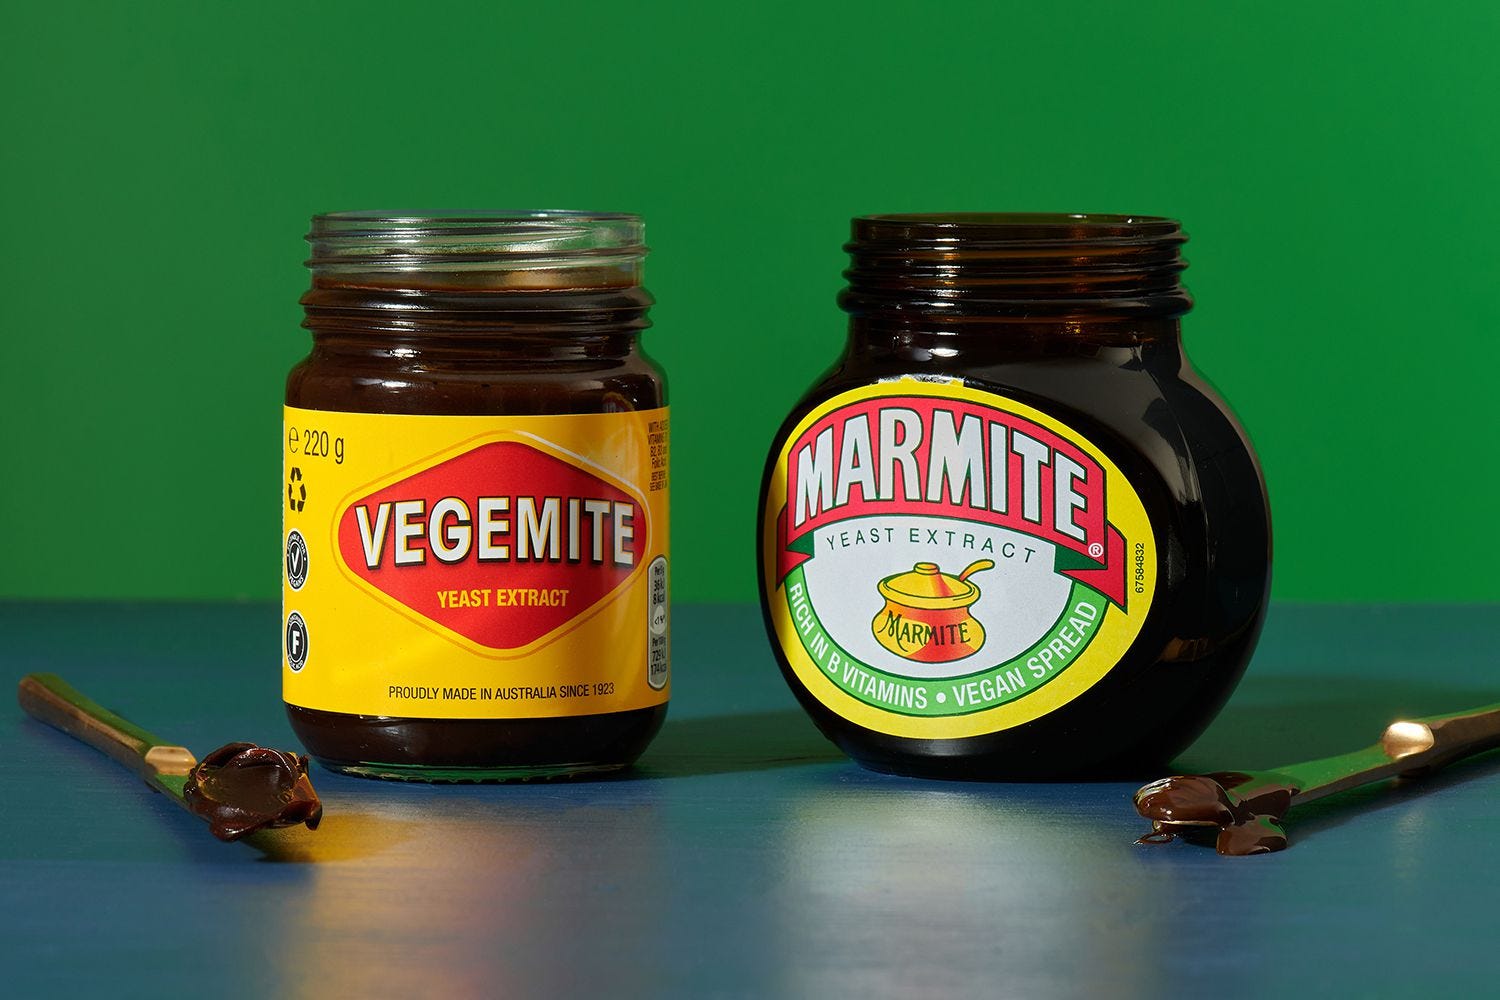
Unilever is selling British icons Marmite, Colman’s, and Bovril (estimated $260 million revenue). The divestiture continues Unilever’s portfolio simplification ahead of next month’s ice cream spinoff. Olive Young, Korea’s beauty retail giant, is coming to America with Pasadena and Century City locations. The 1,300-store chain could reshape U.S. K-beauty distribution.
📊 THE DATA DIGEST
Numbers that matter
Q4 Earnings Season
BellRing Brands crushed Q4:
Net sales up 16% to $648M
Premier Protein: +14.9%
Dymatize: +32.9%
FY 2026 guidance: $2.4B
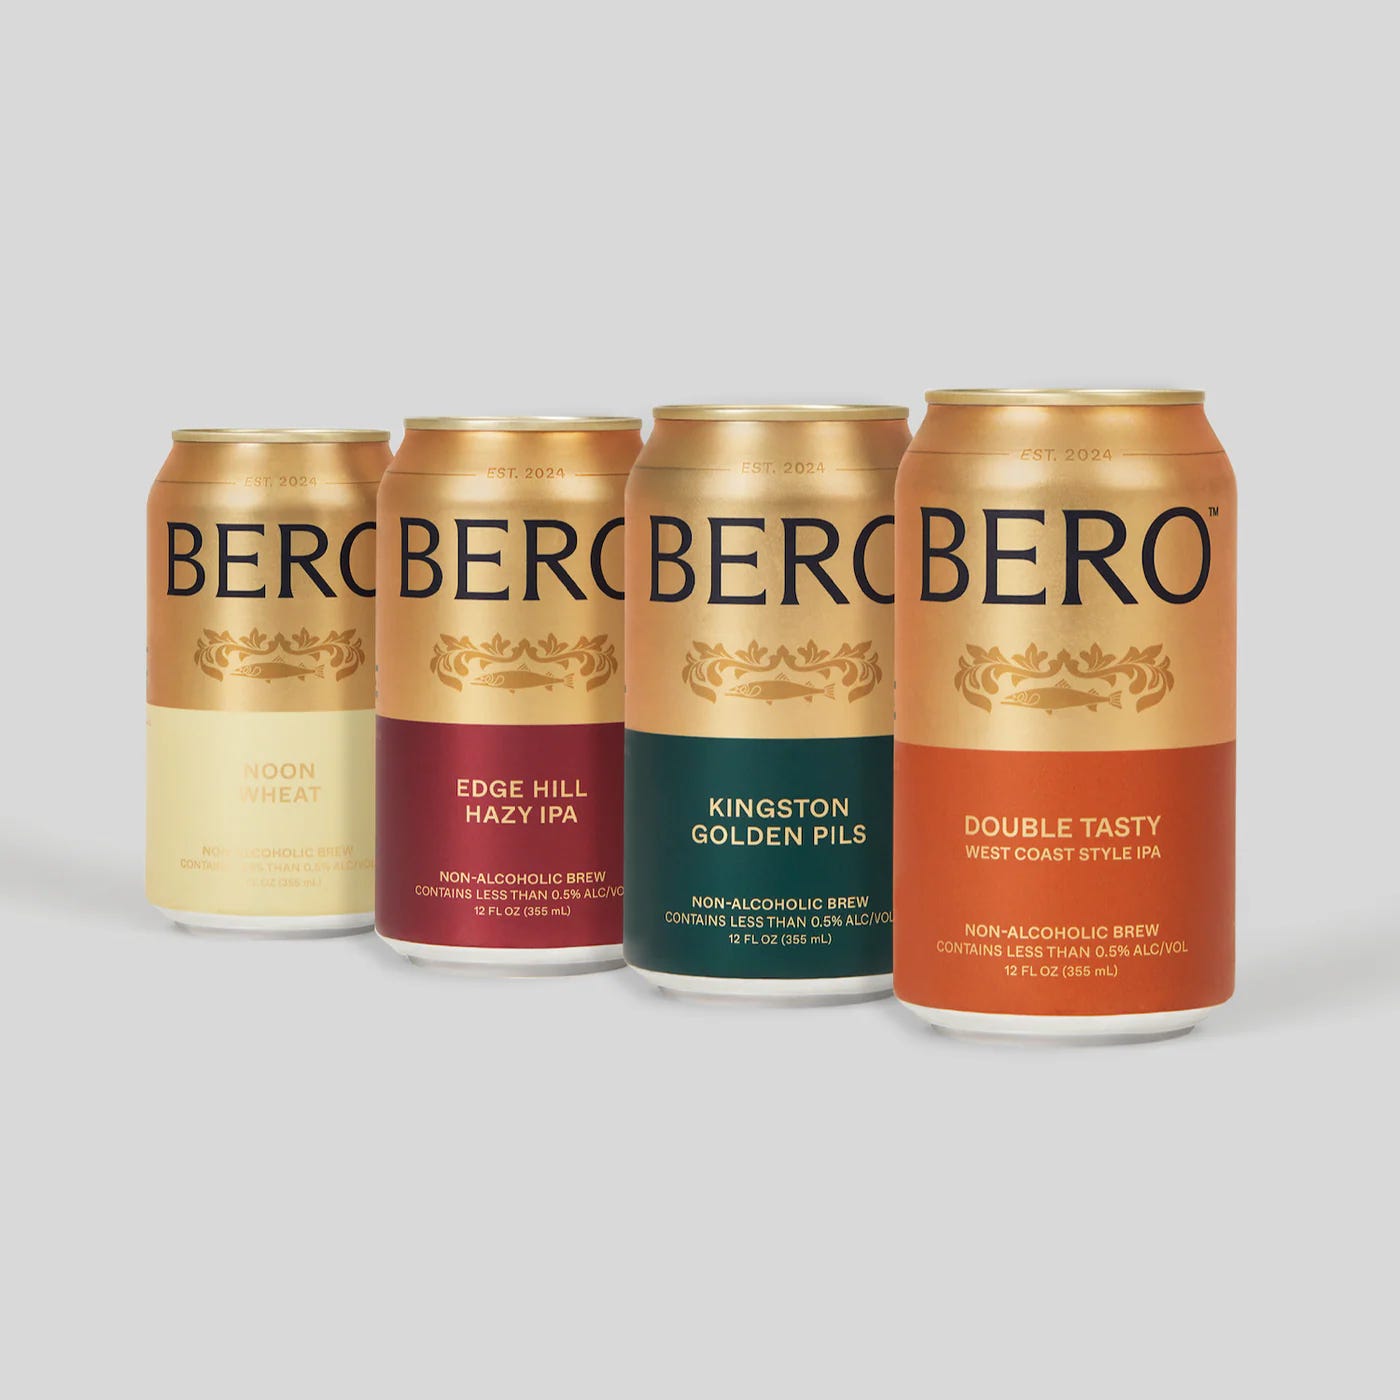
BERO approaching 8 figures in annual revenue after launching October 2024. Now the #2 non-alc beer at Target and partnered with Aston Martin.
The Week’s Metrics
$700M: BeatBox acquisition price
$600M: Prelude’s Fund III
$350M: Monogram’s Fund III
800%: BUM Energy’s YoY growth
$100M: Joyburst’s revenue pace
500: Jobs at BUILT’s new facility
50M: Americans with acne (Oddity’s TAM)
2,000: Doors Aplós added this year
🎙️ FROM THE PODCAST
Coming next week on Unpackaged Goods
We’ll dive deep into the BeatBox exit and what it means for RTD valuations. Plus: Is Suja Life’s IPO brilliant timing or wishful thinking?
🔥 THE HOT TAKE
My unfiltered opinion on this week’s madness
Seven hundred million dollars for Party Punch. That’s the headline, but it’s actually... reasonable? At 2.8x revenue, BeatBox’s exit shows discipline returning to CPG M&A. Compare that to 2021’s delusional multiples and this feels downright conservative.
The fund raising bonanza tells the real story. When Monogram raises $350 million and Prelude closes $600 million, they’re betting on more BeatBoxes. Not moonshots or unicorns – just solid brands building to $200-300 million exits. The fantasy is over. The business is back.
Watch BUILT opening factories while BERO does 8 figures in two months. One builds infrastructure, the other rides cultural waves. Both models work, but only one lasts forever. In Utah, 500 people will have jobs making protein bars. That’s real. That’s sustainable. That’s boring.
Suja filing for IPO feels ambitious. Public markets haven’t been kind to beverage brands. But if they can sell a juice/shots/soda platform story instead of just cold-pressed prayers, maybe Wall Street bites.
The winners this week? The funds with fresh capital, the brands with real revenue, and anyone building actual infrastructure. BUM Energy hiring from Liquid Death and Congo Brands shows talent flowing to momentum. Olive Young, bringing 1,300-store expertise to America, could reshape beauty retail.
Build factories. Raise rationally. Exit realistically. The adults are back.
📺 COMING MONDAY
The Deeter Digest: Week in Review
Breaking down the RTD gold rush and why every fund suddenly has hundreds of millions to deploy.
🥫 ONE MORE THING...
Before you close this tab
Monster is launching a spirits-based RTD called “Just Vibe.” BUILT opened two factories but still makes TikToks. Clebby’s created hemp-infused baking mixes with windowed packaging. The old meets the new meets the weird.
But here’s what matters: Exits are happening. Funds are raising. Brands are building. The CPG carousel spins again, this time with adult supervision.
Until next Sunday, Jonathan Deeter Your CPG-Obsessed Friend
P.S.
Proxies acquired “select assets” from Avec. In M&A speak, that’s “we bought the good parts and left the rest.” Selective asset purchases – another sign of discipline returning to dealmaking.
TikTok | Podcast | Instagram | Pickle Advisors | YouTube
This newsletter is finished with Trophy Wife Finishing Salts - elevating every bite since 2025